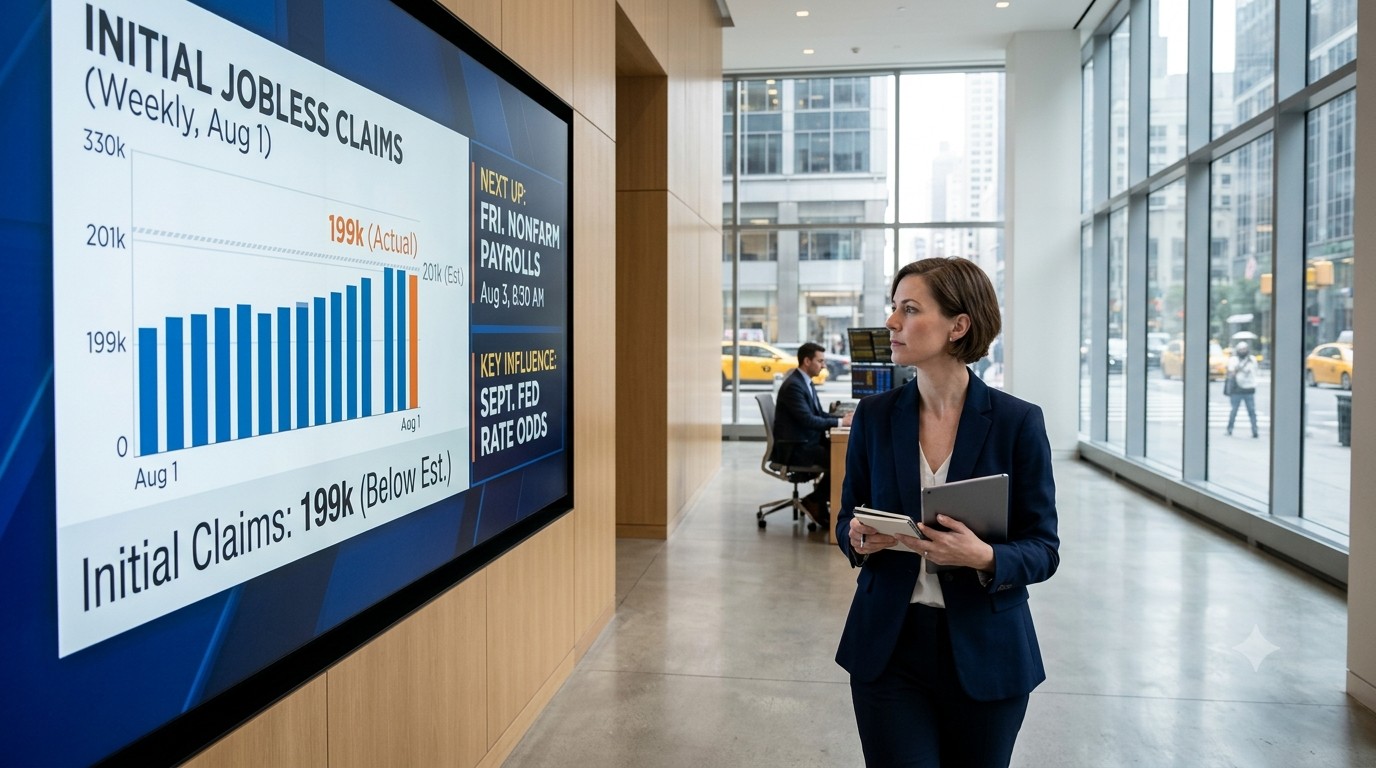
U.S. initial jobless claims ticked higher to 199,000 for the week ended August 1, coming in slightly below the consensus forecast of approximately 201,000. The prior week’s figure had been 197,000. The data indicate continued stability in layoff activity even as other labor-market indicators have shown signs of cooling.
Markets largely took the claims number in stride. Attention remains concentrated on the July nonfarm payrolls report due Friday, where estimates center around 80,000 jobs with a wide range of outcomes possible. A softer payroll print could further reduce the probability of a September rate hike, while a stronger number would reinforce the higher-for-longer narrative.
Recent ADP private-payroll figures had already shown a slowdown, increasing the importance of the official government data. Federal Reserve speakers continue to emphasize that inflation remains above target, keeping policy options open. Futures pricing has moved closer to even odds between no change and a hike at the September meeting.
Equity traders are balancing solid corporate earnings against these macro cross-currents. The claims data themselves are unlikely to drive a sustained move, yet they form part of the mosaic that will shape positioning into the weekend. Treasury yields and rate-sensitive sectors remain responsive to any shift in labor-market momentum.
Overall the report fits a picture of a gradually cooling but still resilient labor market. Investors will parse the payrolls details—including unemployment rate, wage growth, and revisions—for clearer signals on the Federal Reserve’s next steps.