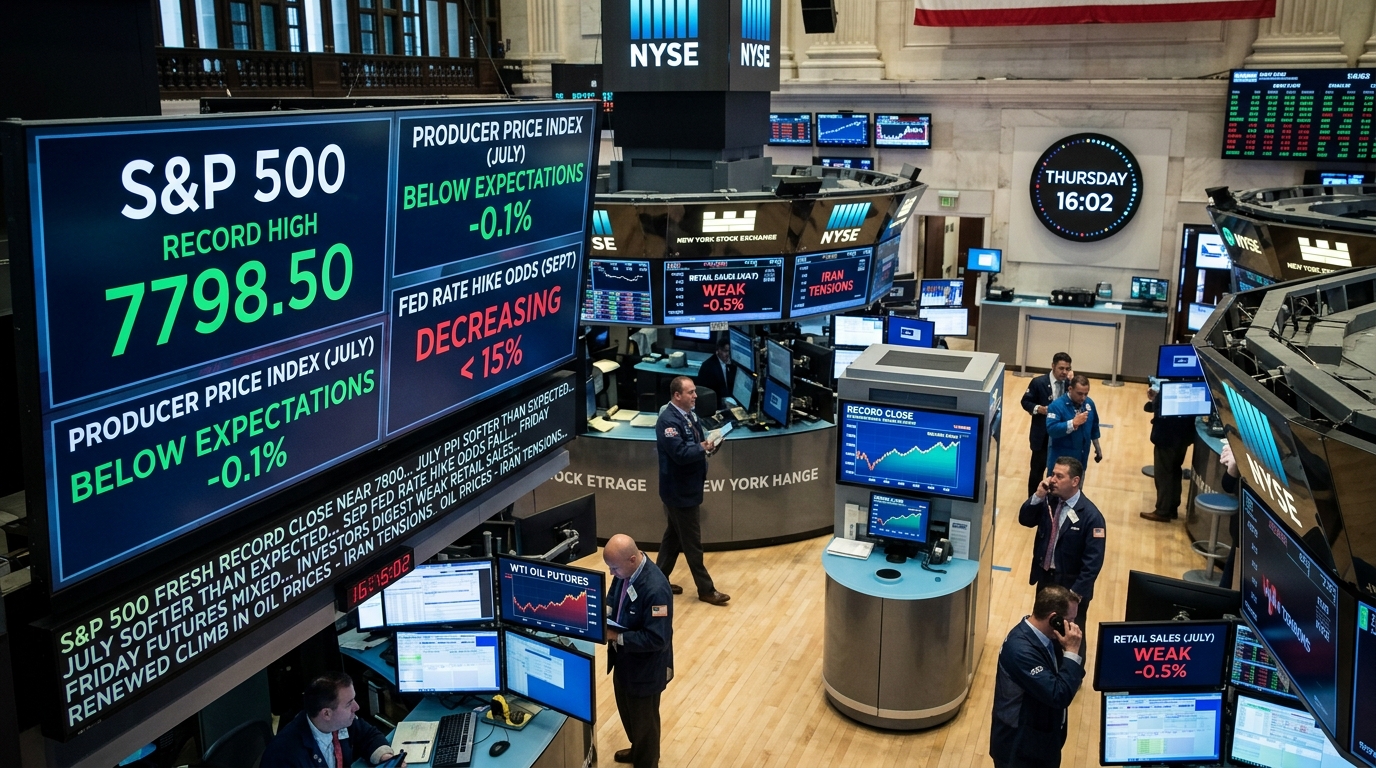
The S&P 500 closed at a record high near 7800 on Thursday after the producer-price index for July was unchanged month-over-month, cooler than the modest increase economists had anticipated. The softer wholesale-inflation reading lowered the market-implied probability of a Federal Reserve rate hike at the September meeting and helped propel both the S&P 500 and Nasdaq higher.
Technology and communication-services sectors led the advance, extending the recent AI-driven momentum. The Dow also finished positive, snapping a short losing streak. Overnight and early Friday, equity futures turned mixed as the weaker-than-expected July retail-sales print and a fresh rise in crude oil prices introduced competing cross-currents.
Traders are now pricing roughly a two-thirds chance that the Fed will keep the policy rate unchanged next month. At the same time, elevated oil prices linked to US-Iran developments keep a residual inflation risk alive, preventing yields from falling more decisively. The combination leaves the market in a classic tug-of-war between supportive rate expectations and geopolitical energy premiums.
With the S&P 500 and Nasdaq on track for a third consecutive weekly gain, positioning into the weekend remains cautious. Volume and breadth will be watched closely for signs that the record-high close can be sustained or whether the retail-sales miss and oil rebound prompt profit-taking. Sector rotation between growth, energy and defensive names is likely to remain active.
Overall, the backdrop still favors selective risk-taking in AI-related and quality-growth names, but the fresh data and geopolitical headlines argue for disciplined position sizing and attention to intraday levels.