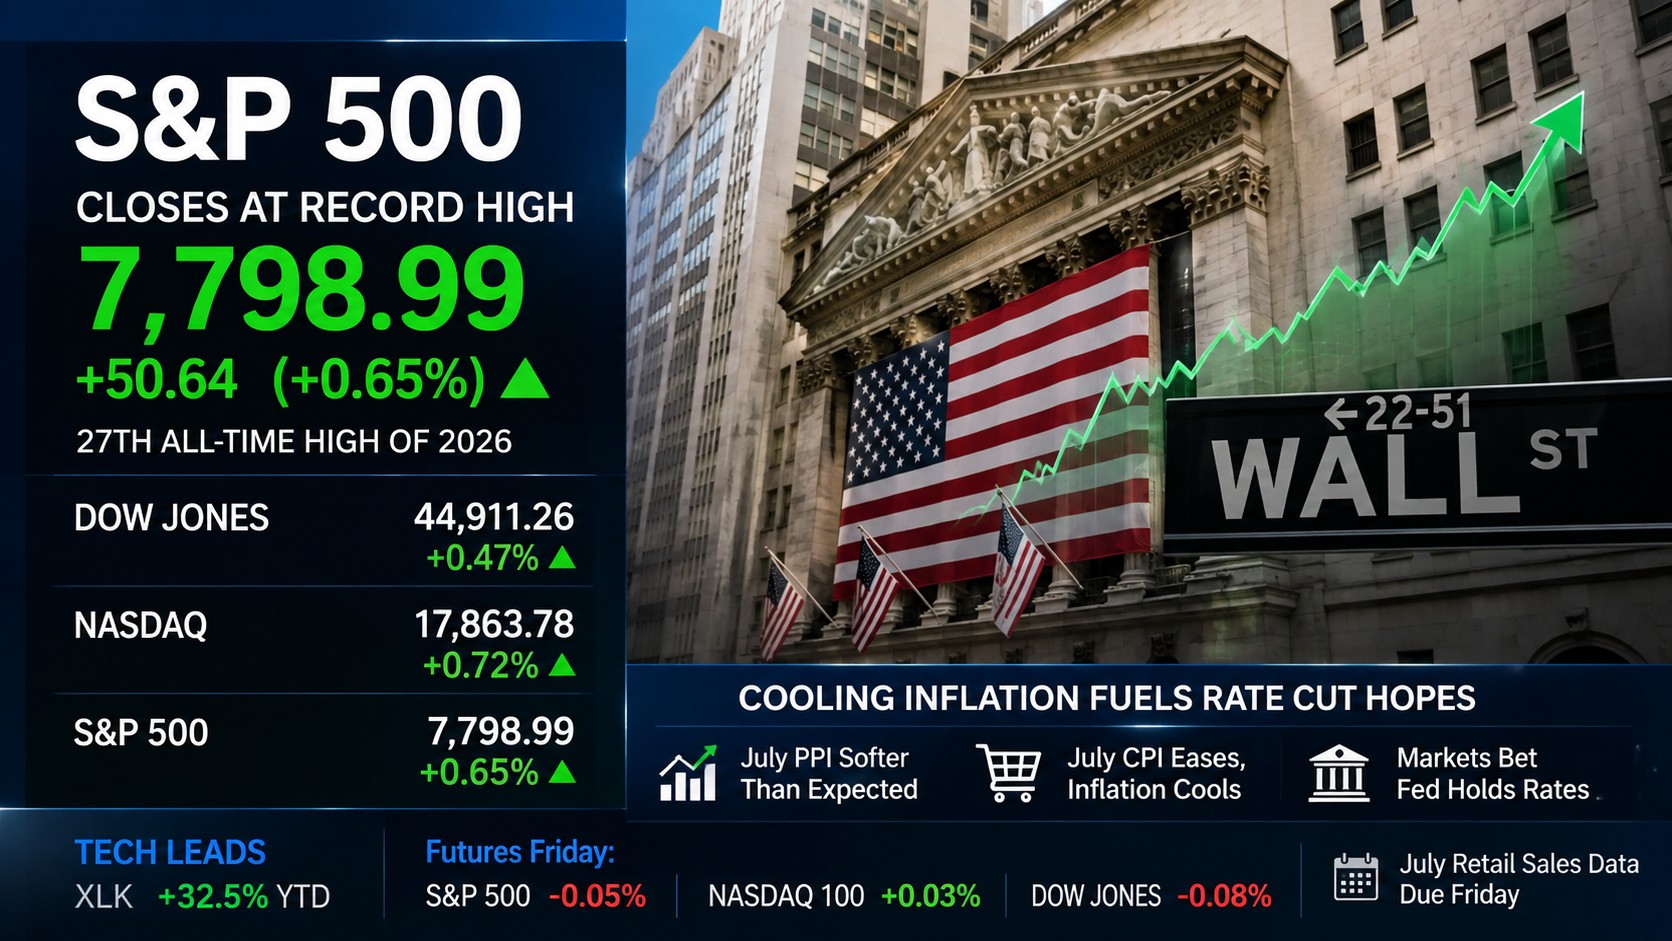
The S&P 500 closed at a record 7,798.99 on Thursday, its 27th all-time high of the year, as cooling inflation data reinforced investor bets that the Federal Reserve will hold interest rates steady in September. The benchmark index gained 50.49 points, or 0.65%, extending a rally that has been fueled largely by strength in technology shares.
The Dow Jones Industrial Average added 69.72 points, or 0.13%, to close at 53,839.99, while the Nasdaq Composite outperformed with a 214.54-point gain, or 0.81%, finishing at 26,803.03. The Russell 2000 also advanced, rising 7.37 points, or 0.24%, to 3,052.86, suggesting the rally has broadened beyond mega-cap names.
Technology remained the standout sector, with the Technology Select Sector SPDR Fund up 32.5% year-to-date, according to trading data cited in morning market commentary. Energy stocks also had a strong week, climbing more than 6%, while healthcare and financial shares each rose more than 1%.
The rally has been underpinned by a string of softer-than-expected inflation reports. The July Producer Price Index came in flat on a monthly basis, with core PPI rising just 0.2%, below consensus estimates. That followed a similarly benign Consumer Price Index report earlier in the week and weaker-than-expected employment data the previous Friday, all of which have fed expectations that the Fed's rate-hiking cycle may be over for now.
Attention now turns to a fresh batch of economic data due Friday, including July retail sales, which economists expect to show a 0.1% monthly increase, down from 0.2% in June. Retail sales excluding autos are projected to rise 0.2%, a reversal from the prior month's 0.2% decline. The University of Michigan's preliminary August consumer sentiment reading, along with its closely watched inflation expectations survey, is also due at 10 a.m. ET.
Overseas, Asian markets extended the positive momentum overnight. Japan's Nikkei 225 advanced 405 points to 68,713, while South Korea's Kospi index, viewed as a bellwether for the artificial intelligence trade, climbed further after a week in which it and other regional chip-linked shares posted double-digit gains. The Shanghai Composite was little changed, and Hong Kong's Hang Seng slipped modestly. In Europe, Germany's DAX rose while London's FTSE 100 dipped slightly in early trading.
Futures pointed to a mixed session ahead of the opening bell, with Dow futures down slightly and S&P 500 and Nasdaq futures little changed to modestly higher. Treasury yields held near recent highs, with the 10-year note yielding around 4.65%, even as rate-cut expectations firmed. Gold slipped, while oil prices were roughly flat as investors weighed geopolitical tensions in the Middle East against demand concerns.
Portfolio strategists note that record after record raises the bar for continued gains, and that markets increasingly need confirmation from upcoming data, including retail sales and consumer sentiment figures, to justify current valuations. With earnings season winding down and the Fed's next policy meeting still weeks away, near-term direction may hinge on incoming economic releases rather than corporate results.