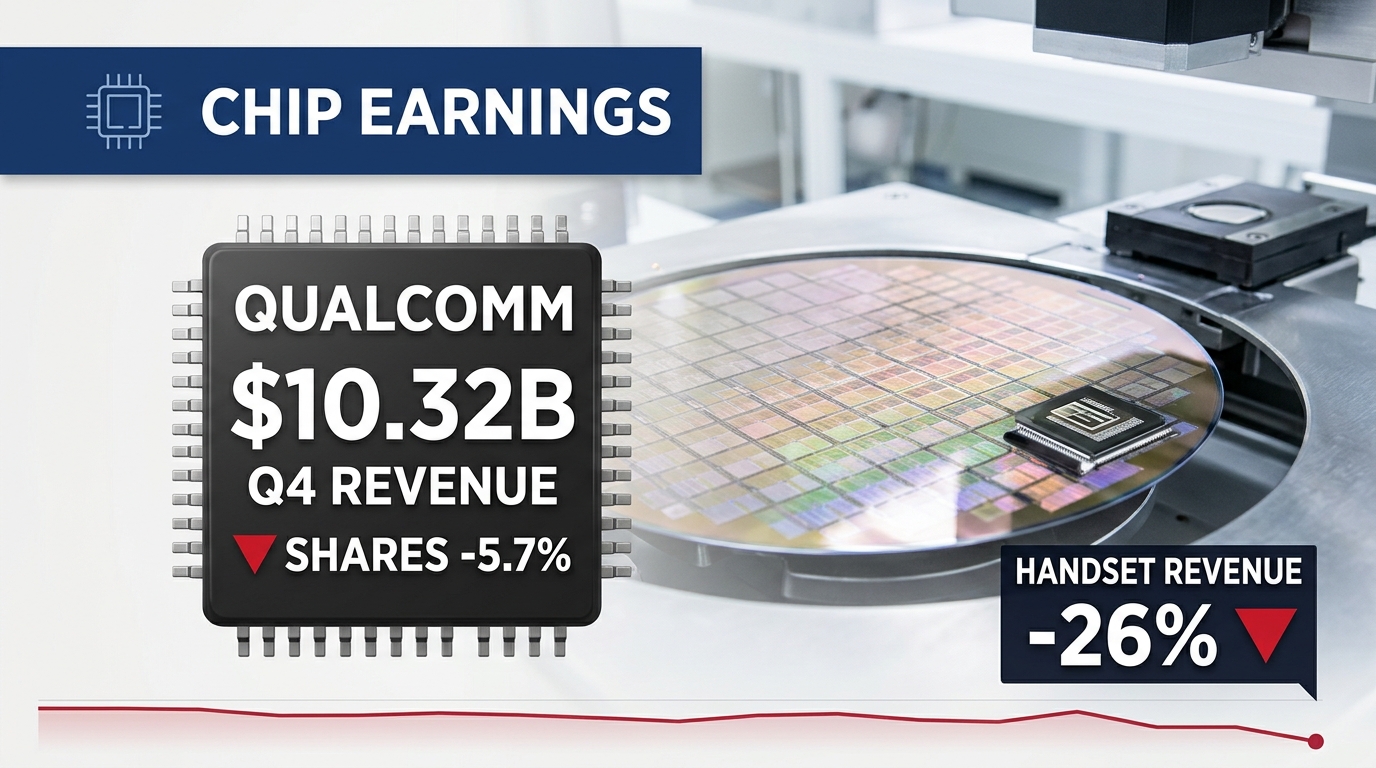
Qualcomm reported fiscal fourth-quarter results that topped Wall Street's expectations, but investors focused on a first-quarter earnings forecast that came in below consensus. The chipmaker posted adjusted earnings of $2.17 per share on revenue of $10.32 billion, compared with analyst estimates of $2.16 and $10.12 billion, Yahoo Finance reported. A year earlier it earned $3.00 per share on revenue of $11.27 billion.
Guidance was mixed. Qualcomm projected first-quarter revenue of $10.4 billion to $11.2 billion, with a midpoint ahead of the $10.6 billion Wall Street had expected. Adjusted EPS guidance of $2.15 to $2.35, however, has a midpoint of $2.25, below the $2.32 analysts were looking for. InvestingLive reported that full-year capital spending also came in well above forecasts, which compounded the reaction. Shares closed Wednesday at $173.19, up 5.33%, before sliding to about $163.28 in after-hours trading.
The segment detail shows the smartphone squeeze. Revenue in the QCT chip segment, which includes handsets and automotive, fell 8% year over year to $9 billion but beat the $8.8 billion estimate. Handset revenue dropped 26% to $5.1 billion, short of the $5.3 billion analysts expected, while the QTL licensing business generated $1.3 billion. Automotive sales rose 89% to $2 billion. Qualcomm's own release said combined automotive and IoT revenue grew 36% year over year.
Management emphasized diversification. For fiscal 2026, Qualcomm reported GAAP revenue of $43.1 billion and non-GAAP EPS of $10.54, and said non-handset revenue is projected to grow more than 60% in fiscal 2027. It reiterated its fiscal 2027 data center revenue target of $5 billion and announced renewed long-term licensing agreements with Apple, Huawei and Transsion.
The company is pursuing a series of partnerships. On Wednesday it announced a deal to provide technology to SpaceX's Starlink as the satellite company builds a terrestrial network. In late October it said it was working with Anduril on a laptop line focused on reshoring computer manufacturing, and in September it signed an agreement with Amazon for custom chips for AWS AI infrastructure.
The backdrop is a memory and storage shortage that has forced consumer electronics makers to raise prices, sending demand lower. Apple said on Monday that the memory crisis will continue to cut into margins, while Intel and AMD said they expect PC sales to decline in the coming quarter. Intel shares plunged nearly 29% in response, its worst day since 1974.
The setup for Thursday: the stock ran higher into the print, rising 5.33% on Wednesday, so a roughly 6% after-hours drop partly gives back that gain. For chip investors already rattled by a 12% three-day slide in the semiconductor index and fresh concern over data center regulation, Qualcomm's results reinforce a split market in which diversification stories such as automotive and data center are rewarded for revenue but must still deliver margin. Investors will look for management commentary on memory costs, handset demand into the holiday quarter and the timing of data center revenue.