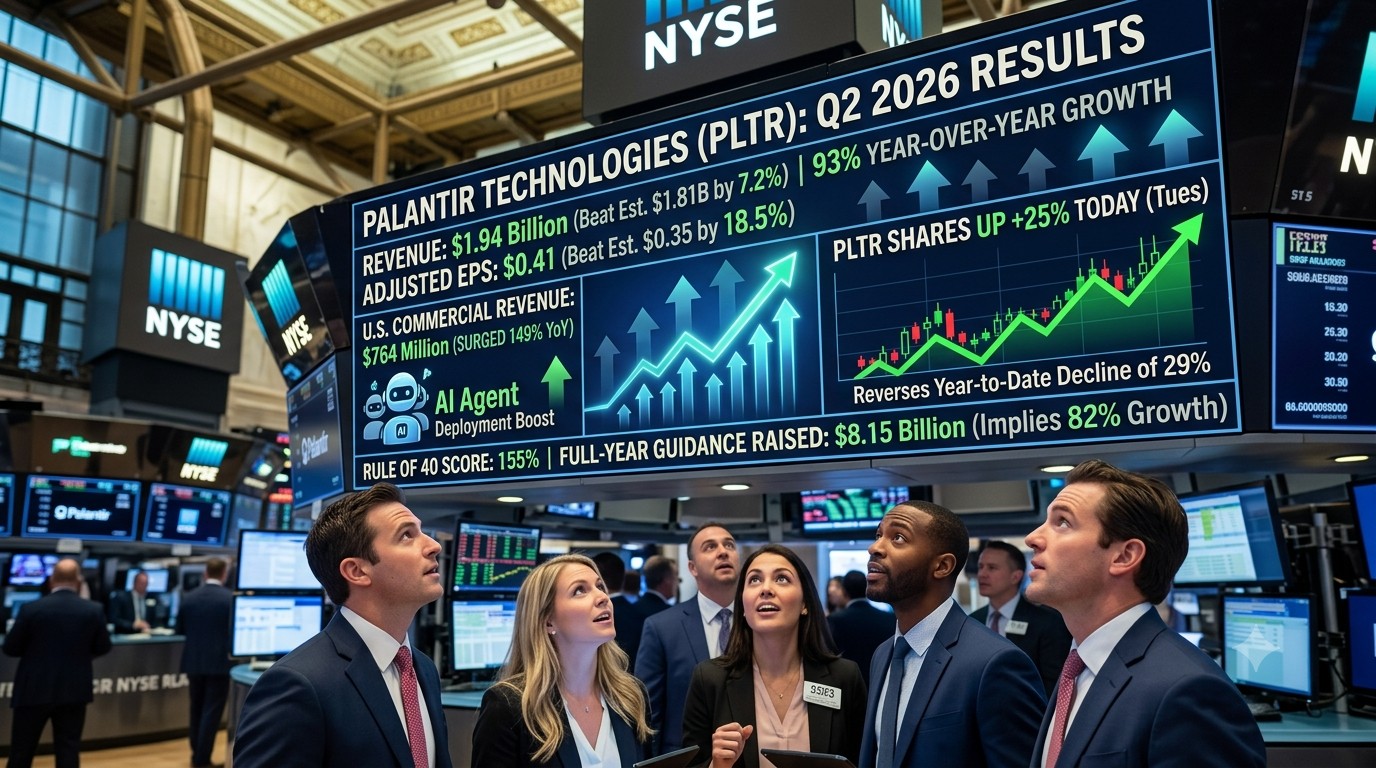
Palantir Technologies reported second-quarter 2026 results after the bell Monday that exceeded consensus estimates across every key metric and validated the company's position as the dominant enterprise AI software platform of the current cycle. Revenue of $1.94 billion rose 93% year-over-year and beat the $1.81 billion Wall Street estimate by approximately $130 million. Adjusted earnings per share of $0.41 topped the $0.35 consensus by 18.5%. The stock surged more than 12% in after-hours Monday and extended those gains to more than 25% in Tuesday trading as investors recalibrated expectations for AI software economics.
The quarter's defining metric was U.S. commercial revenue, which soared 149% year-over-year to $764 million — a figure that, on a compounded basis, represents 380% growth since 2024. U.S. government revenue grew 90% year-over-year to $809 million, driven by defense and intelligence agency deployments. GAAP operating income reached $912 million at a 47% margin, an extraordinary level of profitability for a hypergrowth software company, while adjusted operating income hit $1.19 billion at a 62% margin. Total contract value of $3.37 billion rose 49% year-over-year, providing strong forward revenue visibility.
Palantir's Rule of 40 score — a standard SaaS metric that combines revenue growth rate and free cash flow margin, where a score above 40 is considered exceptional — reached 155%, placing the company among the highest-scoring enterprise software businesses ever measured by the metric. CEO Alex Karp did not understate the moment: "Forget consensus. To my knowledge, no businesses at our scale has even grown half this much," he told CNBC's Seema Mody following the earnings call.
Management raised full-year 2026 revenue guidance to $8.15 billion to $8.16 billion, representing 82% year-over-year growth and implying more than $500 million of upward revision versus prior guidance. U.S. commercial revenue guidance was lifted to in excess of $3.42 billion, up from prior guidance of $3.22 billion, implying at least 134% year-over-year growth in the company's most strategically significant segment. Adjusted free cash flow guidance was set at $4.50 billion to $4.70 billion for the full year.
For Q3 2026, Palantir guided revenue of $2.16 billion to $2.164 billion, well above the prior consensus estimate, and adjusted income from operations of $1.292 billion to $1.296 billion. The Q3 guidance implies sequential acceleration — a pattern inconsistent with the deceleration narrative that had weighed on PLTR shares through much of July, during which the stock had declined approximately 29% year-to-date ahead of the print.
The Palantir result carries broad implications for enterprise AI software valuations. The company's AIP Bootcamp — its signature five-day sales tool with a roughly 75% conversion rate — is clearly generating demand at a pace that management's own guidance framework is struggling to fully capture. For investors evaluating AI software exposure entering the second half of 2026, the combination of 93% revenue growth, 155% Rule of 40, and an $8.15 billion annual guidance midpoint positions Palantir as the most quantitatively compelling AI software case in the public market today.