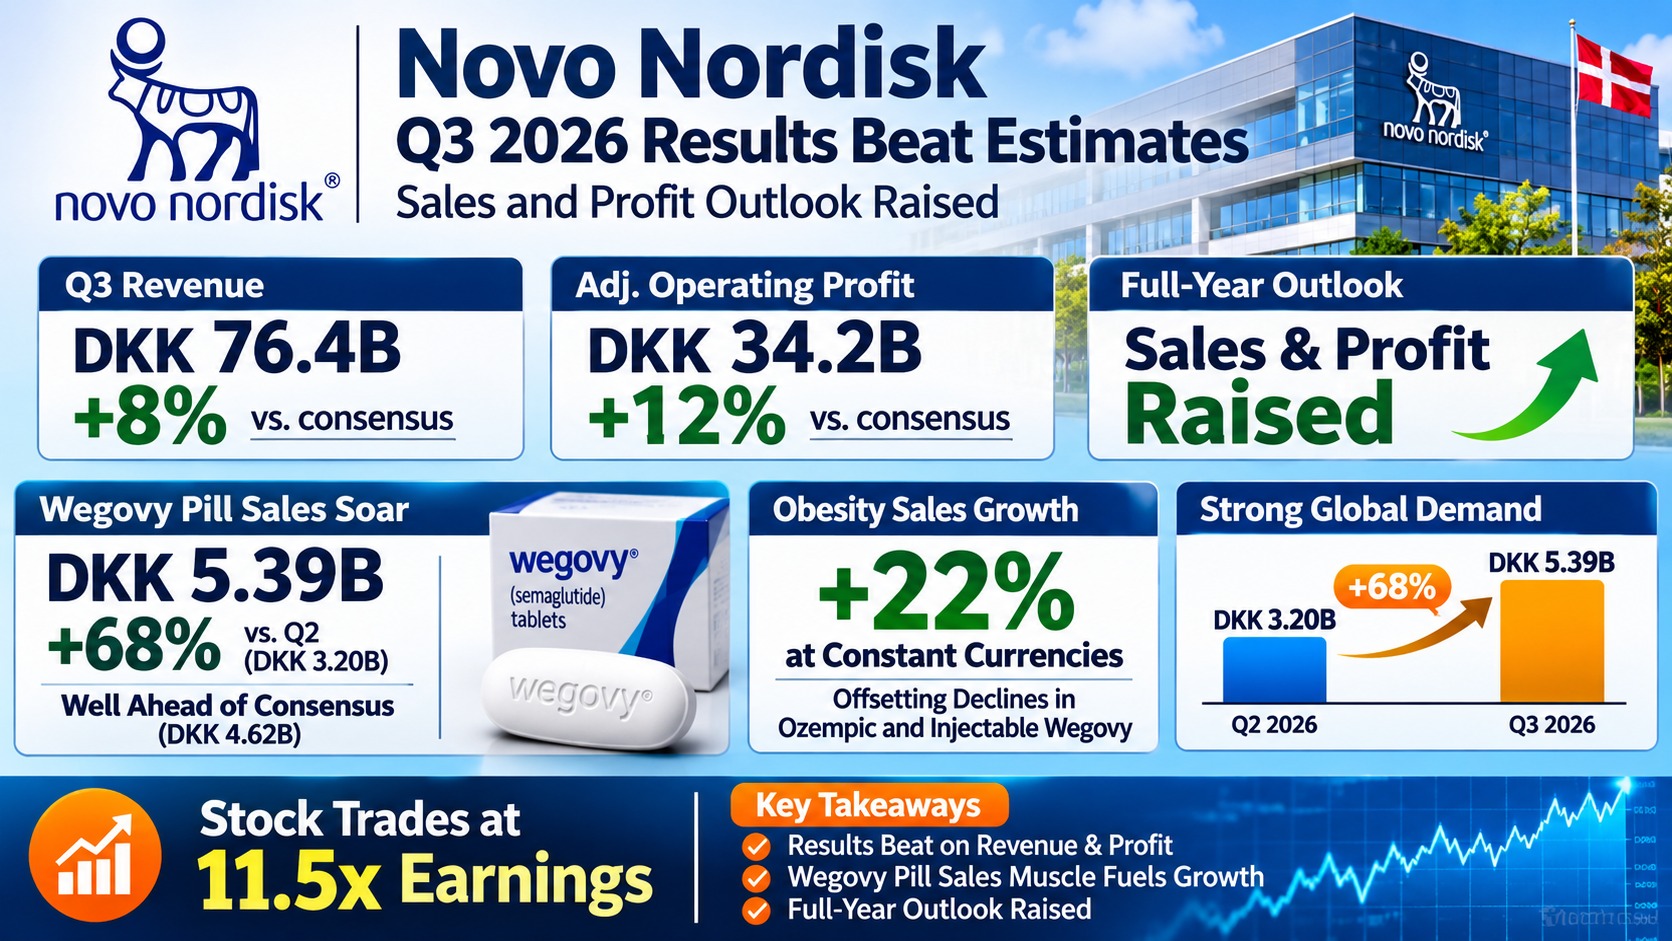
Novo Nordisk delivered a stronger third quarter than the market expected, reporting adjusted operating profit above forecasts and raising its full-year profit and sales outlook, according to Reuters. Revenue came in about 8% above consensus, adjusted operating profit beat by roughly 12%, and the Associated Press reported quarterly profit of $2.58 billion for the Wegovy maker.
The standout was the oral version of its obesity drug. Wegovy pill revenue reached DKK 5.39 billion, about 68% higher than the DKK 3.22 billion booked in the second quarter and well above the DKK 4.62 billion analysts had projected, a beat of roughly 17%. According to one post-earnings review, the pill is now large enough to offset weakness elsewhere in the portfolio, a key point for a company that has been working to stabilize its business while rebuilding growth.
That weakness was visible in the legacy franchises. At constant currencies, injectable Wegovy sales fell 2%, Ozempic declined 5% and total diabetes sales dropped 5%. Even so, obesity care remained the engine of growth, with sales rising 22% at constant exchange rates. The mix shift toward the pill matters because it broadens the patient base and gives Novo a second route to market as competition in the category intensifies.
The profit picture needs careful reading. At constant currencies, total revenue grew 4% and adjusted operating profit climbed 27%. Adjusted earnings per share, however, fell 12%, an outcome also affected by weaker financial income. Year-ago comparisons were distorted by roughly DKK 9 billion of restructuring costs that remain in the adjusted operating profit comparison, which flatters the year-over-year growth rate. Novo strips restructuring costs out when calculating adjusted EPS, so the two measures do not move in lockstep.
Management’s decision to lift guidance for 2026 is the most forward-looking signal in the report. It follows a prior raise earlier in the year, when the company upgraded its adjusted sales and adjusted operating profit outlook in August, and it suggests that demand for the oral product is tracking ahead of internal plans. Investors will look for detail on supply, pricing and prescription trends on the earnings call.
Valuation is part of the appeal. At the November 3 Copenhagen closing price of DKK 270.15, Novo traded at roughly 11.5 times earnings, a low multiple for a company still growing obesity revenue at a double-digit pace. That discount reflects concerns about pricing pressure and the decline in injectable products, and a beat-and-raise quarter challenges some of those fears.
For U.S. investors, the report lands on a day when healthcare shares were rising in premarket trading as markets assessed a Democratic-controlled House and potential shifts in healthcare policy. Novo’s American depositary receipts trade in New York, so the earnings reaction and the policy backdrop could reinforce each other. The key risks remain further erosion in Ozempic and injectable Wegovy and the pace at which the pill can scale. This article is informational and does not constitute investment advice.