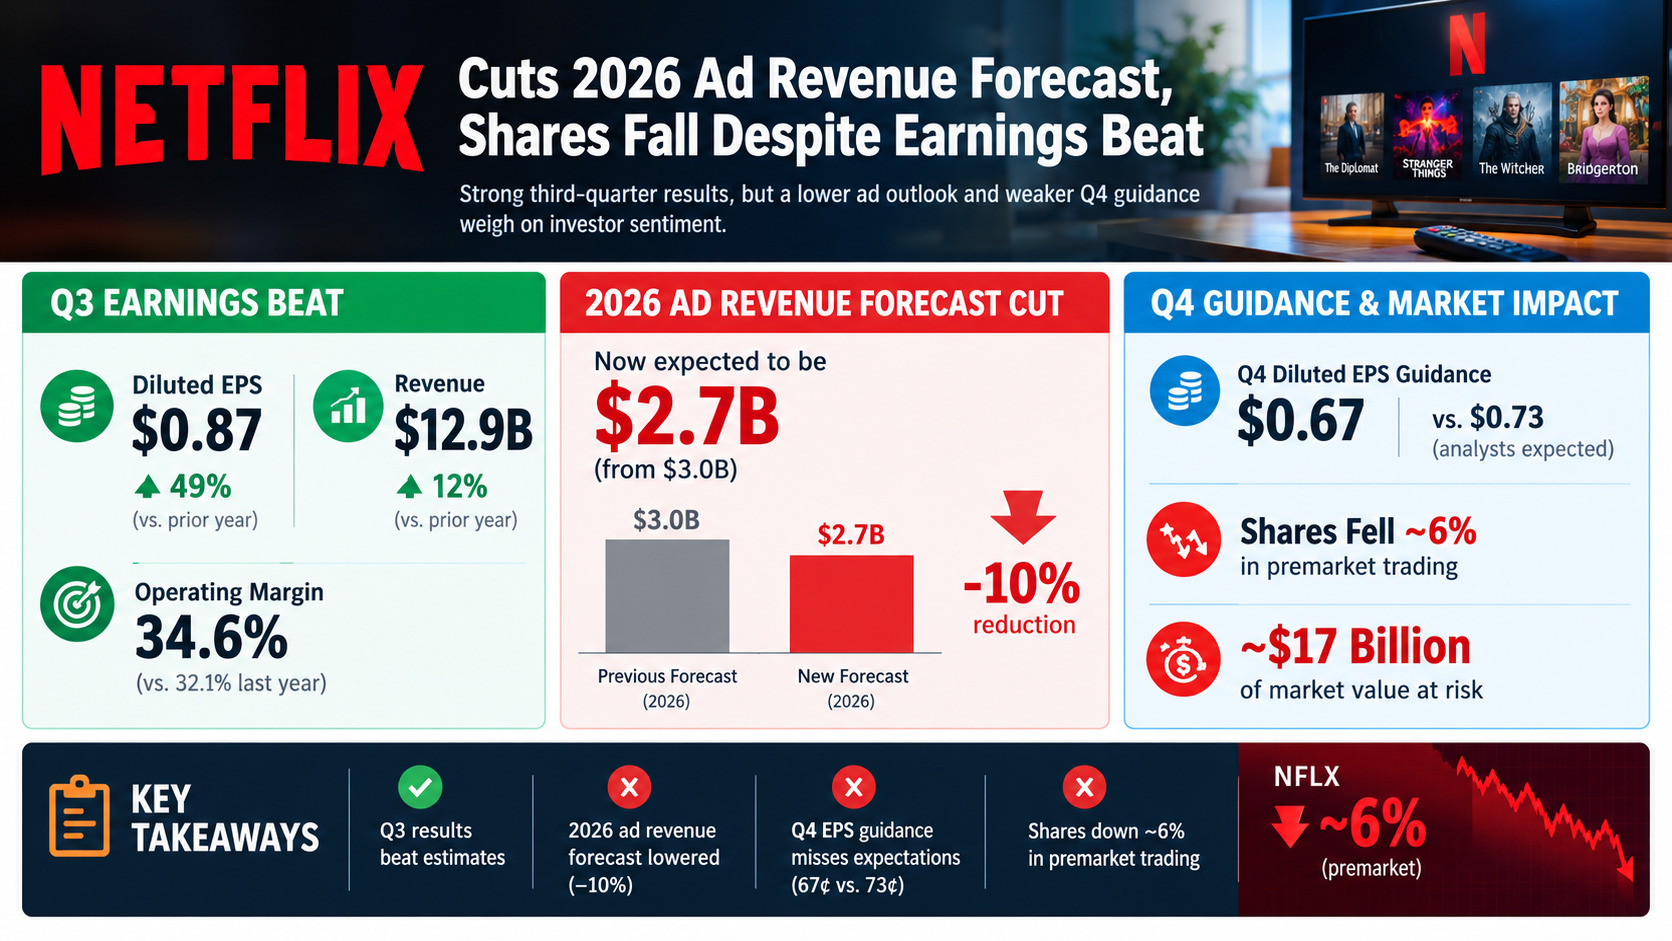
Netflix (NFLX) reported third-quarter 2026 results on Tuesday that topped profit expectations but included a lower advertising forecast and a fourth-quarter profit outlook below analyst estimates, sending the shares down about 6% in Wednesday premarket trading. The stock closed at $68.69 on Tuesday, according to StockTitan, and was already down more than 26% year to date.
Revenue was $12.87 billion, up about 12% from a year earlier and in line with the company’s own forecast of $12.86 billion. Exchange4media noted that the growth rate was the slowest in three years. Operating income rose 37% to about $4.46 billion, and operating margin expanded to 34.6% from 28.2% a year earlier, which Netflix said was ahead of its forecast mainly because of the timing of expenses. Diluted earnings per share were $0.87, up 49% from $0.59, against the company’s own forecast of $0.82.
The disappointment came from the outlook. Netflix lowered its 2026 advertising revenue forecast to roughly $2.7 billion from about $3 billion, citing a slower-than-expected rollout of some advertising capabilities and partner integrations. A co-CEO acknowledged the company is behind aggressive targets in advertising, according to TheStreet. Management still expects advertising revenue to grow more than 80% this year and said the ad tier will expand to nine more countries in March 2027.
For the fourth quarter, Netflix guided to revenue of $13.44 billion, up about 11.5%, and an operating margin of 26.0%, including a drag of roughly 120 basis points from headcount reductions. It forecast net income of $2.79 billion, or 67 cents per share, below analyst expectations of $3.07 billion and 73 cents, according to Reuters. The company reiterated full-year 2026 revenue of $51.1 billion, up 13%, with an operating margin of 31.5%. It trimmed its free cash flow outlook to $12.0 billion from $12.5 billion, citing the timing of a real estate transaction.
Netflix repurchased 63.9 million shares for $4.8 billion in the quarter and generated $2.9 billion in free cash flow. Management pointed to growth in India, where view hours rose 24% year over year, and to a slate that includes live events and third-party licensing.
Investing.com estimated that a 6% premarket decline would erase roughly $17 billion of market value. The reaction underscores how sensitive the stock has become to growth signals this year, with investors focused on whether advertising can accelerate enough to offset slowing subscription growth.
Traders should note that the quarter itself was solid; the debate is about forward earnings power and the credibility of the ad ramp. The shares are trading in a market where the 10-year Treasury yield sits near 5.1% and Brent crude is around $110, conditions that tend to compress multiples for growth names. Key items to watch include the stock’s reaction at the open, whether buyers step in near recent lows, and any analyst price-target changes later today.
This article is for informational purposes only and does not constitute investment advice.