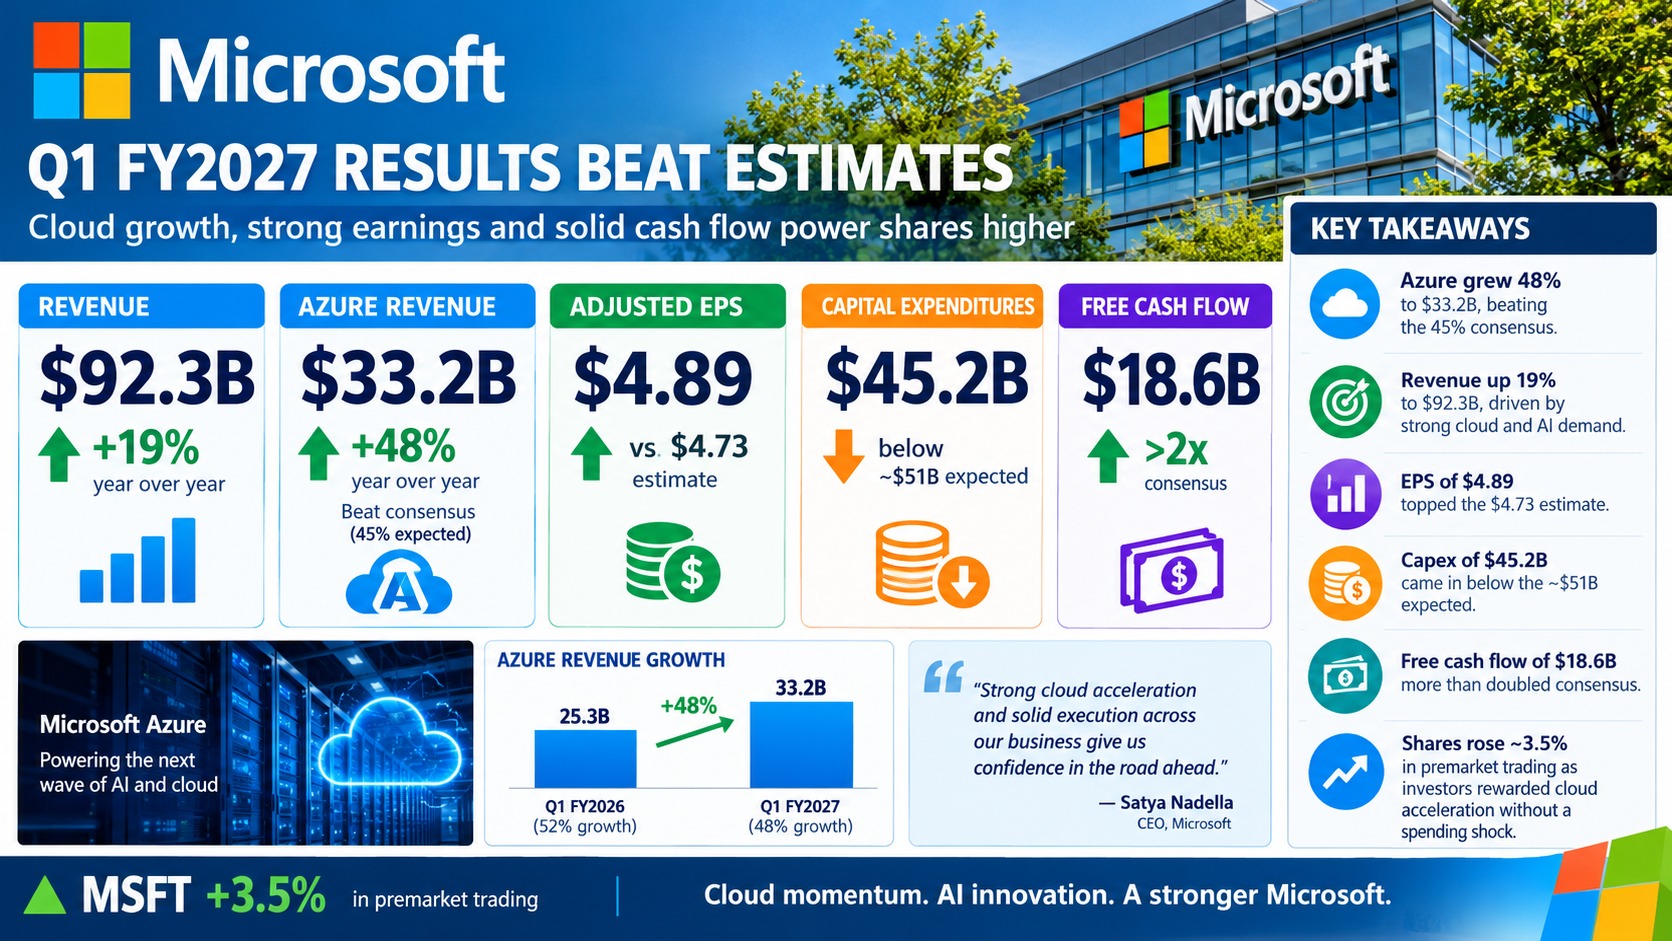
Microsoft reported fiscal first-quarter 2027 results on Wednesday that combined accelerating cloud growth with lower-than-expected capital spending, and the shares were up roughly 3.5% in Thursday premarket trading. Revenue reached a record $92.3 billion, up 19% from a year earlier and above the $90.6 billion consensus, while adjusted earnings per share of $4.89 topped the $4.73 estimate. Net income rose 32% on a GAAP basis to $36.6 billion, or $4.92 per share.
Azure was the centerpiece. For the first time Microsoft disclosed Azure revenue in dollars, reporting $33.2 billion for the quarter, ahead of the $32.3 billion analysts had projected. Growth accelerated to 48% in constant currency from 43% in the prior quarter and beat the 45% consensus. Microsoft Cloud revenue reached $63.9 billion, up 30%, and Microsoft 365 commercial cloud revenue grew 18% in constant currency, about one percentage point above expectations, with pricing and mix gains from Copilot, E5 plans and usage-based products such as GitHub Copilot. Management credited efficiency gains across its GPU and CPU fleet that freed capacity for customers, even as third-party capacity delays limited supply. Demand still exceeds supply, according to the company.
Spending was the other focus. Capital expenditures including finance leases totaled $45.2 billion, up about 30% from a year earlier but below the roughly $51 billion analysts expected. CFO Amy Hood said around three-quarters of the outlay went to short-lived assets such as memory chips and storage, and the company added 24 new data centers worldwide during the quarter. Free cash flow was $18.6 billion, well above the $8.3 billion consensus. The combination matters because Alphabet's report the same evening showed the opposite pattern, with capital spending outrunning cash generation and the shares falling about 10% premarket.
Contracted demand also remained large. Commercial remaining performance obligation rose 73% to $677 billion, representing future revenue committed under existing contracts. TechCrunch reported that Microsoft recorded about $10 billion in revenue from OpenAI during the quarter and noted that Anthropic also runs on Azure. That customer concentration among AI labs is a variable investors will keep monitoring. AFP noted that the results arrived days after Microsoft offered voluntary buyouts to more than a quarter of its workforce, which is part of the cost backdrop to the quarter.
Analysts moved quickly after the print. Guggenheim raised its price target to $595 and Citizens lifted its target to $625, citing the Azure acceleration and cash-flow strength. The stock's gain stood in contrast to a Nasdaq-100 futures decline of roughly 1% driven by Alphabet. Google Cloud revenue of $30.7 billion is now close to Azure's $33.2 billion, a reminder that competition for AI workloads is intensifying even as both businesses grow quickly.
For investors, the quarter shifts the debate from whether Microsoft is overspending to whether supply constraints cap Azure growth. Key watch items include the pace of capital spending in coming quarters, the share of AI-lab customers in the backlog, and how rate-sensitive technology valuations respond to Thursday's inflation and growth data, given market pricing of a December Federal Reserve hike near 85%. Amazon, which reports after the close, will provide another read on cloud demand and the return on AI infrastructure spending.
This article is for informational purposes only and is not investment advice.