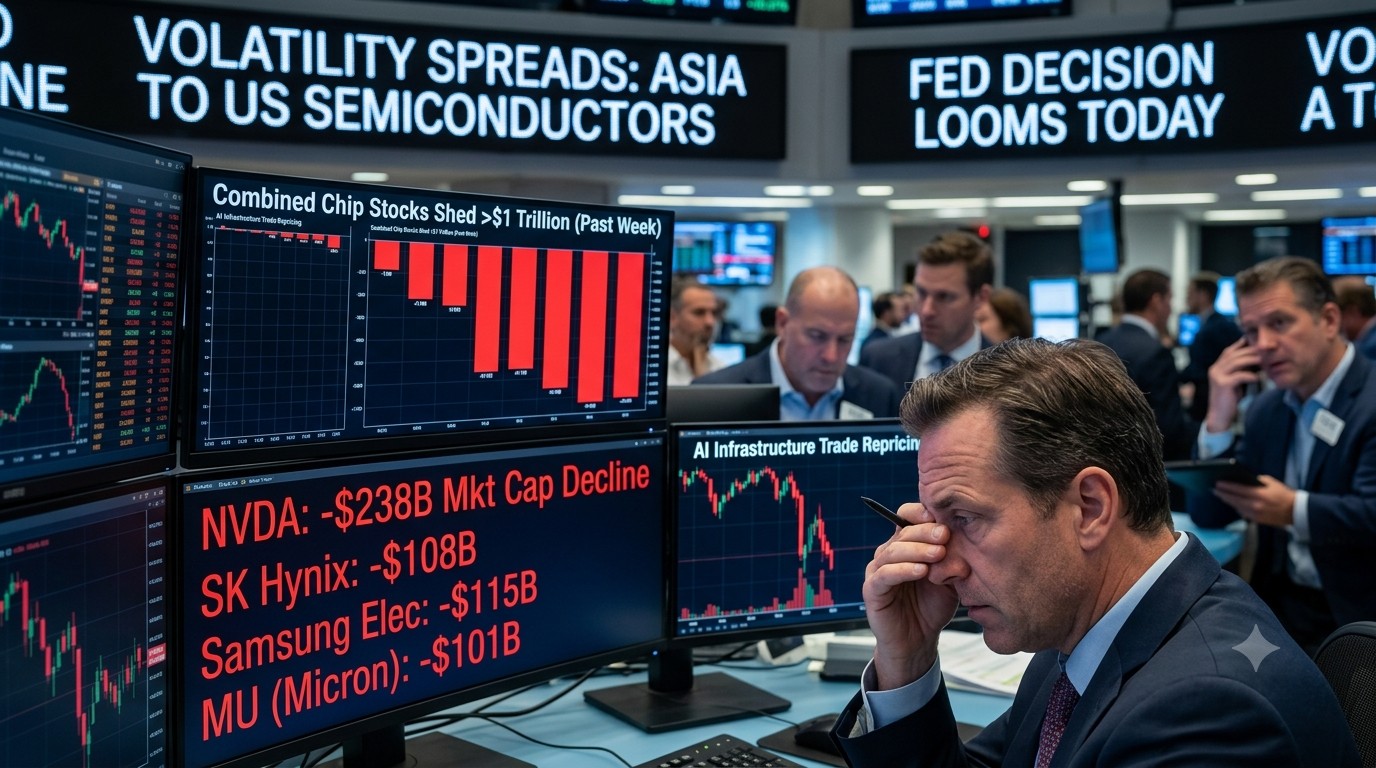
Microsoft and Meta Platforms are both scheduled to report second-quarter 2026 results after today's market close, in what analysts are calling one of the most consequential earnings sessions of the year. The reports land just hours after the Federal Reserve's latest interest rate decision, with Fed Chair Kevin Warsh set to hold his first press conference since being confirmed to the role. Markets currently assign roughly a 30% probability to a rate hike at this meeting, an unusually elevated figure for a Fed that held rates steady in June.
Wall Street consensus calls for Microsoft to post fiscal fourth-quarter earnings per share of $4.24, up about 16% year-over-year, on revenue near $87.6 billion, an increase of roughly 15%. Meta is expected to report earnings per share of $7.18 on revenue of about $60.2 billion, up 27% from a year earlier. Both companies carry Strong Buy consensus ratings, and analysts estimate roughly 95% odds that each will beat headline estimates, a figure high enough that the earnings beat itself is unlikely to move either stock meaningfully.
The real swing factor for both companies is capital expenditure guidance for fiscal 2027. Microsoft has already guided to roughly $190 billion in calendar-year 2026 capital spending, largely tied to AI infrastructure, and some analysts model fiscal 2027 capex approaching $262 billion. Investors will also focus on Azure cloud growth, where management had guided to constant-currency growth in the high 30% range. Meta, meanwhile, has guided full-year 2026 capital expenditure to a range of $125 billion to $145 billion, and traders will watch whether Reality Labs losses and AI infrastructure costs compress operating margins from the prior quarter's level above 41%.
Both stocks enter the print under pressure. Microsoft closed last week around $381.70, more than 30% below its record high, and has traded below every major moving average since a steep decline in June. Meta has fallen for seven consecutive sessions and sits roughly 25% off its own record close. The pattern this earnings season has been unforgiving: Alphabet posted 24% revenue growth in its own recent report and still saw its shares sold off after raising capital spending guidance, a reminder that investors are currently grading AI-exposed megacaps on spending discipline as much as on growth.
The outcome carries implications beyond the two companies themselves. A reassuring capital spending update from either Microsoft or Meta could help stabilize sentiment across a broader technology and semiconductor complex that has already lost more than $1 trillion in combined value this week. A disappointing update, on the other hand, would likely deepen the current rotation out of high-multiple AI infrastructure names and into more defensive sectors such as healthcare and financials, which have already been hitting fresh highs as investors seek shelter from the volatility surrounding AI capital spending.
With the Fed decision, a high-profile press conference, and two megacap earnings reports compressed into a single session, market participants describe Wednesday as a session where multiple binary outcomes could each independently move the broader index, making it one of the more difficult days of the year to position around with high conviction in either direction.