Chip stocks have lost more than $1 trillion in combined market capitalization over the past week, as a rally that carried semiconductor names to record highs earlier this year gives way to sharp profit-taking. Nvidia has borne the brunt of the decline, shedding roughly $238 billion in value since last Friday's close, while SK Hynix, Samsung Electronics, and Micron have each lost more than $100 billion.
The selloff began in Asia, where SK Hynix and Samsung led a steep drop on the Korean stock exchange, and has since spread into US trading hours, dragging down Micron, Intel, Advanced Micro Devices, and Taiwan Semiconductor Manufacturing Company. All six companies have now lost more than $100 billion apiece in market value, according to figures reported this week.
Analysts describe the pullback as a recalibration of expectations rather than a sign that artificial intelligence demand is fading. Forrester's Charlie Dai said the selloff reflects worries that AI infrastructure spending could be peaking faster than markets anticipated, adding that investors are reassessing whether near-term revenue can justify the scale of capital outlays companies have committed to. He characterized the move as a repricing after an unusually strong run rather than evidence that underlying AI demand is weakening.
Memory chipmakers have been especially volatile. SK Hynix's stock has tumbled more than 40% in July alone, on pace for its worst month since the 2008 financial crisis, after Korea Investment & Securities cut its earnings forecast for the company. Some independent researchers argue the market has misread the revision, framing what they see as a contract-timing issue around how quickly SK Hynix recognizes higher DRAM prices as evidence of a broader collapse in memory demand. The rise of Chinese memory producer CXMT, which recently completed a well-received debut on the Shanghai exchange, has added to investor anxiety about future pricing power in the DRAM market, even though the company's global market share remains well below that of Samsung, SK Hynix, and Micron combined.
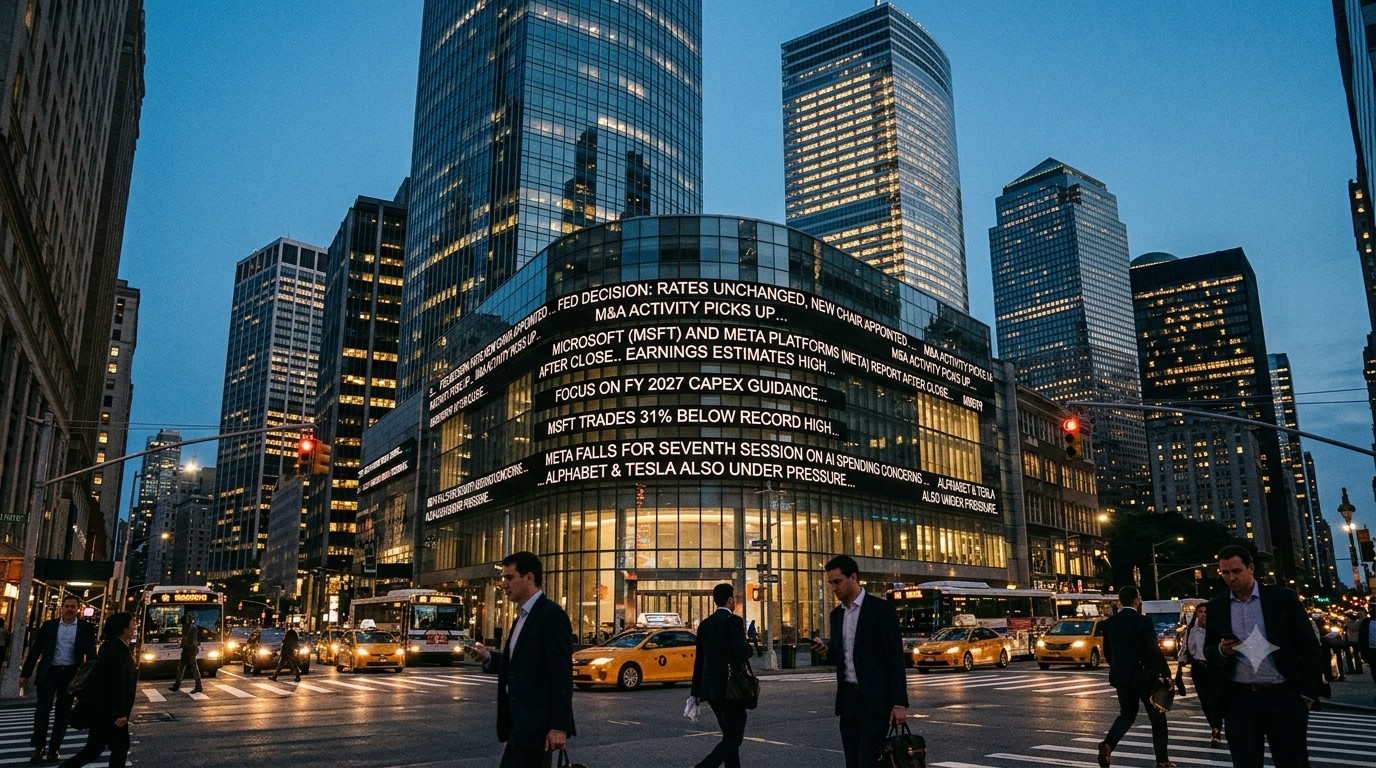
The timing amplifies the stakes. The selloff lands on the same day the Federal Reserve is set to announce its latest interest rate decision and hours before Microsoft and Meta Platforms report quarterly results after the closing bell. Both tech giants face intense scrutiny over their own artificial intelligence capital expenditure plans, and a disappointing capex outlook from either company could reinforce the narrative currently weighing on chipmakers. Conversely, reassuring guidance on AI monetization could help stabilize sentiment across the sector.
Options markets are pricing in significant moves for chip-linked names over the next several sessions, and traders are watching whether support levels established during recent sessions can hold as the week's earnings and monetary policy catalysts play out. The semiconductor sector remains one of the most crowded trades of 2026, and the scale of this week's decline underscores how quickly sentiment can shift even when underlying earnings, as in Samsung's case, have topped expectations.
For portfolio positioning, the divergence between reported fundamentals and share price action is the key signal to watch. Micron's most recent quarter delivered revenue growth exceeding 300% year-over-year with earnings well above consensus, yet the stock has still declined double digits since. That disconnect suggests the market has shifted from rewarding AI-linked growth unconditionally to demanding clearer evidence that spending translates into durable returns, a dynamic likely to define trading in chip stocks through the rest of earnings season.