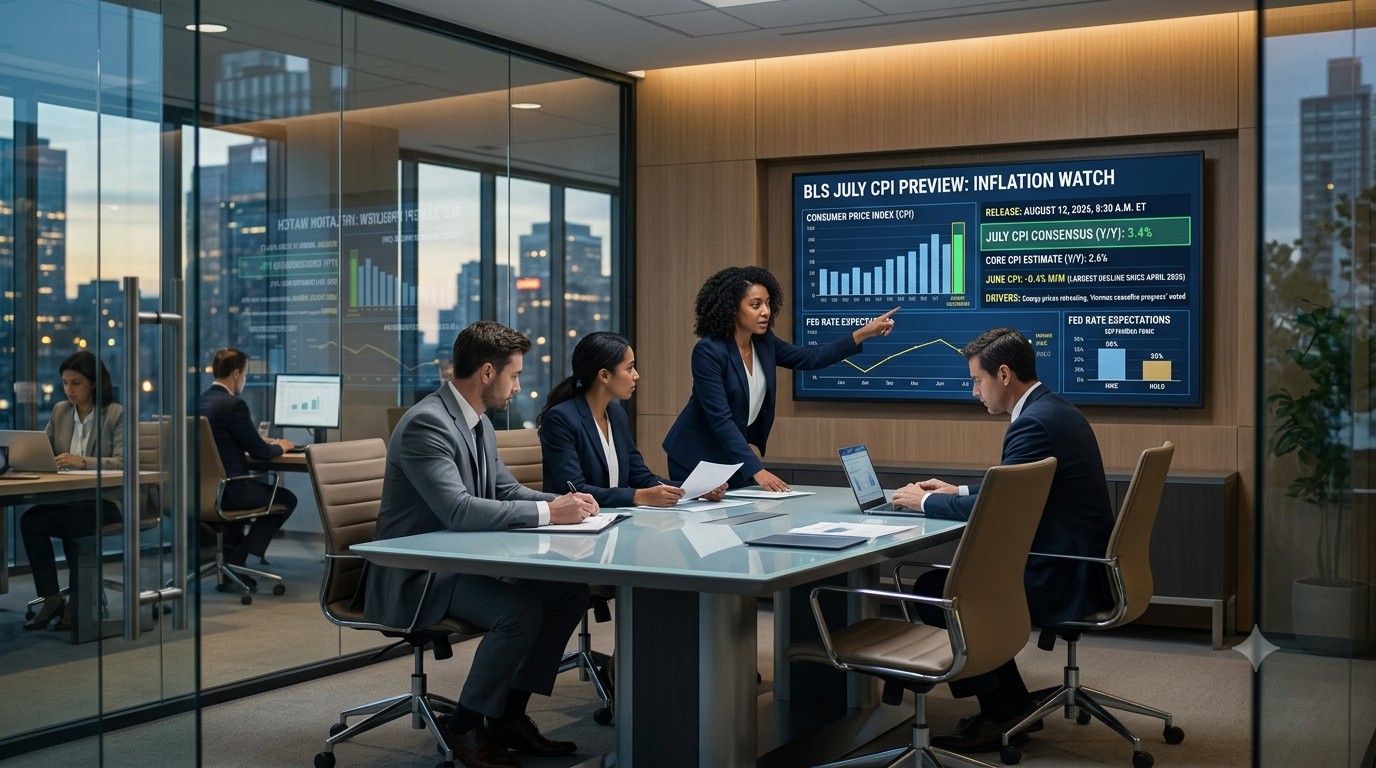
The most consequential macro event of the week arrives Wednesday morning: the Bureau of Labor Statistics publishes the Consumer Price Index for July 2026 at 8:30 a.m. ET, and the outcome will have direct implications for Federal Reserve policy, Treasury yields, the dollar, and equity valuations across every major sector. Consensus estimates compiled by FactSet and TradingKey anticipate a headline CPI increase of approximately 3.4% year-over-year, with month-over-month growth expected to be flat to modestly positive after June's dramatic disinflationary print.
June's CPI report set a high bar for the July reading: the June all-items index fell 0.4% on a seasonally adjusted month-over-month basis — the largest single-month decline since April 2020 — as energy prices retreated sharply following ceasefire progress on the Strait of Hormuz. Over the twelve months through June, the all-items index rose 3.5% before seasonal adjustment, with core CPI (excluding food and energy) rising 2.6% year-over-year and holding flat on a monthly basis. That combination — declining headline, stable core — was precisely the disinflationary configuration that Fed officials needed to feel comfortable maintaining their current policy stance without initiating rate hikes.
The July data will be shaped by two competing forces. On the deflationary side, energy prices — particularly gasoline — have continued to moderate as Hormuz diplomacy has advanced, with Brent settling in the mid-$80s versus its 2026 peak above $166. Goods inflation, which had been a tariff-driven upside risk, has also shown signs of stabilizing. On the inflationary side, services — particularly shelter, which moves slowly through the CPI basket — remain elevated, and food prices have not yet meaningfully reversed. Core CPI is broadly expected to print at 2.6% year-over-year, unchanged from June, with a monthly increase of approximately 0.2%.
The stakes for the September 16–17 FOMC meeting are high. Following July's nonfarm payrolls report — which showed an unexpected decline of 23,000 jobs and prompted a sharp rally in risk assets — futures markets have effectively priced out the probability of a September rate hike. A July CPI print that matches or undershoots consensus would cement that view, potentially opening the door to discussion of rate cuts before year-end. A surprise to the upside — particularly in core services or shelter — could reignite hike probability and produce a sharp, rapid repricing in yields, the dollar, and growth equities.
Later in the week, July PPI (Thursday, August 13) and retail sales (Friday, August 14) round out the inflation and demand picture. Applied Materials and Cerebras Systems both report earnings Wednesday evening after CPI, creating a scenario where the macro print at 8:30 a.m. sets the tone for the session and the tech earnings after the close add a second directional impulse. Investors deploying $100,000 today should consider that Wednesday represents the single most binary data point of the week — reducing exposure ahead of the print and sizing back into positions based on the actual outcome is a disciplined approach given the asymmetric reaction function of the current market.