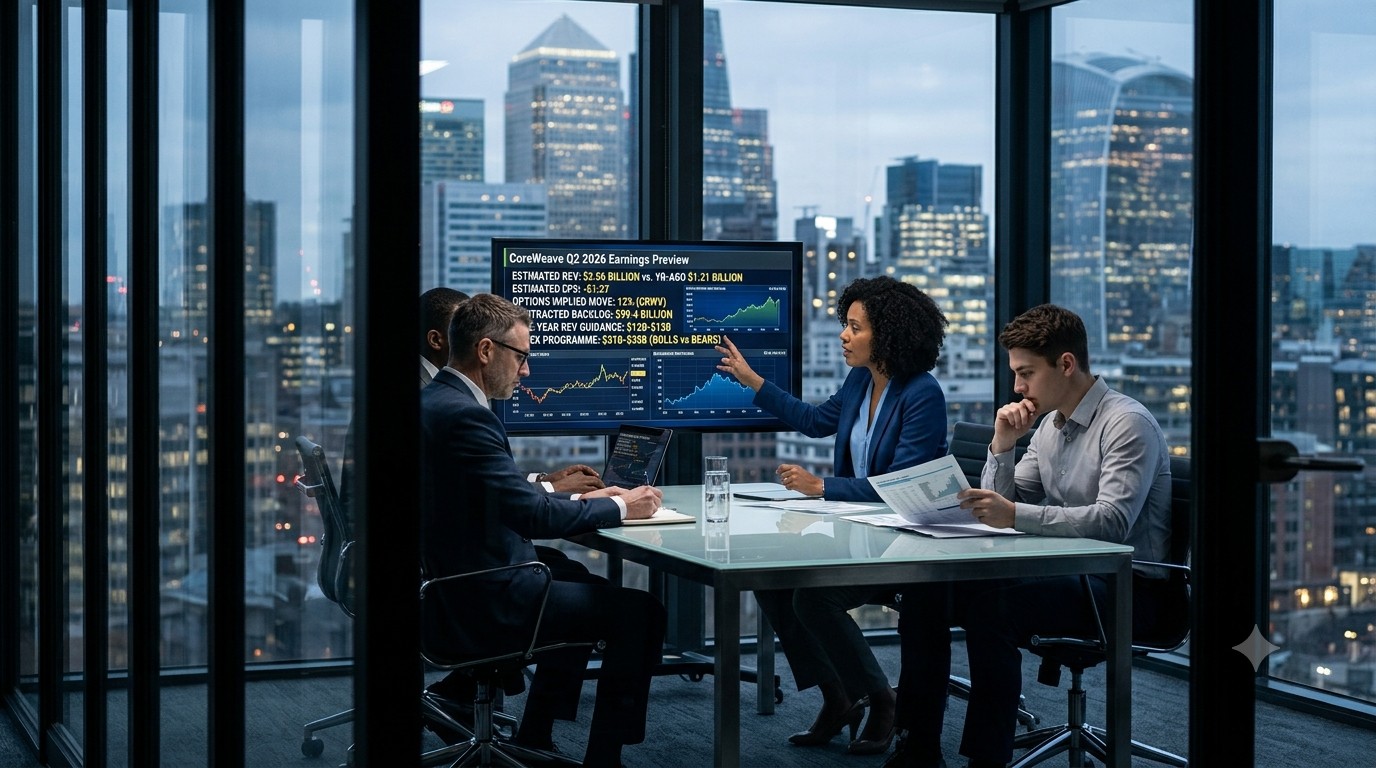
CoreWeave, the GPU-powered AI cloud infrastructure company that went public in March 2025, reports its second-quarter 2026 results tonight after the close of regular trading, with a conference call scheduled for 5:00 p.m. ET. The report is one of the most closely watched AI infrastructure prints of the August earnings season, functioning as a real-time read on whether demand for high-performance GPU compute continues to compound at the extraordinary pace implied by the company's $99.4 billion contracted backlog.
Analyst consensus compiled by Benzinga expects Q2 revenue of approximately $2.56 billion — more than double the $1.21 billion reported in the second quarter of 2025 — with a loss per share of approximately $1.27, compared to a loss of $0.27 per share a year earlier. The widening loss reflects a capital expenditure programme that management most recently guided to $31 billion to $35 billion for the full year of 2026, a figure that has been the primary fault line between bulls who view the spending as a durable infrastructure moat and bears who see it as a structural drag on the path to free-cash-flow generation.
In the most recent quarter CoreWeave reported — its first quarter of 2026 — the company delivered revenue of $1.37 billion and maintained its full-year 2026 revenue forecast of $12 billion to $13 billion while raising its exit 2026 annualized run-rate revenue target to $18 billion to $19 billion. Adjusted operating income guidance of $900 million to $1.1 billion for the full year was also reaffirmed, providing a glimmer of near-term profitability against a backdrop of aggressive spending.
Options markets are pricing a 12% implied move in either direction for CRWV, according to data compiled by Bloomberg. The historical context is instructive: CoreWeave has exceeded its implied move in three of its last five earnings announcements. The largest prior swing was a 33.9% decline in November 2025, followed by a 21.1% gain in May 2025 and a 16.6% drop in February 2026. The stock traded near $85 heading into Monday's session, well below its 52-week high of $153.20 but up 19% year-to-date.
Piper Sandler recently named CoreWeave its top AI infrastructure pick with an Overweight rating and a $151 price target. The firm's conviction rests on CoreWeave's role as a dedicated GPU cloud provider to the most demanding AI labs and enterprises — a positioning that differentiates it from the general-purpose hyperscalers. Microsoft and NVIDIA are among CoreWeave's largest customers and investors. The key watch items for tonight's call include: the trajectory of backlog growth from the current $99.4 billion base; any commentary on gross margin improvement as revenue scales against fixed infrastructure; updates on capacity expansion timing; and management's response to the competitive positioning of Amazon, Microsoft, and Google in dedicated AI compute — all of whom have accelerated their own GPU cloud build-outs in 2026.
For investors allocating $100,000 today, a CoreWeave earnings beat with a raised backlog figure would validate the long-duration AI infrastructure thesis that JPMorgan's Monday target upgrade is also premised upon. The options-implied 12% move in either direction makes this a high-risk, high-reward event — suitable for a smaller position size with predefined risk parameters rather than a full allocation ahead of the print.