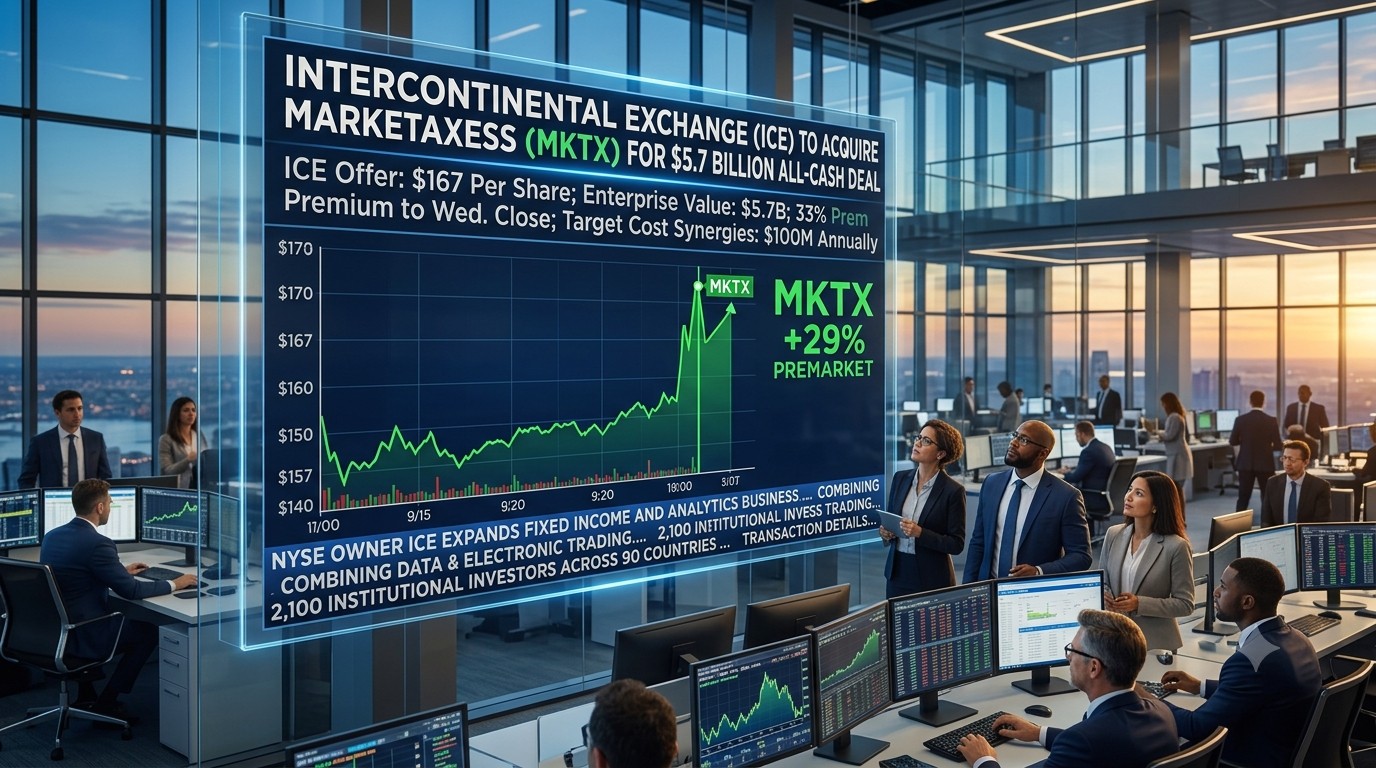
Intercontinental Exchange announced Thursday morning it has entered into a definitive agreement to acquire MarketAxess Holdings in an all-cash transaction valued at approximately $5.7 billion in total enterprise value — $6.0 billion on an equity basis — paying $167 per share, a 33% premium to MarketAxess's closing price of $125.73 on July 29. The deal has been unanimously approved by the boards of both companies and is expected to close in the first half of 2027, subject to shareholder approval and customary regulatory clearance.
MarketAxess shares surged approximately 29% in premarket trading Thursday, trading near $163 against the $167 cash offer — a narrow spread that implies the arbitrage community sees high deal certainty. ICE shares edged up approximately 1.7% before the bell, a sign that investors view the acquisition as strategically value-creating rather than dilutive, particularly given ICE's track record of integrating fixed income businesses following its 2021 acquisition of Ellie Mae and long-standing data and analytics buildout. ICE also reported Q2 2026 net income of $958 million, or $1.69 per share, up from $851 million in the year-earlier period, indicating the underlying business is in strong shape to absorb the new leverage.
The strategic rationale centers on a fundamental inefficiency in the global bond market. ICE CEO Jeff Sprecher framed the opportunity bluntly in the announcement: the $145.1 trillion global fixed income market remains disproportionately manual, bilateral, and information-asymmetric relative to equities — a structural gap that has persisted despite decades of incremental electronic trading adoption. MarketAxess's platform connects approximately 2,100 institutional investors and broker-dealers across more than 90 countries, enabling electronic trading in corporate bonds, municipal bonds, emerging market debt, Eurobonds, U.S. Treasuries, and other fixed income instruments. ICE contributes a comprehensive fixed income data and analytics platform, a leading retail bond marketplace, and a global index business. Together, the companies aim to build what Sprecher described as "the fixed income ecosystem that investors have always deserved — one that is transparent, efficient, fully connected, and accessible to all."
ICE targets $100 million in annual run-rate cost synergies, financed through a combination of bonds, a term loan, and commercial paper. The transaction is priced at approximately 10.6x MarketAxess's last twelve months EBITDA pro forma for full run-rate synergies — a multiple that reflects a high-quality, cash-generative business with defensible market share but also one that has lost approximately 31% of its market value in 2026 as higher interest rates have reduced fixed income trading volumes and compressed the valuation multiple. ICE's CFO Warren Gardiner specifically described the target as "a high-quality, cash-generative business" — language that signals confidence in the pro forma financial profile after synergy realization.
ICE is increasing its minimum quarterly share repurchases to $400 million from $350 million concurrent with the announcement — a signal that management is confident the deal's leverage, targeted at a beginning gross ratio of 3.4x with a goal to return to 3.0x within 18 to 24 months post-close, will not constrain capital return capacity. The transaction adds to a broader wave of exchange-group consolidation in the fixed income electronification space, which has accelerated as rising rates and bond market volatility have drawn institutional investor attention back to credit products after years of equity dominance. Competitors including CME Group, Tradeweb, and Bloomberg's trading infrastructure will be watching the regulatory review closely for its implications for the competitive landscape in electronic bond trading.