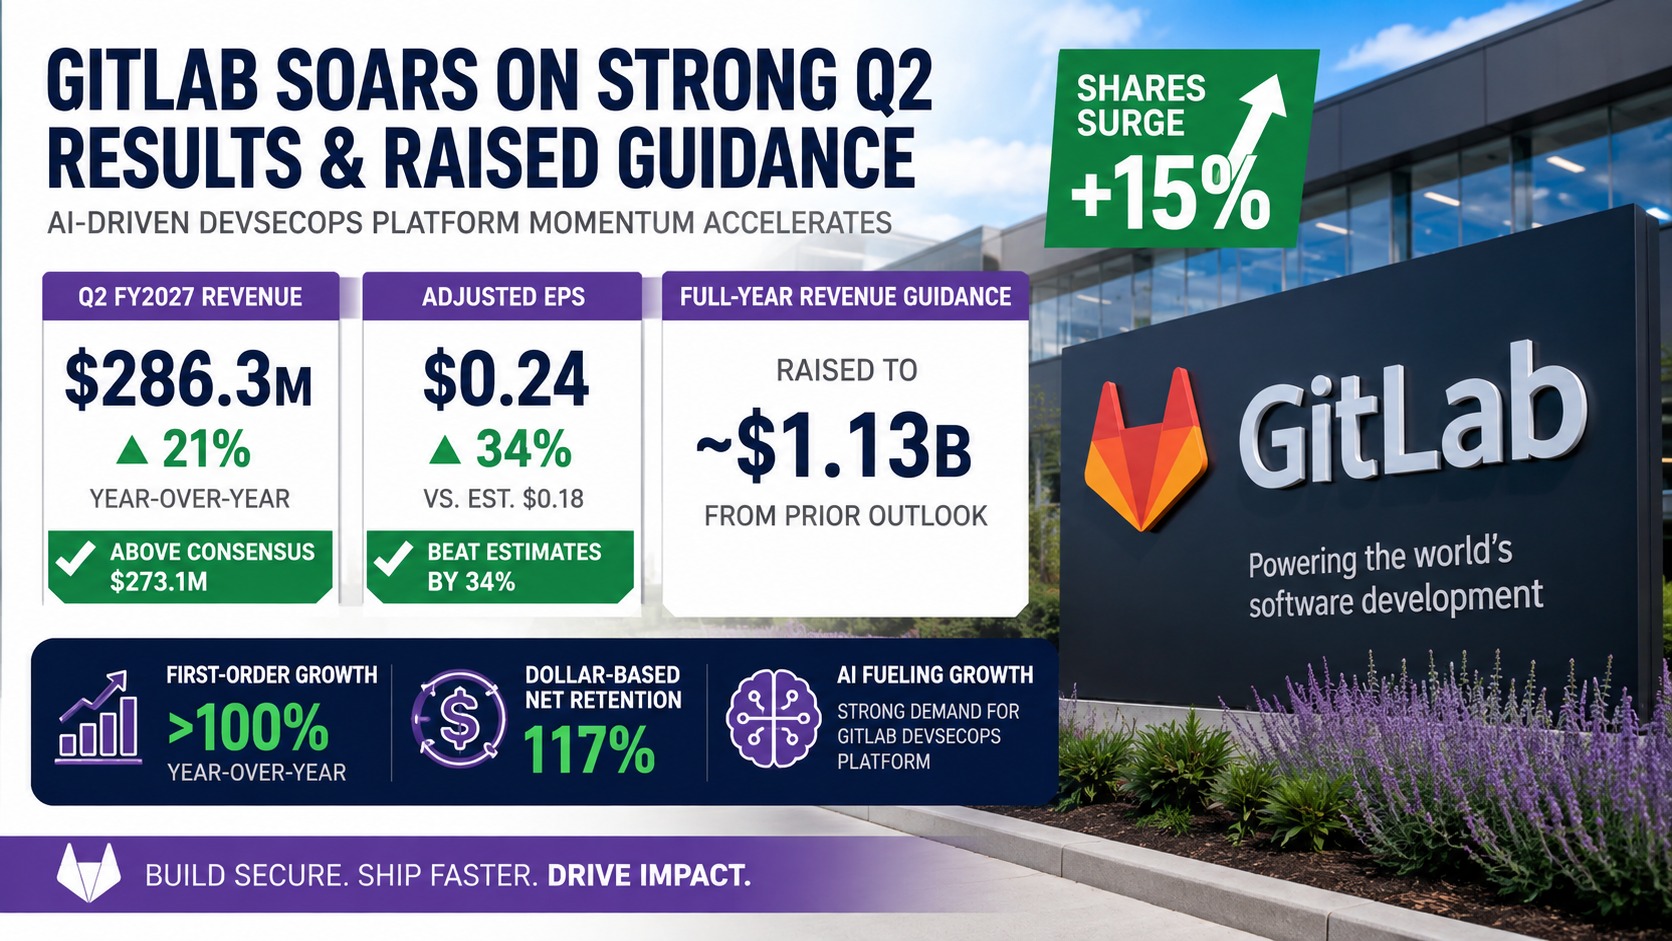
GitLab shares surged more than 15% on Wednesday, extending gains that began in premarket trading after the DevSecOps software company posted fiscal second-quarter 2027 results that comfortably beat Wall Street expectations across nearly every metric. Revenue for the quarter ended July 31 reached $286.3 million, up 21% from $236.0 million a year earlier and ahead of the $273.1 million analysts had forecast.
Adjusted earnings per diluted share came in at 24 cents, beating the 18-cent consensus estimate by nearly 34% and matching the year-ago figure even as the company scaled its business. Adjusted operating income rose to $42.6 million from $39.6 million a year earlier, a margin the company said reflected disciplined spending even while investing heavily in artificial intelligence features.
Beyond the headline revenue and profit beats, GitLab highlighted several growth metrics that pointed to accelerating momentum. First-order growth, a measure of new customer wins, more than doubled year-over-year. Customers generating more than $5,000 in annual recurring revenue climbed to 11,114, up 8% from a year earlier, while customers spending more than $100,000 annually rose 17% to 1,571. The company's dollar-based net retention rate, which tracks spending growth among existing customers, held at 117%. Total remaining performance obligations grew 16% year-over-year to $1.2 billion, and current remaining performance obligations rose 20% to $744.7 million.
Executives framed the results as evidence that GitLab's platform is becoming more valuable as software development increasingly involves both human engineers and AI coding agents working side by side. The company's leadership argued that the context, security, and governance controls GitLab provides are becoming more important, not less, as more code gets generated with AI assistance, positioning the platform as complementary to rather than threatened by AI coding tools.
Looking ahead, GitLab raised its full-year revenue guidance to a range of $1.129 billion to $1.133 billion, up from a prior midpoint near $1.12 billion. The company also guided to adjusted operating income of roughly $150 million and earnings per share of 86 cents at the midpoint for the fiscal year, while projecting next-quarter revenue near $282 million, broadly in line with existing analyst estimates.
The stock's reaction pushed GitLab shares back toward their 52-week high, though some technical analysts flagged early signs of short-term momentum fatigue even as the underlying daily trend remained bullish, with key moving averages stacked in a constructive alignment. Investors weighing the stock following the report will likely focus on whether GitLab can sustain the pace of new customer additions and large-account expansion seen this quarter, particularly given persistent concerns among some analysts that AI-native coding tools from well-funded rivals could eventually erode demand for traditional DevSecOps platforms.
Wall Street's response also reflects a broader reassessment of software companies positioned at the intersection of AI adoption and enterprise governance. GitLab's expanded partnership with major cloud providers has been cited by analysts as a structural tailwind, even as the average sell-side price target has remained comparatively conservative relative to the stock's recent run. Some analysts continue to rate the shares a hold, citing valuation and competitive risk from larger platform providers, while others argue the quarter's bookings strength justifies a more constructive stance heading into the back half of the fiscal year.