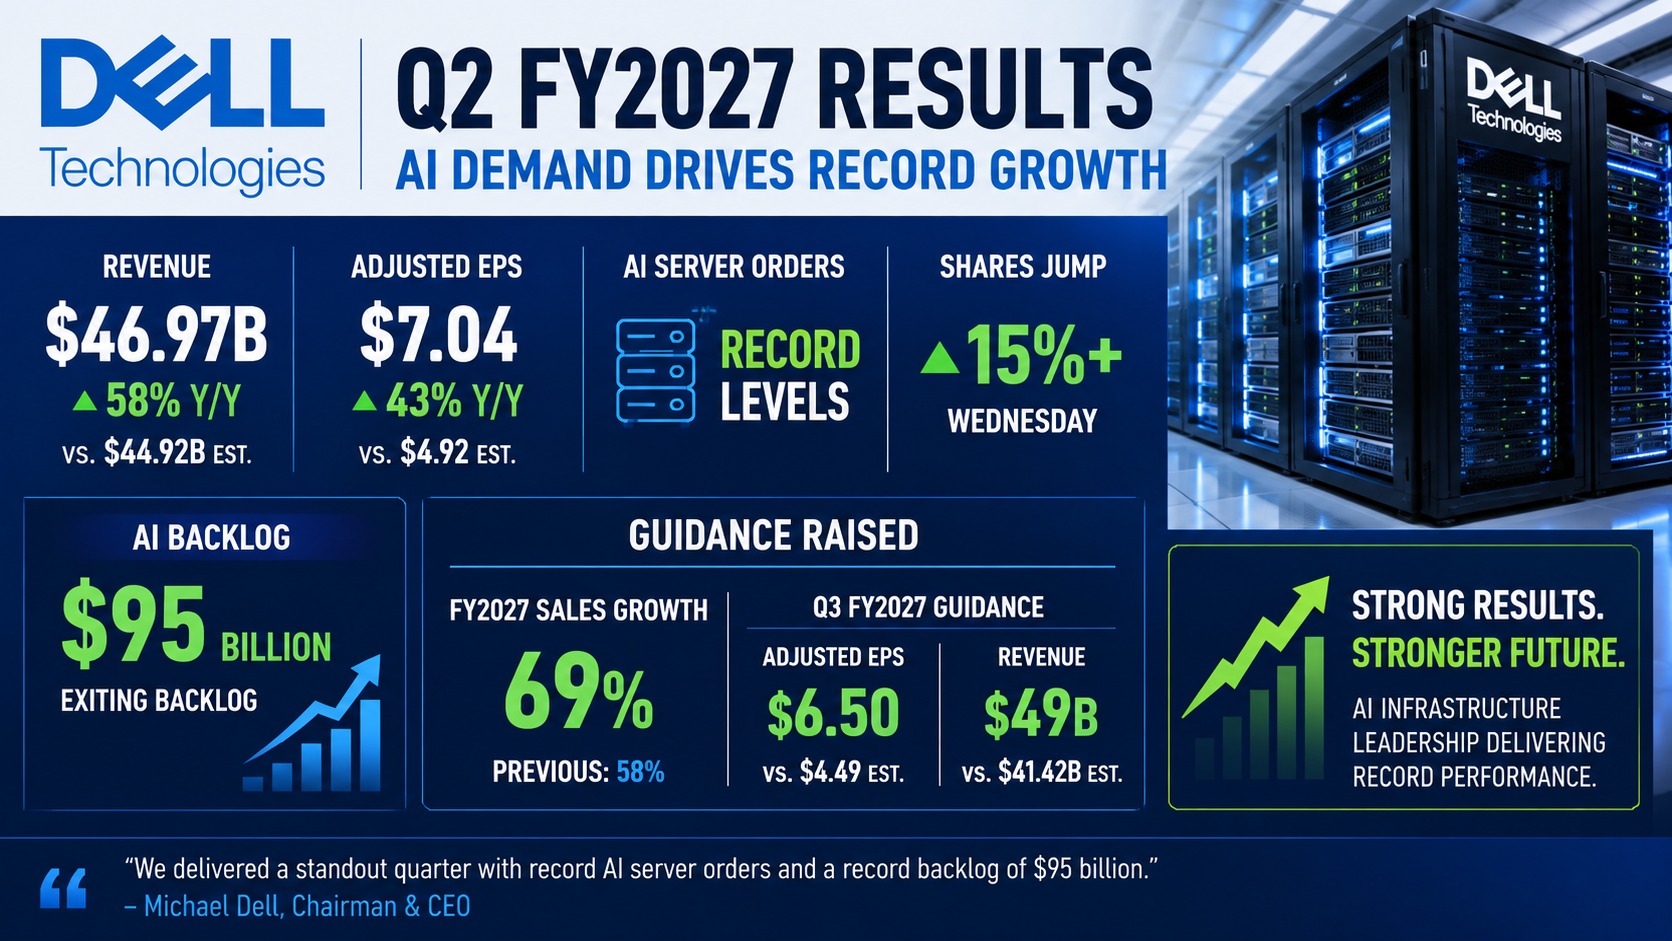
Dell Technologies delivered one of the most emphatic earnings beats of the current reporting season, with fiscal second-quarter 2027 revenue climbing to $46.97 billion, an increase of roughly 58% from a year earlier and comfortably ahead of the $44.92 billion analysts had penciled in. The results, released after Tuesday's closing bell, sent shares surging more than 15% in the following session as investors cheered the company's deepening exposure to artificial intelligence infrastructure spending.
Adjusted earnings per share came in at $7.04, more than 40% above the consensus estimate of $4.92 and nearly triple the $2.32 Dell reported in the same period a year earlier. Net income reached $4.13 billion, or $6.34 per share on a GAAP basis, up sharply from $1.16 billion, or $1.70 per share, in the prior-year quarter. The gap between adjusted and GAAP figures reflects the exclusion of stock-based compensation expenses.
The standout figure in Wednesday's report was Dell's AI-related order book. The company said it exited the quarter with a backlog of $95 billion tied to AI server demand, alongside record quarterly orders of $60.9 billion in that category. Revenue from traditional servers and networking equipment jumped 122% year-over-year to $10.53 billion, while storage revenue rose nearly 26% to $4.85 billion. Executives pointed to a growing need among customers for both AI accelerators and conventional CPU compute capacity to support increasingly automated, agentic workloads.
Dell's Client Solutions Group, which covers personal computers and related accessories for consumers and businesses, contributed $15.03 billion in revenue, up 20% from a year earlier. Management noted earlier this year that it had observed early signs of softening demand in the PC market during the back half of the year, a dynamic it continues to monitor even as the infrastructure side of the business accelerates.
Looking ahead, Dell raised its full-year guidance meaningfully, now projecting sales growth of 69% and adjusted earnings per share growth of 148% to $25.50 for the fiscal year. For the fiscal third quarter specifically, the company guided to adjusted earnings of $6.50 per share on revenue of $49 billion, implying roughly 81% year-over-year growth and well above the $4.49 per share and $41.42 billion analysts had modeled. The magnitude of the guidance raise underscores management's confidence that AI infrastructure demand has staying power beyond the current fiscal year.
The reaction in the options market ahead of the report had signaled investors were bracing for a large move. Contracts tied to the report had implied a swing of roughly 11.4% in either direction, and the actual result landed toward the upper end of that range. Dell shares have now climbed roughly 266% so far in 2026, a run that has made the stock one of the most closely watched proxies for enterprise AI capital spending alongside chipmakers and hyperscale cloud providers.
At current levels, Dell trades at approximately 19 times forward earnings, a multiple some analysts consider reasonable given the scale of the AI backlog and the durability of the company's server, networking, and PC franchises. Still, with expectations now elevated after back-to-back quarters of outsized guidance raises, some strategists caution that Dell will need to keep converting backlog into recognized revenue at a similarly rapid clip to sustain the stock's premium valuation. For portfolio managers evaluating exposure to the AI infrastructure buildout, Wednesday's report reinforces Dell's position as a direct beneficiary of enterprise and cloud spending on AI-capable servers, even as questions persist about how long the current investment cycle can run.