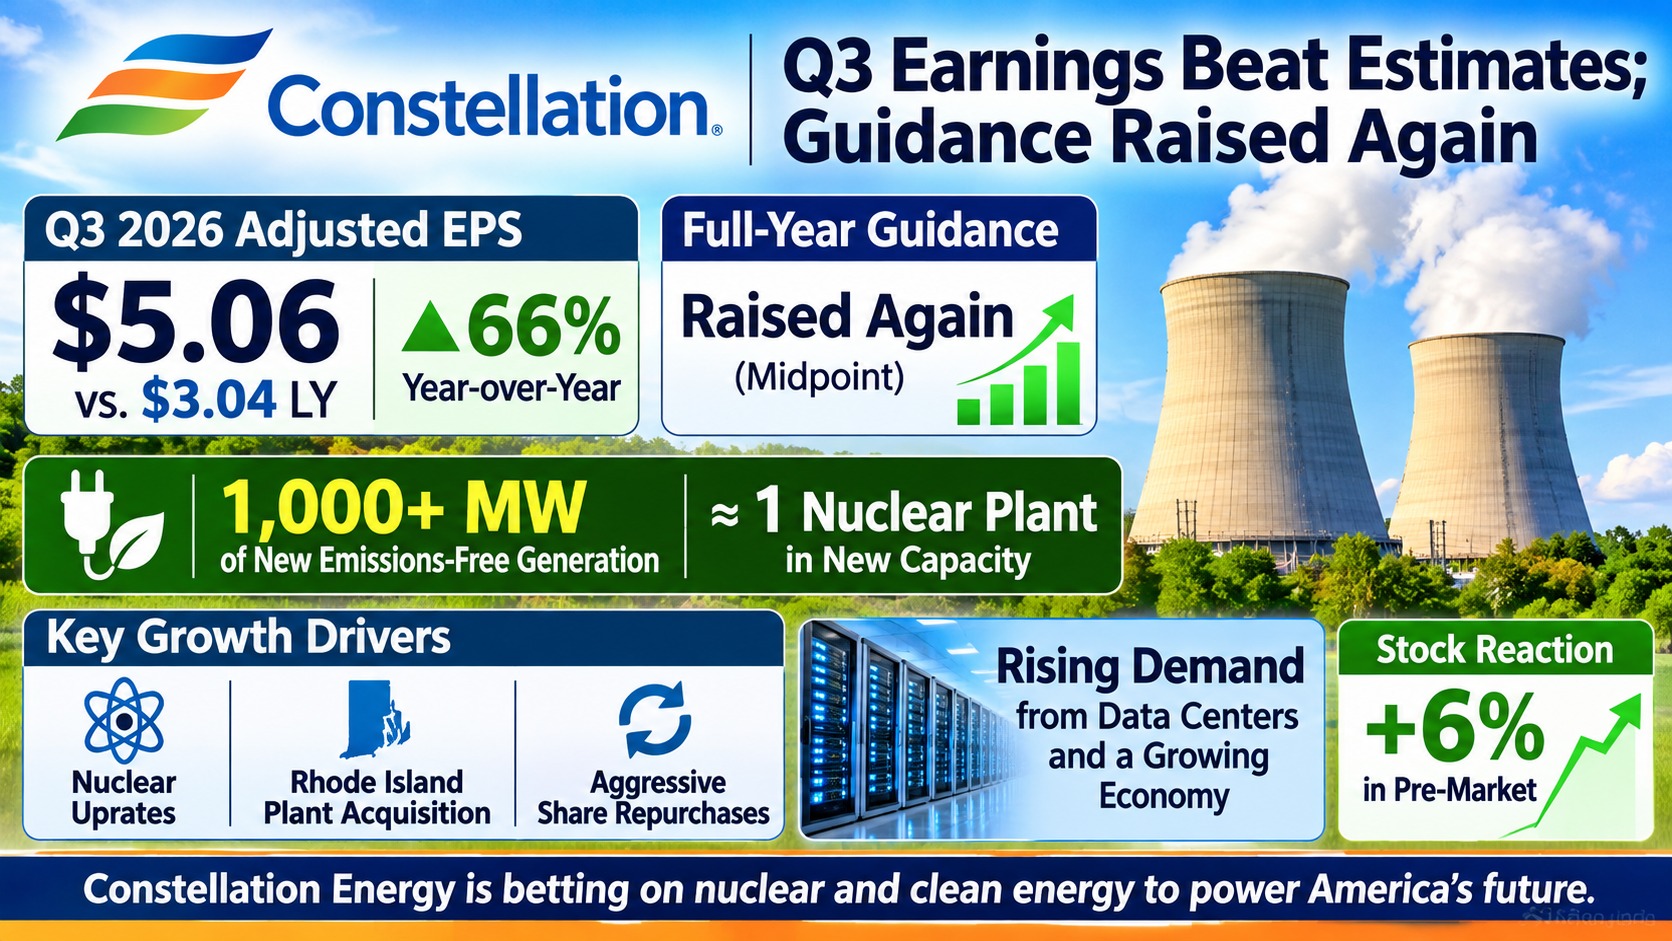
Constellation Energy Corporation reported third-quarter 2026 adjusted operating earnings of $5.06 per share on Monday, compared with $3.04 a year earlier, and raised the midpoint of its full-year adjusted earnings guidance range for the second time this year, according to its filing with the Securities and Exchange Commission. The result represents growth of about 66% from the year-ago quarter.
The Baltimore-based company, which describes itself as the nation’s largest producer of carbon-free electricity, operates a fleet of nuclear, hydroelectric, wind and solar plants. Management held its earnings call at 9:00 a.m. Eastern on Monday, with the results landing the same morning as a handful of other closely watched earnings reports.
Chairman, President and Chief Executive Officer Joe Dominguez said agreements announced during the quarter add more than 1,000 megawatts of new emissions-free generation to the grid, the equivalent of a new large-scale nuclear plant. He said the new capacity comes with no costs borne by existing customers, a point that matters politically as electricity bills draw scrutiny. Dominguez also pointed to Peak+, an integrated offering that combines new capacity, including new generation and demand response, with energy products designed to help large customers meet their evolving needs.
Chief Financial Officer Shane Smith attributed the quarter’s performance to strong execution and said the company’s capital allocation approach positions it for sustained earnings growth. He cited accretive organic growth through nuclear uprates, the acquisition of the Rhode Island State Energy Center and what he called an aggressive pace of share repurchases as the main building blocks.
Investors had been watching whether Constellation could meet its earlier full-year target of $11.50 to $12.50 per share. That range was set after second-quarter adjusted earnings rose 33.5% to $2.55 per share, partly because of the Calpine acquisition. Monday’s print, along with a second guidance raise, adds to the case that demand for firm, around-the-clock power is translating into earnings rather than just narrative.
The update arrives in a week when AI-linked equities are under heavy pressure. Power producers and nuclear operators have benefited from the data center buildout story, and last week’s selloff was partly triggered by worries that Democrats, who won control of Congress in the November 3 midterm elections, could target power permitting and data center construction. For Constellation, whose pitch rests on supplying reliable clean power to digital infrastructure, policy direction matters as much as quarterly numbers.
Risks remain. The stock has been volatile and sensitive to artificial intelligence sentiment; at the end of July it was trading near $263, down roughly 26% for the year. Power prices, regulatory decisions, plant outages and the pace of data center demand all influence results, and a sustained AI spending pullback could weigh on the multiples investors are willing to pay for nuclear exposure.
For investors, the report offers a rare fundamental positive in a tape dominated by macro and technology headlines. With October CPI due Tuesday and December Fed rate-hike odds above 75%, utilities and power producers with visible earnings growth and raised guidance may attract defensive interest. Position sizing remains important while volatility is elevated, and traders will watch whether Constellation’s earnings momentum can hold up against policy headlines out of Washington.