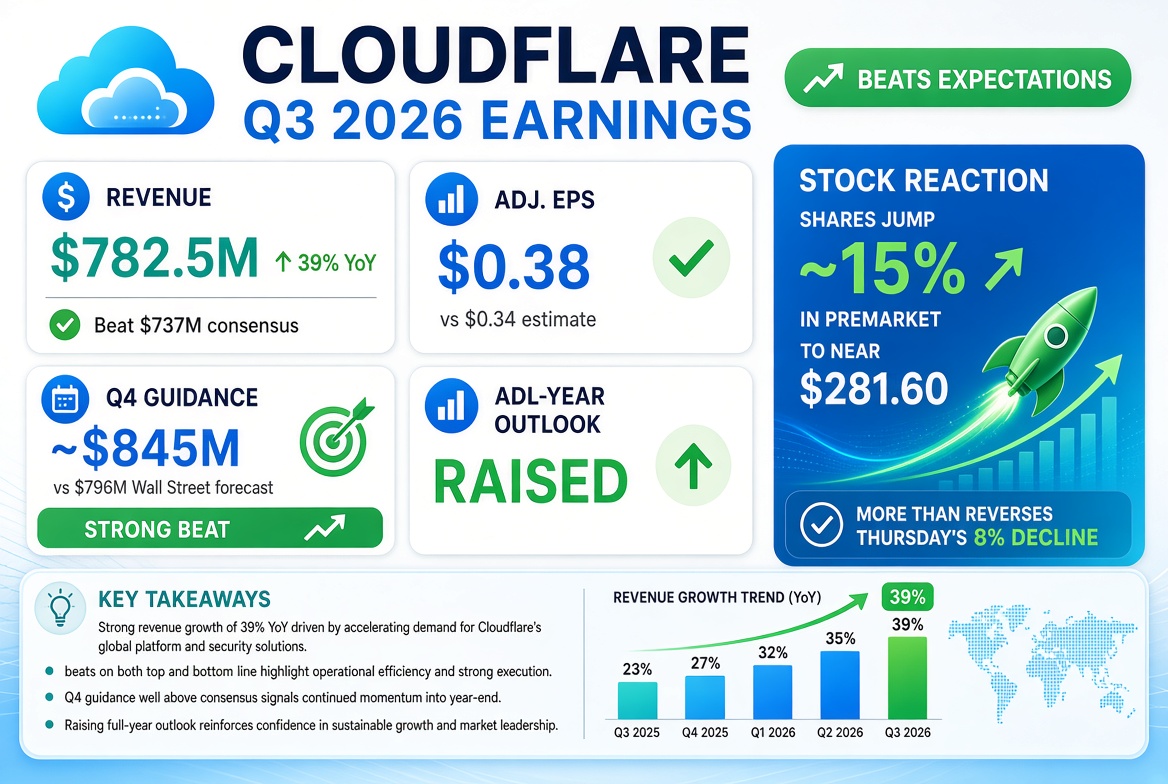
Cloudflare reported third-quarter 2026 revenue of $782.5 million, up 39% from a year earlier and well above the roughly $737 million analysts had projected, and its shares jumped about 15% in premarket trading on Friday to near $281.60. The stock closed Thursday at $244.51 after falling about 8% in a broad technology selloff, so the earnings reaction more than reverses that decline.
Adjusted earnings were $0.38 per share versus the $0.34 consensus. Revenue growth accelerated from 36% in the second quarter, when sales were $696.1 million, and Chief Executive Matthew Prince called the period the company's best quarter ever. Non-GAAP net income reached $143.7 million, while non-GAAP operating income rose to $137.1 million, a 17.5% margin compared with 15.3% a year earlier. The results arrived after Thursday's close, extending a run of upside surprises for the internet infrastructure and cybersecurity company.
Guidance was the standout. Cloudflare expects fourth-quarter revenue of about $845 million to $846 million, compared with the $796 million Wall Street had forecast, and it raised its fiscal 2026 revenue outlook. One market newsletter noted it was the third time this year the company lifted its profit forecast, citing demand from firms running AI workloads that depend on its network.
Not every metric improved. Cloudflare posted a GAAP net loss of $34.1 million, or $0.10 per share, compared with a $1.3 million loss a year earlier, and GAAP gross margin slipped to 71.2% from 74%. Investors will want to understand whether the margin decline reflects temporary infrastructure investment for AI traffic or a more durable shift in the cost of serving customers.
Analysts were already constructive. Goldman Sachs kept its Buy rating and a $420 price target and said the company's outlook sits about 6% above Street revenue estimates, with earnings per share projected 13% above consensus. J.P. Morgan had upgraded the stock after a recent pullback, giving the shares support heading into the report.
The move also carries a message for the AI trade. While chip and data center names were sold heavily on Thursday over concerns that political opposition could slow construction, Cloudflare's results indicate that orders from companies deploying AI applications are still arriving at the firms that carry internet traffic and provide security. That demand pattern is less dependent on new data center permits than hyperscale capacity buildouts.
For traders, the key question is whether the premarket gain survives the open and the payrolls report at 8:30 a.m. ET. A rebound of this size leaves the shares well above Thursday's close, and any fade in the broader Nasdaq could pressure high-multiple software and infrastructure names. Position sizing matters in a session where index futures are mixed and volatility remains elevated after the worst day for U.S. stocks since April 2025.
Looking ahead, investors will focus on whether Cloudflare can sustain growth near 39% while protecting margins, how much of the demand is tied to AI inference and agent traffic, and how large enterprise deals convert into revenue in 2027.