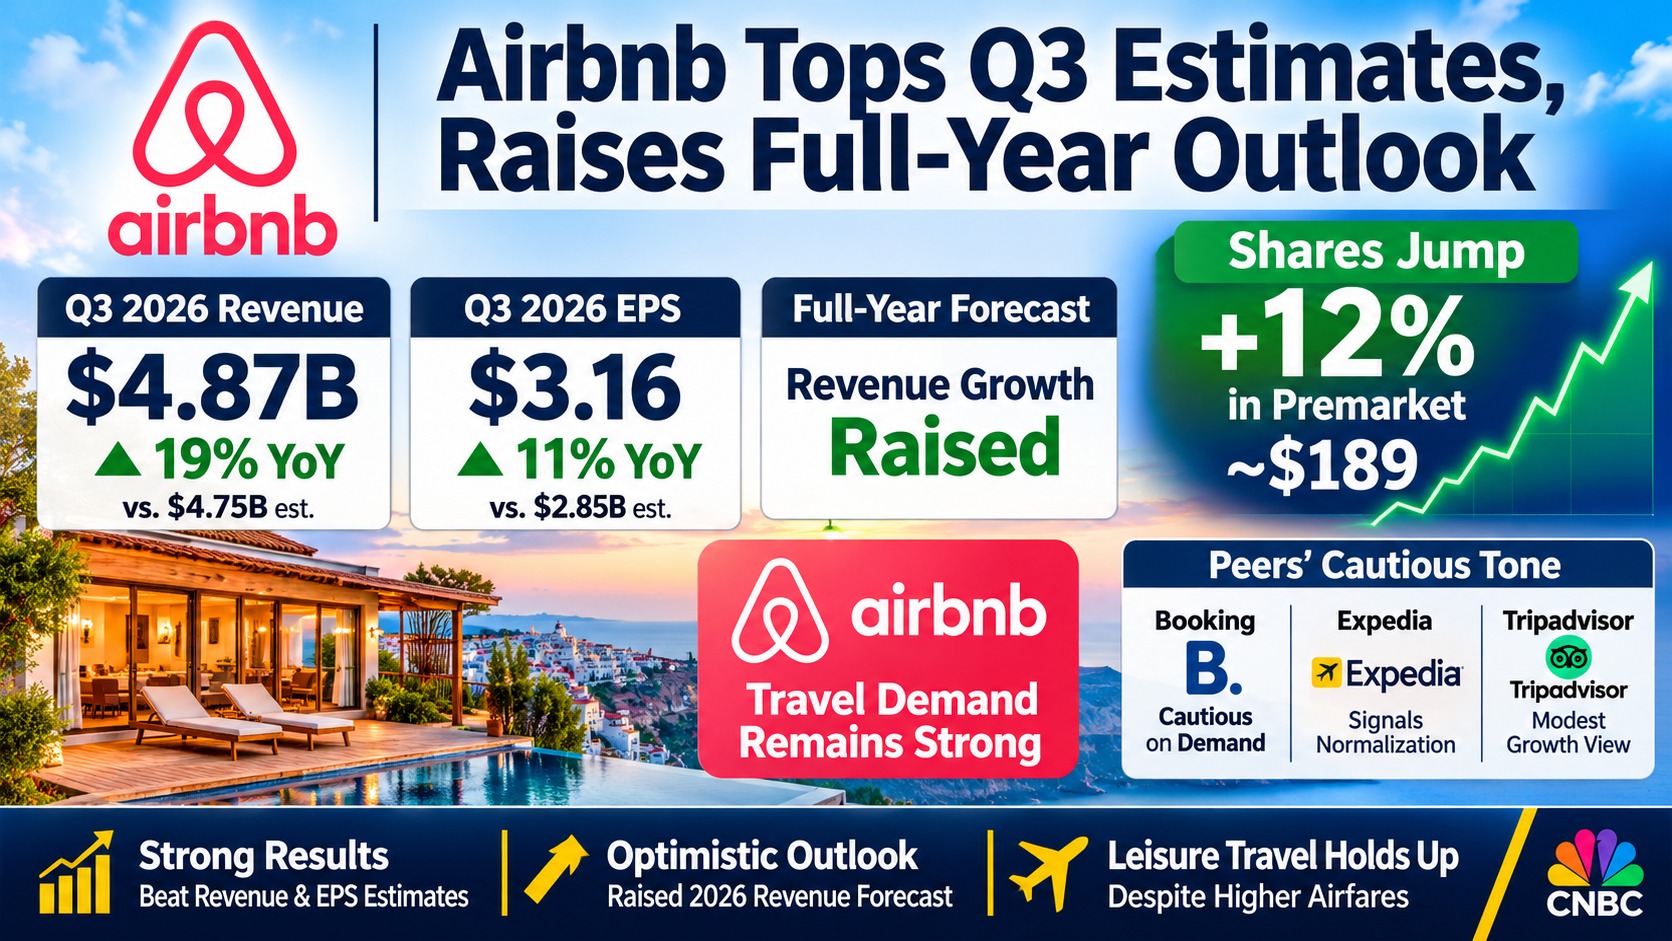
Airbnb reported third-quarter 2026 revenue of $4.87 billion, up 19% from a year earlier and ahead of the $4.75 billion analysts expected, and raised its full-year revenue growth forecast. Diluted earnings came in at $3.16 per share versus the $2.85 consensus. Shares jumped roughly 11% to 12% in premarket trading on Friday, near $189, after the results were released following Thursday's close.
The quarter marked the home-sharing platform's fastest revenue growth in three years, according to market commentary, and arrived while many investors were selling nearly everything tied to growth. Management said demand accelerated across regions and in newer markets, with Chief Executive Brian Chesky telling analysts on the post-earnings call that the company is back in growth mode.
The upbeat outlook contrasts with recent commentary from other online travel agencies. Booking Holdings, Expedia Group and TripAdvisor have pointed to headwinds from higher airfares linked to the Iran war and unrest in parts of Europe, according to wire reports. Airbnb's results suggest leisure travel demand remains resilient even as fuel costs and geopolitical risk weigh on airlines and rival booking platforms.
Valuation is the main debate. Airbnb trades at a 12-month forward price-to-earnings ratio of about 31.9, compared with roughly 18.3 for Booking and 16.0 for Expedia, according to market data cited in wire reports. Investors are also tracking Airbnb's push to look more like a conventional online travel agency, which sets up greater competition with those established peers as the company expands services beyond short-term rentals.
Context on the quarter: Airbnb's second-quarter revenue was $3.61 billion with gross booking value of $27.2 billion, up 16%, and the company then guided third-quarter revenue to $4.69 billion to $4.77 billion. Delivering $4.87 billion therefore cleared the top of that range by roughly $100 million, a sign that momentum built through the summer travel season rather than fading.
Key numbers: premarket price near $189.50 versus a Thursday close of roughly $170; earnings per share beat by about $0.31, or 11%; and revenue exceeded consensus by about $120 million.
The gap-up comes against a hostile tape. The Nasdaq Composite fell 5.52% on Thursday, and U.S. futures were mixed Friday ahead of the October jobs report. Airbnb is a consumer-discretionary name that has often been treated like a technology stock, so it can swing with AI-led sentiment, but this quarter's results give bulls company-specific support independent of the data center debate. Because the report arrived after Thursday's close, the full reaction will play out in regular trading, when liquidity improves and index-driven flows resume.
What happens next: Whether the gap holds will depend on the details of the raised full-year outlook, commentary on bookings and how the broader market trades after payrolls. Analysts are likely to lift price targets, though the premium valuation leaves less room for error than at cheaper rivals. Traders will also watch whether the stock holds above the $180 area after the open, since a fade would suggest the broader selloff is overwhelming the earnings reaction.