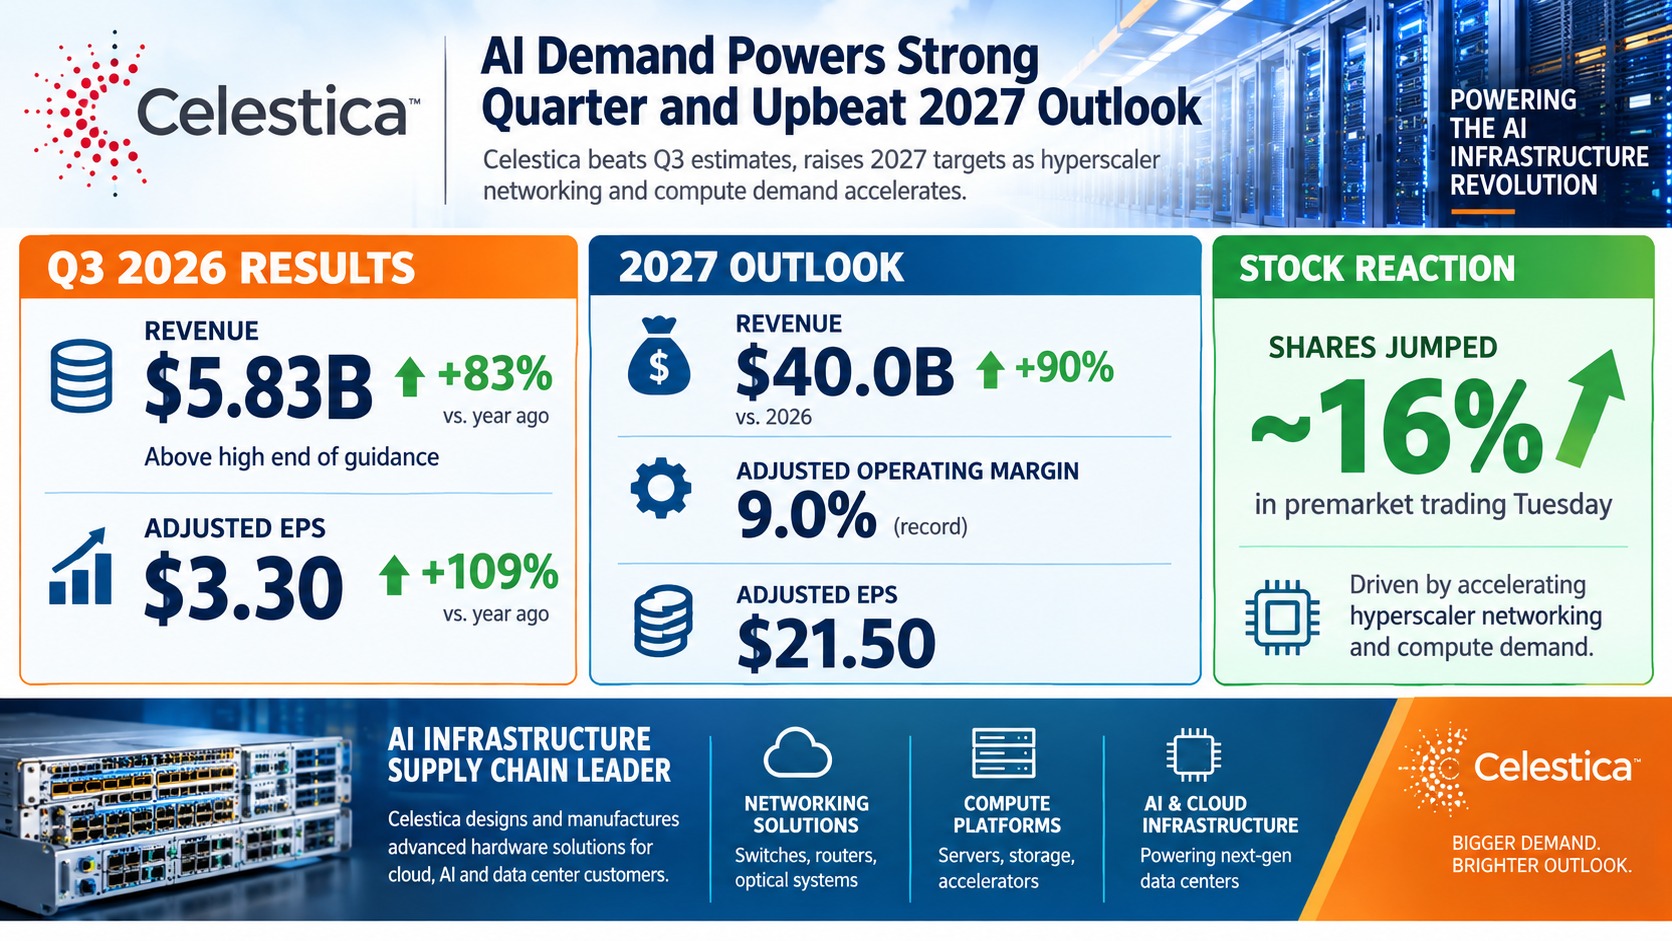
Celestica delivered a blowout third quarter and a bullish first look at 2027, sending its shares sharply higher in premarket trading on Tuesday. The electronics manufacturing and data center infrastructure company reported revenue of $5.83 billion for the quarter ended September 30, 2026, an 83% increase from $3.19 billion a year earlier. Adjusted earnings per share of $3.30 were up 109%, and both measures exceeded the high end of company guidance.
Revenue topped the $5.25 billion to $5.55 billion range management provided in July, and adjusted EPS cleared the $2.88 to $3.08 range. Management attributed the outperformance to higher-than-anticipated customer demand and strong operational execution, with operating leverage pushing the adjusted operating margin above the midpoint of guidance. GAAP earnings from operations were 7.9% of revenue.
Sequentially, revenue rose $1.13 billion, or 24%, from the second quarter. The CCS segment, which houses data center networking and compute, increased $1.06 billion, or 28%, led by a $610 million, or 23%, rise in networking revenue from hyperscaler switch programs and a $452 million, or 39%, jump in compute and storage as AI compute volumes grew. The Advanced Technology Solutions segment grew 8%, helped by acceleration in its capital equipment business.
The headline for investors was the initial 2027 outlook: revenue of $40.0 billion, up 90%, a record adjusted operating margin of 9.0% and adjusted EPS of $21.50. The 90% growth rate implies 2026 revenue of roughly $21 billion. CEO Rob Mionis said the demand environment continues to strengthen and that customer demand forecasts for 2028 are meaningfully higher. The company also raised its 2026 annual outlook, which in July stood at $20.5 billion of revenue and $11.30 of adjusted EPS, and said it will hold an investor and analyst day.
Shares rose about 16% in premarket trading Tuesday, according to market reports, making the stock among the most notable gainers before the opening bell. The reaction is striking in a month when investors have rotated away from chip stocks, and it shows that results tied directly to hyperscaler capital spending can still command a premium when the numbers are this strong.
For portfolio managers the figures raise the usual question of valuation versus momentum. A 2027 adjusted EPS forecast of $21.50 would be nearly double the $11.30 outlook management gave in July for 2026, and any shortfall in hyperscaler spending, component supply or margin delivery would hit a stock now priced for flawless execution. Customer concentration is the main structural risk, since results depend on a small group of very large cloud customers whose budgets can shift quickly.
Timing also matters. With the Fed’s decision and major cloud-provider earnings due Wednesday, traders chasing the gap should expect volatility, and a measured approach, such as scaling in after the first hour of trading, may be more prudent than buying the opening print. Celestica’s investor day should provide more detail on the 2027 bridge, and analysts will likely scrutinize how much of the growth is already contracted versus forecast by customers.