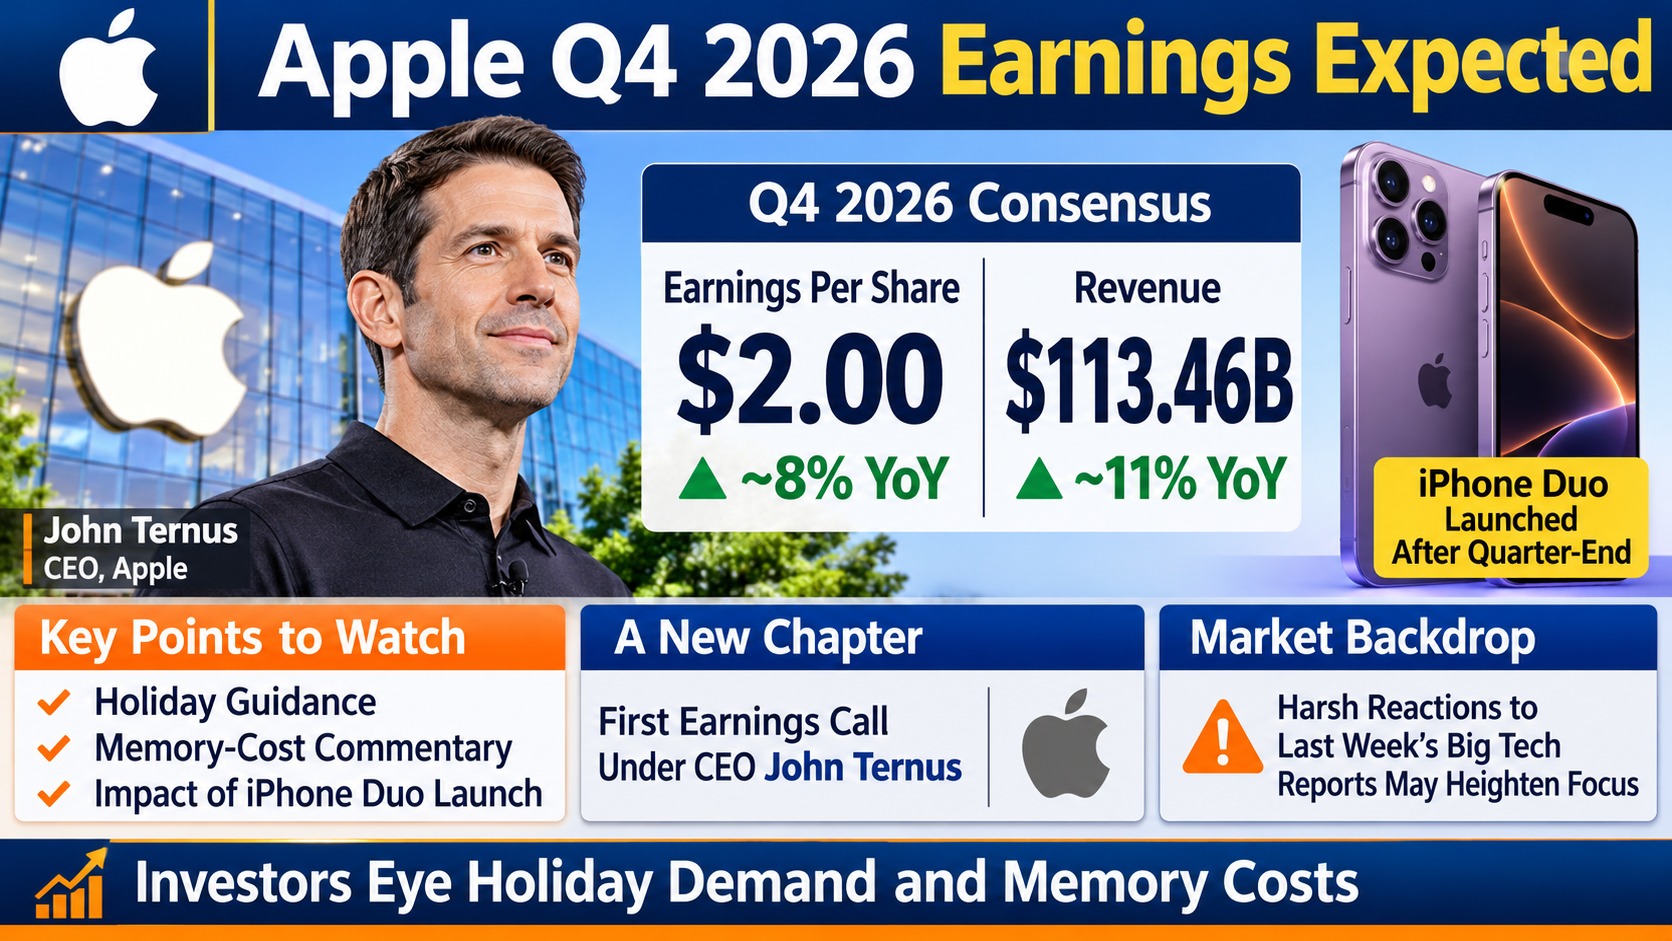
Apple reports fiscal fourth-quarter results after the closing bell on Monday, and Wall Street expects earnings of $2.00 per share on revenue of $113.46 billion, according to Bloomberg consensus cited by Yahoo Finance. That compares with $1.85 per share and $102.46 billion a year earlier, implying earnings growth of about 8% and revenue growth of roughly 11%. Shares slipped slightly in premarket trading as investors positioned for the report.
The print is the first earnings call under new chief executive John Ternus, who took over from Tim Cook on September 1. Investors will look for continuity in capital returns and services momentum, but also for any shift in tone on product strategy, pricing and artificial intelligence under the new leadership team.
Product timing complicates the read. The iPhone Duo went up for preorder on October 16 and went on sale on October 23, so its launch sales fall outside the fiscal fourth quarter that ended in September. Management could still offer color on early demand for the new iPhone 18 Pro lineup and the Duo during the call, and guidance for the holiday quarter is likely to matter more than the backward-looking numbers.
The setting is unforgiving. Big Technology earnings last week produced punishing reactions: Alphabet fell 13% after missing on revenue and profit, and Intel lost about a quarter of its value after a weak outlook that cited soft PC demand tied to higher memory costs. Analysts quoted by Yahoo Finance described the sell-off as a reflection of higher investor expectations rather than outright weak fundamentals, which raises the bar for Apple to deliver a clean beat and confident guidance.
Memory pricing is one area to monitor. If component costs are rising across the PC and device supply chain, as Intel's commentary suggested, investors may listen for how Apple describes gross-margin pressure and its ability to offset it through pricing or mix. Services revenue, which carries higher margins, and the pace of upgrades in key regions including Greater China are the other recurring focus points.
Context from the broader market is mixed. Nasdaq-100 futures were up about 0.75% on Monday after the index briefly entered correction, and chipmakers rebounded premarket. Oil prices fell on hopes of US-Iran diplomacy, which eases consumer-cost concerns, while the 10-year Treasury yield near 4.93% continues to weigh on large-cap growth valuations.
For paper-trading purposes, this is an event-risk name rather than a momentum entry. Apple's post-earnings move will likely set the tone for Tuesday's session, which also carries the US midterm elections, and for the remaining Big Technology reporting this week. Sizing ahead of the report should reflect the possibility of a sharp gap in either direction when the after-hours session opens.
Beyond the headline numbers, the call will also be read for commentary on capital return, since Apple has historically used large buybacks to support per-share growth. Any change in the pace of repurchases, or in how management describes tariff and supply-chain costs, could influence how the market values the shares heading into the holiday quarter.