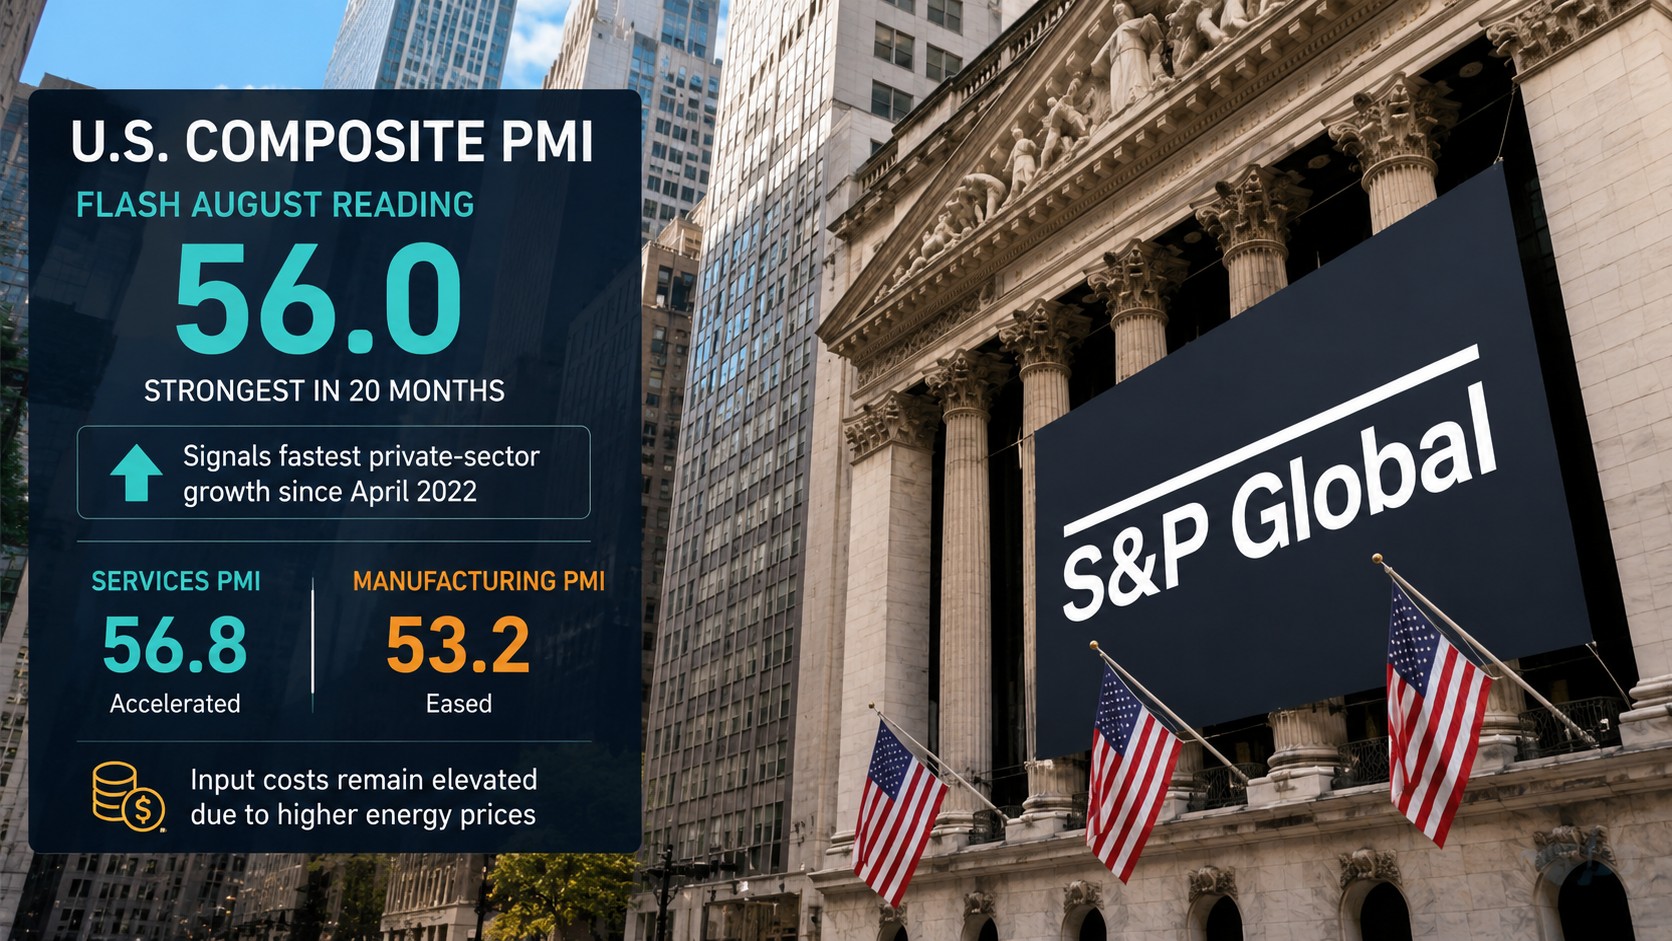
S&P Global reported that U.S. private-sector business activity expanded at the fastest pace in 20 months during August according to its flash Purchasing Managers’ Index surveys. The Composite Output Index climbed to 56.0 from 54.5 in July, marking the strongest reading since April 2022.
The improvement was driven almost entirely by the services sector, where the Business Activity Index jumped to 56.8 from 54.6, a 20-month high. Manufacturing activity moderated, with the Manufacturing PMI slipping to 53.2 from 53.9, still indicating expansion but at a slower rate. Factory output growth was dampened by reduced inventory building and some supply delays.
Chris Williamson, chief business economist at S&P Global Market Intelligence, noted that the data signal a marked acceleration of growth in the third quarter so far. Firms reported rising optimism and solid demand, particularly in consumer-facing and financial services. Price pressures cooled on the selling-price side even as input costs stayed elevated, largely reflecting higher energy prices linked to Middle East tensions.
The strong services reading provided a constructive backdrop for equity markets on Friday after a difficult week dominated by rising Treasury yields and geopolitical concerns. Economists said the data reduce the likelihood of an imminent Federal Reserve rate hike while still leaving open the possibility of further policy adjustment later in the year depending on upcoming inflation reports.
Final PMI figures for August are scheduled for early September. Markets will next focus on the personal consumption expenditures price index for additional insight into the inflation trajectory.