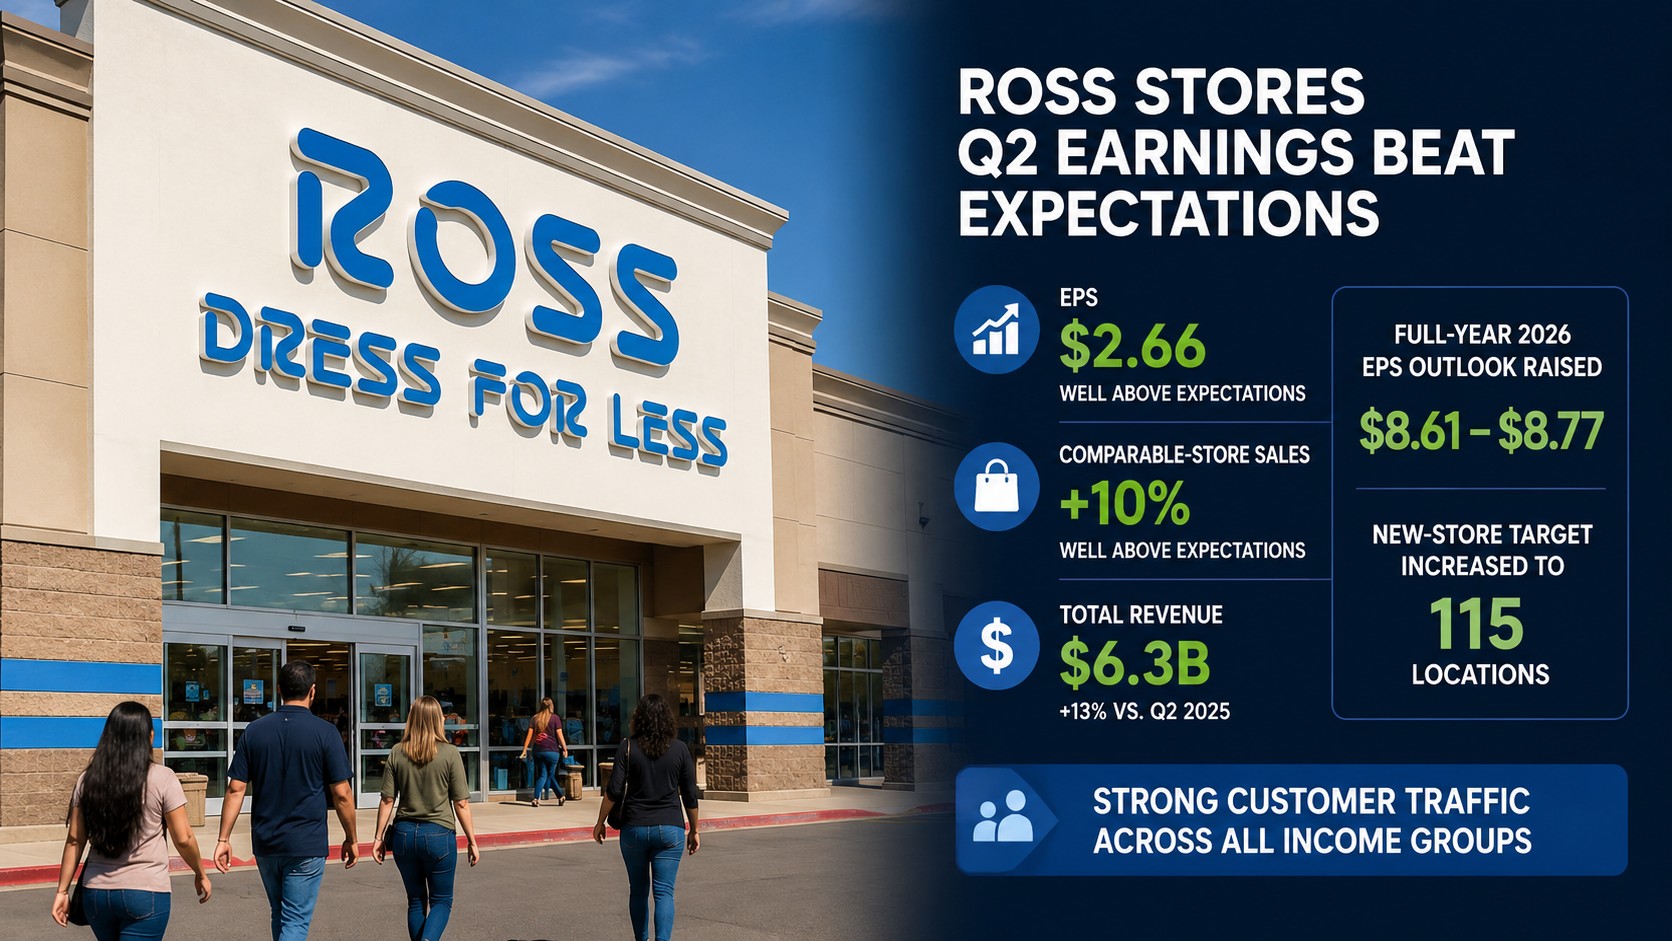
Ross Stores delivered a robust second-quarter performance that exceeded Wall Street forecasts on both the top and bottom lines. The company reported diluted earnings per share of $2.66, which included an approximate $0.60 benefit from tariff refunds, compared with the consensus estimate near $1.94. Total sales increased 13 percent year-over-year to $6.3 billion while comparable-store sales climbed 10 percent, driven primarily by higher customer traffic.
Chief Executive Jim Conroy highlighted gains from both new and existing customers across a wide range of income and age demographics. Merchandise margins expanded and operating income rose sharply. Inventory levels increased to support the stronger sales pace and improved product availability.
Management raised its fiscal 2026 earnings-per-share guidance to a range of $8.61 to $8.77 from the prior $7.50–$7.74 outlook. Third-quarter comparable sales are now expected to rise 6–7 percent with EPS of $1.75–$1.83. Fourth-quarter comps are projected up 4–5 percent with EPS of $2.17–$2.26. The company also lifted its planned new-store openings for the year to 115 locations from 110.
Shares of Ross Stores responded positively in Friday trading after the Thursday after-hours release, outperforming broader retail peers. The results stood in contrast to the more cautious consumer picture painted by Walmart’s slower comparable-sales growth reported the same day. Off-price retailers continue to benefit from value-seeking shoppers amid elevated gasoline prices and broader cost-of-living pressures.
Investors will monitor whether the strong traffic trends persist into the back half of the year as the company expands its store base and leverages closeout merchandise opportunities.