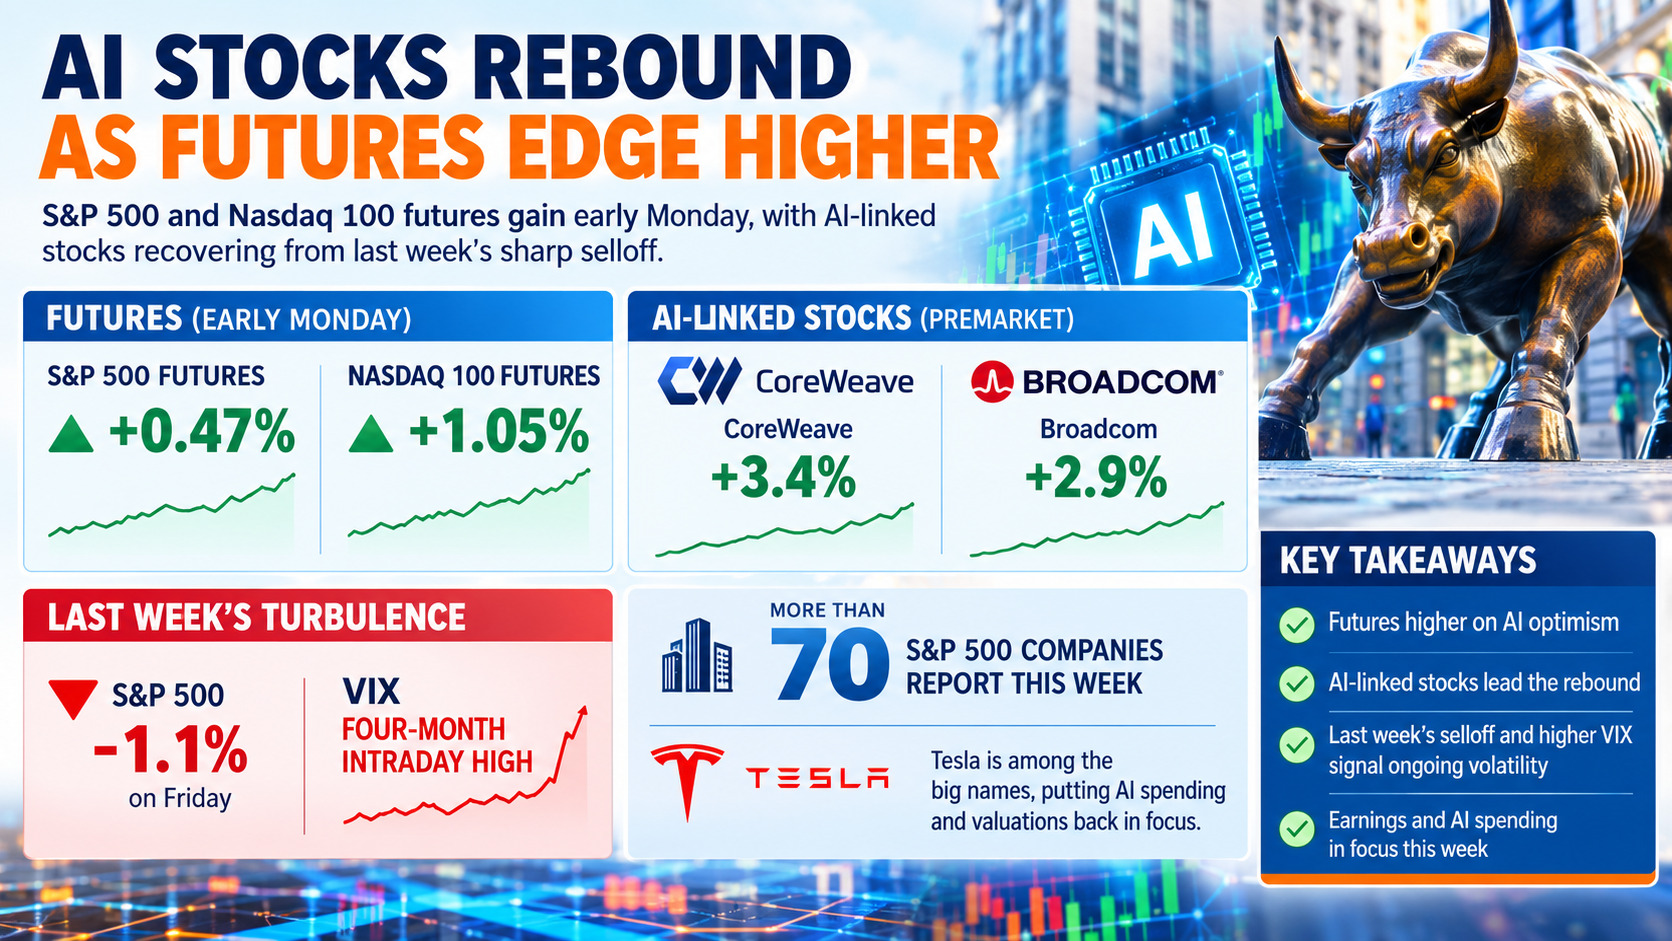
U.S. equity index futures pointed to a firmer open on Monday, October 19, as technology shares tied to artificial intelligence bounced from a punishing prior week. At 7:05 a.m. ET, S&P 500 E-mini futures were up 36.5 points, or 0.47%, and Nasdaq 100 E-minis had added 307.5 points, or 1.05%, according to Reuters. Dow E-minis were down 73 points, or 0.14%, a split that underlines how concentrated the rebound is in growth and chip names.
The bounce follows a rough close to last week. The S&P 500 fell 1.1% on Friday to finish its worst week since June, and the VIX climbed to a four-month intraday high as technology shares slumped, Bloomberg reported. Other coverage put the Nasdaq's weekly decline at more than 4%, its steepest since early June, amid concerns about AI spending and valuations that hit neocloud operators especially hard.
Premarket moves were led by the names that suffered most. CoreWeave, which plunged more than 25% last week, climbed 3.4% in early trading, while Broadcom and Micron added 2.9% and 3.3%, respectively. Among megacaps, Nvidia and Amazon each rose more than 1%, while Apple and Meta were marginally lower. A decline in oil prices and Treasury yields provided additional support, easing two of the macro pressures that had weighed on risk appetite.
The calendar is crowded. More than 70 S&P 500 companies, nearly 15% of the index, are due to report this week. Netflix and SpaceX are scheduled for Tuesday, alongside GE Aerospace, RTX, 3M and General Motors, while Meta and Tesla follow on Wednesday with IBM also on deck. Monday itself is light on major reports, with Cleveland-Cliffs and Fifth Third among the notable morning releases, leaving index direction largely to AI sentiment and macro headlines.
Overseas, investors are watching a batch of Chinese economic data, including third-quarter gross domestic product, after authorities moved last week to shore up the country's equity market by urging companies and state funds to buy shares. Geopolitical risk remains elevated, and U.S. midterm elections are only a few weeks away, adding another layer of uncertainty to positioning.
Sentiment is cautious beneath the surface. Stocktwits data showed retail sentiment toward the SPDR S&P 500 ETF slipping into bearish territory, and traders noted that Monday marks the 39th anniversary of the 1987 Black Monday crash. Even so, a Stocktwits poll of more than 12,500 respondents found 46% expect the S&P 500 to gain more than 1% this week, versus 31% who expect a drop of more than 1%.
For traders, the key question is whether premarket strength in AI infrastructure names can hold through the cash open. Futures moves ahead of a heavy earnings week tend to say less about the eventual outcome than the reports themselves, and results from Tesla, Meta and others will test whether capital spending plans and AI monetization justify current valuations. A fade in chip and neocloud shares would reinforce last week's risk-off tone, while a sustained bid would suggest the selloff was a positioning reset rather than a change in the AI thesis.
Investors should treat the morning bounce with caution given the elevated VIX, concentrated earnings risk and thin Monday news flow. Position sizing and defined stops matter more than conviction until the week's major reports clear. This article is for informational purposes only and is not investment advice.