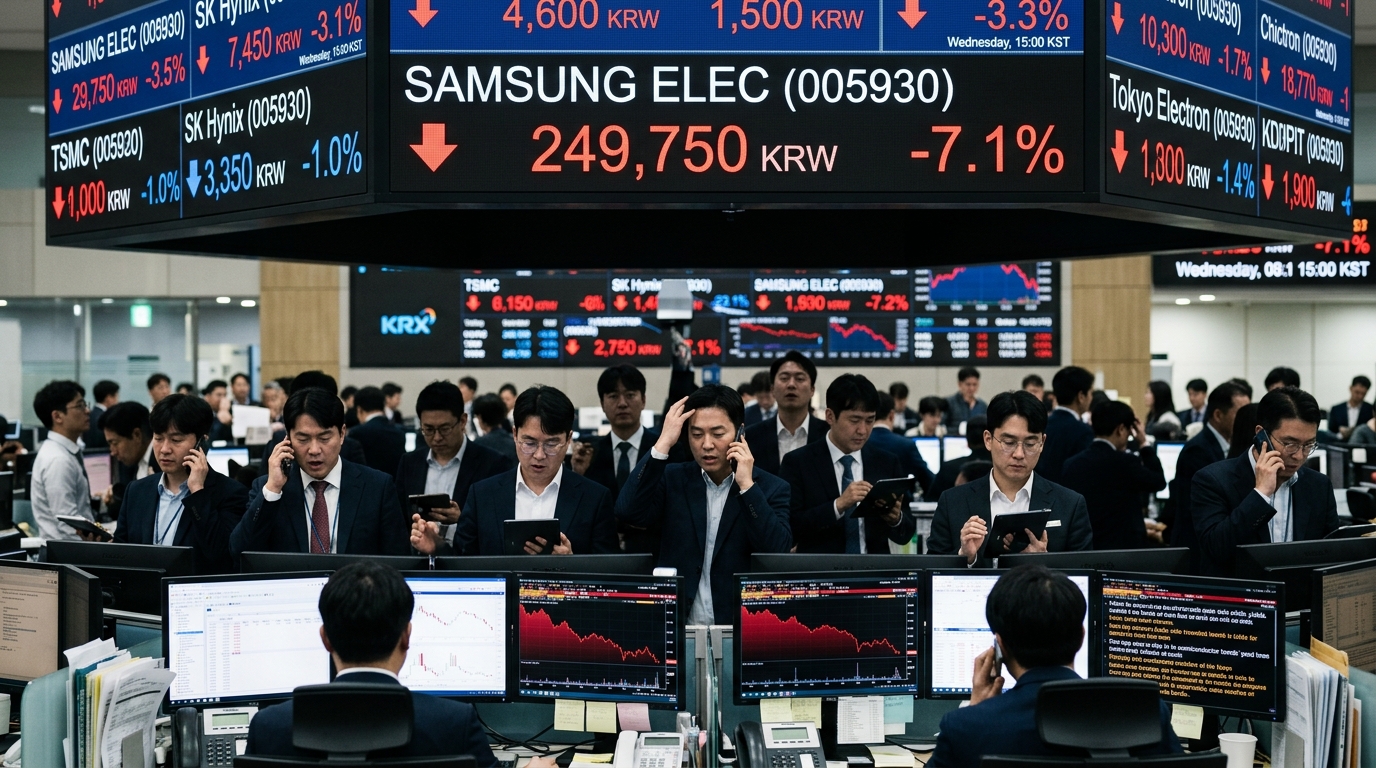
Shares of Samsung Electronics fell 7% to 249,750 won Wednesday, leading a broad selloff in semiconductor stocks across Asian and European markets as a surge in global government bond yields to multi-decade highs prompted investors to reassess valuations across the technology sector.
The decline in Samsung shares came alongside broader weakness in chip stocks internationally. In Europe, the technology component of the STOXX 600 index fell 0.4% even as the broader benchmark held roughly flat at 652.07, with French chipmaker Soitec dropping 4.4% and Norway's Nordic Semiconductor also declining. The pressure reflected a combination of elevated bond yields, which raise the discount rate applied to future earnings and weigh disproportionately on high-growth technology valuations, and lingering caution around the pace of artificial intelligence infrastructure spending.
The selloff comes as 30-year government bond yields in the United States, France and Germany have all climbed toward multi-decade highs this month, driven by investor concern over persistent inflation and difficult-to-contain fiscal deficits across major economies. Rising long-term borrowing costs have historically pressured richly valued growth stocks, including semiconductor companies whose valuations often reflect expectations of strong earnings growth many years into the future.
Despite Wednesday's decline, the memory chip segment specifically received some offsetting news, as South Korean rival SK Hynix separately announced a 40 trillion won ($28.61 billion) treasury share buyback and cancellation program, underscoring the extraordinarily strong cash generation many memory makers have captured amid booming demand for artificial intelligence infrastructure. The divergence between Samsung's stock decline and SK Hynix's capital-return announcement highlights how stock-specific and company-level catalysts continue to matter even amid a broader macro-driven selloff.
The chip sector's volatility comes ahead of a closely watched earnings report from Wolfspeed, the U.S. silicon carbide semiconductor maker, which is scheduled to release its fiscal fourth-quarter results after Wednesday's market close. Wolfspeed shares have already declined heading into the report amid investor concerns about the company's persistent negative margins, adding to the cautious mood across the broader chip complex.
Analysts have generally attributed this week's semiconductor weakness to a combination of macro factors—rising bond yields and a stronger dollar—rather than any deterioration in the underlying demand outlook for AI-related chips, which most industry forecasters continue to expect will remain robust through the remainder of 2026 and into 2027. Still, the sharp pace of Wednesday's declines underscores how sensitive richly valued technology stocks have become to shifts in the interest-rate environment, even when company-specific fundamentals remain largely intact.
Investors will be watching Wolfspeed's results, along with any further movement in global bond yields, for signals on whether Wednesday's selloff proves to be a brief pullback or the start of a more sustained rotation away from high-growth technology names.
The cross-currents in the chip sector—falling shares alongside a major buyback announcement and rising yields—illustrate the difficulty investors currently face in separating company-specific catalysts from broader macroeconomic pressure on technology valuations.