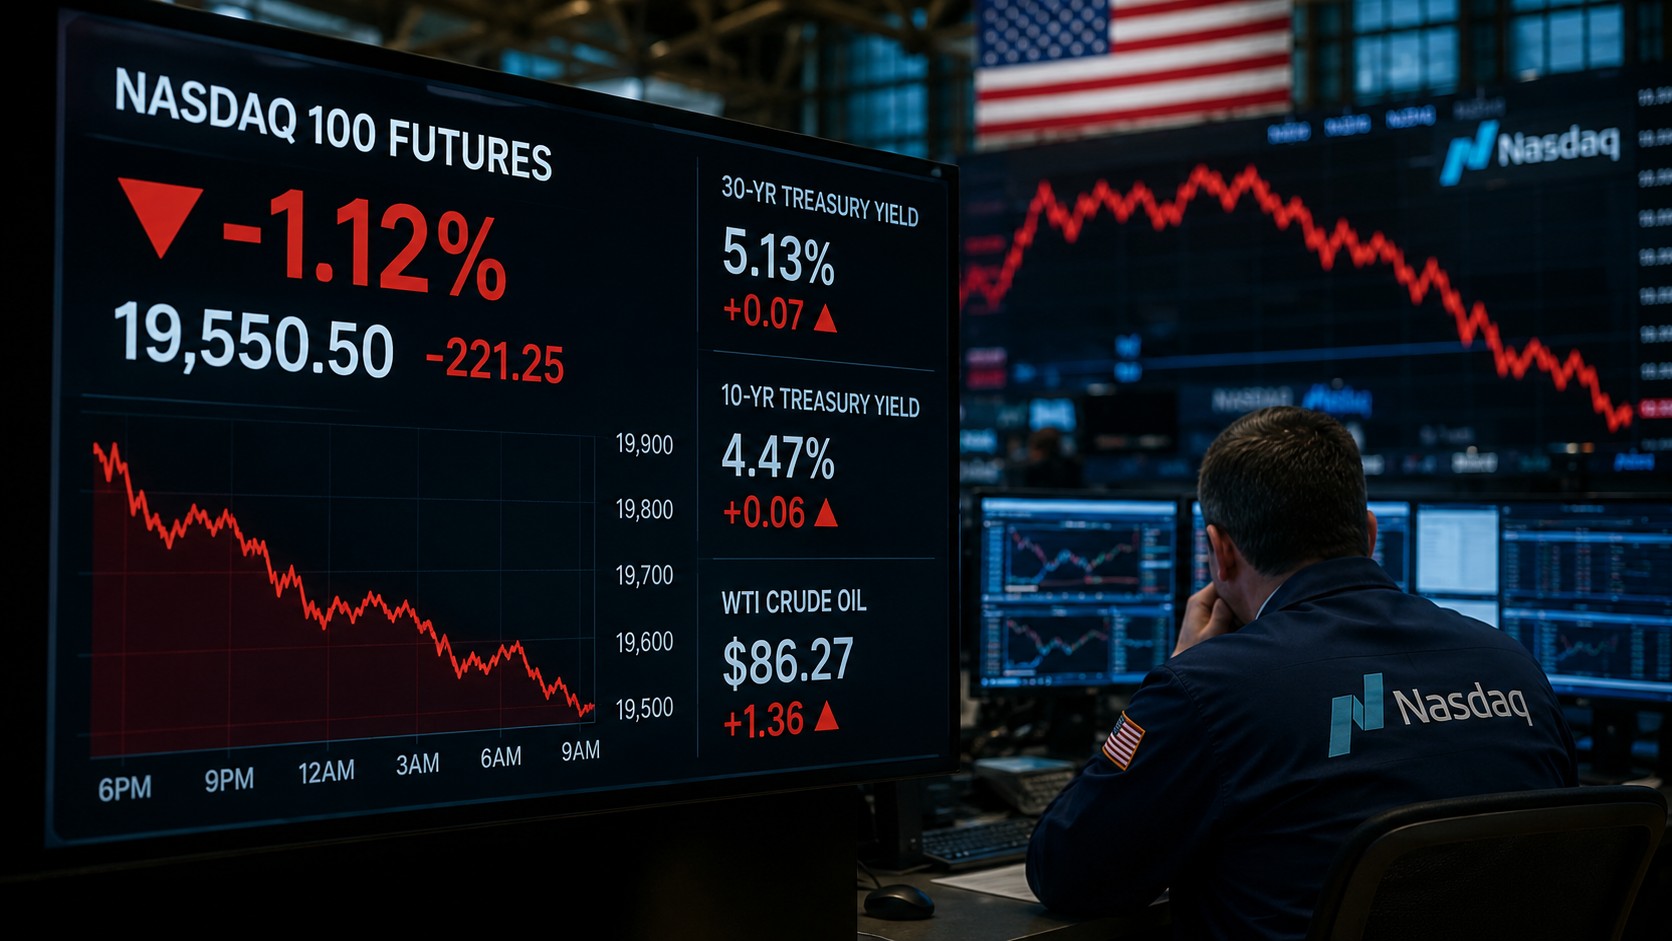
Nasdaq 100 futures fell more than 1% in premarket and early session trading as semiconductor, memory and broader technology shares retreated. The move coincided with a continued rise in long-dated Treasury yields and elevated crude oil prices following the expiration of the U.S.-Iran interim ceasefire.
Memory and storage names that had outperformed earlier in the week reversed course, with several large-cap chipmakers posting premarket declines of 2% to 6%. Higher discount rates implied by the climb in the 30-year and 10-year Treasury yields pressured valuation multiples across the growth complex, while the energy-price backdrop added to inflation concerns that could keep the Federal Reserve on hold or potentially more hawkish.
The technology sector had been a primary driver of the S&P 500’s recent record highs, fueled by strong artificial-intelligence infrastructure spending and better-than-expected corporate earnings. The current pullback reflects a reassessment of how much of that optimism is already priced in once real yields and energy costs move higher.
Equity index futures overall pointed lower, with the S&P 500 also in negative territory while the Dow showed more resilience. Energy shares found relative support from the higher oil price deck. Market participants will watch whether the yield and oil moves stabilize or extend, as sustained pressure on growth multiples could broaden into a more defensive rotation.
In the near term, the combination of geopolitical uncertainty, rising long-term rates and stretched technology valuations argues for selective exposure rather than broad beta to the Nasdaq. Earnings resilience remains a key offset, but the macro cross-currents have clearly intensified.