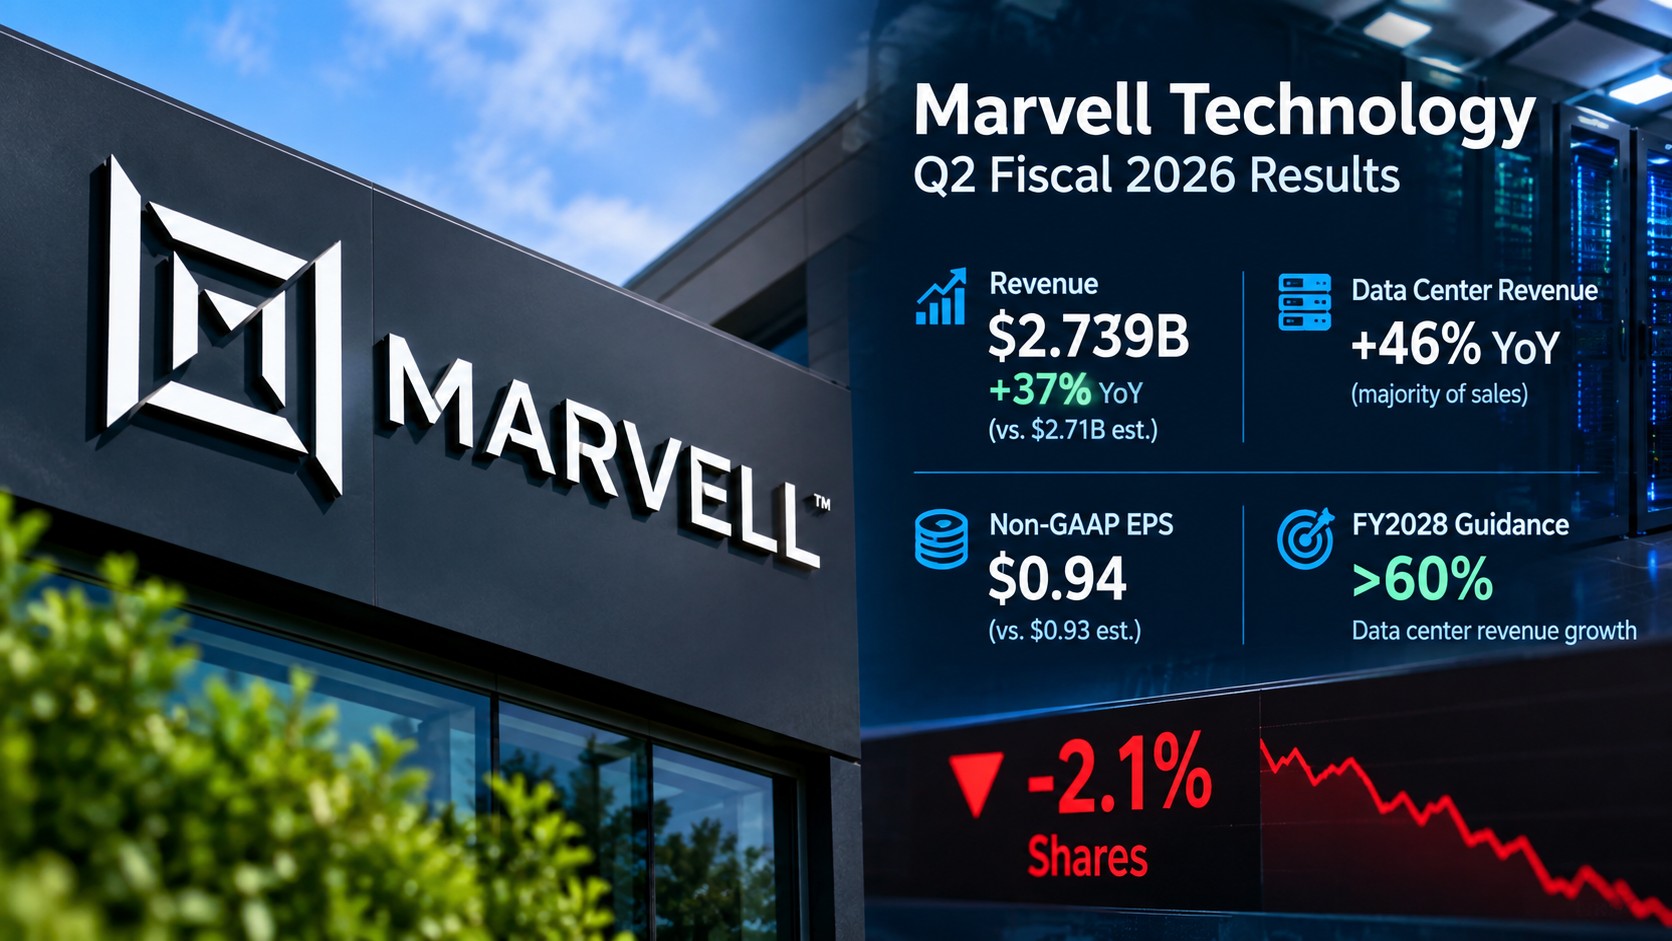
Marvell Technology reported record fiscal second-quarter 2027 revenue of $2.739 billion, up 37% year-over-year and 13% sequentially, topping the roughly $2.71 billion to $2.72 billion Wall Street had expected and exceeding the midpoint of the company's own guidance by approximately $39 million. Non-GAAP earnings per share came in at $0.94, essentially in line with the $0.93 analyst consensus.
Data center revenue, Marvell's largest and fastest-growing segment, climbed 46% year-over-year, continuing to represent the majority of the company's total sales. Non-GAAP operating margin expanded to 36.6% from prior-year levels, reflecting continued scale benefits even as the company invests heavily in custom silicon and AI-related product development.
Despite the headline beat, shares of Marvell fell more than 2% in the session following the report, extending a decline that saw the stock drop as much as 6% at one point in early trading. Investors focused on a gross margin outlook that trailed trailing levels, reflecting a mix shift toward custom application-specific integrated circuits, which typically carry lower margins than Marvell's standard merchant silicon products even as they represent a larger and more strategically important part of the business.
Chief Executive Matt Murphy told investors the company continues to see exceptional demand for AI-related infrastructure, with management projecting data center revenue growth of more than 60% in fiscal 2028. Marvell guided third-quarter revenue to approximately $3.15 billion at the midpoint, roughly 4% above what analysts had been expecting, with the company reaching the $3 billion quarterly revenue milestone a full quarter ahead of its previous outlook.
The report follows a turbulent stretch for Marvell shares, which hit an all-time high above $329 in June before falling to a low near $163 in late July amid broader concerns about custom silicon competition and valuation, then rebounding nearly 50% off those lows heading into Thursday's report. The stock's reaction to Thursday's results suggests investors remain focused on margin trajectory and the durability of Marvell's positioning relative to larger rivals such as Broadcom and Nvidia in the AI custom-chip market.
Marvell's recently announced partnership with Google, under which the search giant would receive warrants tied to as much as $120 billion in future chip orders, continues to be viewed by analysts as a significant long-term catalyst for the company's custom silicon business, even though the arrangement could dilute Marvell's outstanding share count by several percentage points over time as the warrants vest.
Thursday's results followed a strong quarter from rival Broadcom and came one day after Nvidia's blowout earnings report, giving investors an unusually data-rich stretch for gauging demand trends across the AI chip supply chain. Analysts said Marvell's results, while solid on an absolute basis, may simply have been unable to clear the extremely high bar set by a market that has grown accustomed to near-flawless beat-and-raise quarters from AI infrastructure suppliers.
With shares still up roughly 180% over the trailing twelve months despite Thursday's pullback, some analysts characterized the decline as a natural digestion of an extended rally rather than a fundamental reassessment of Marvell's AI growth story, though the muted margin outlook will likely remain a focus for investors heading into the company's next report.