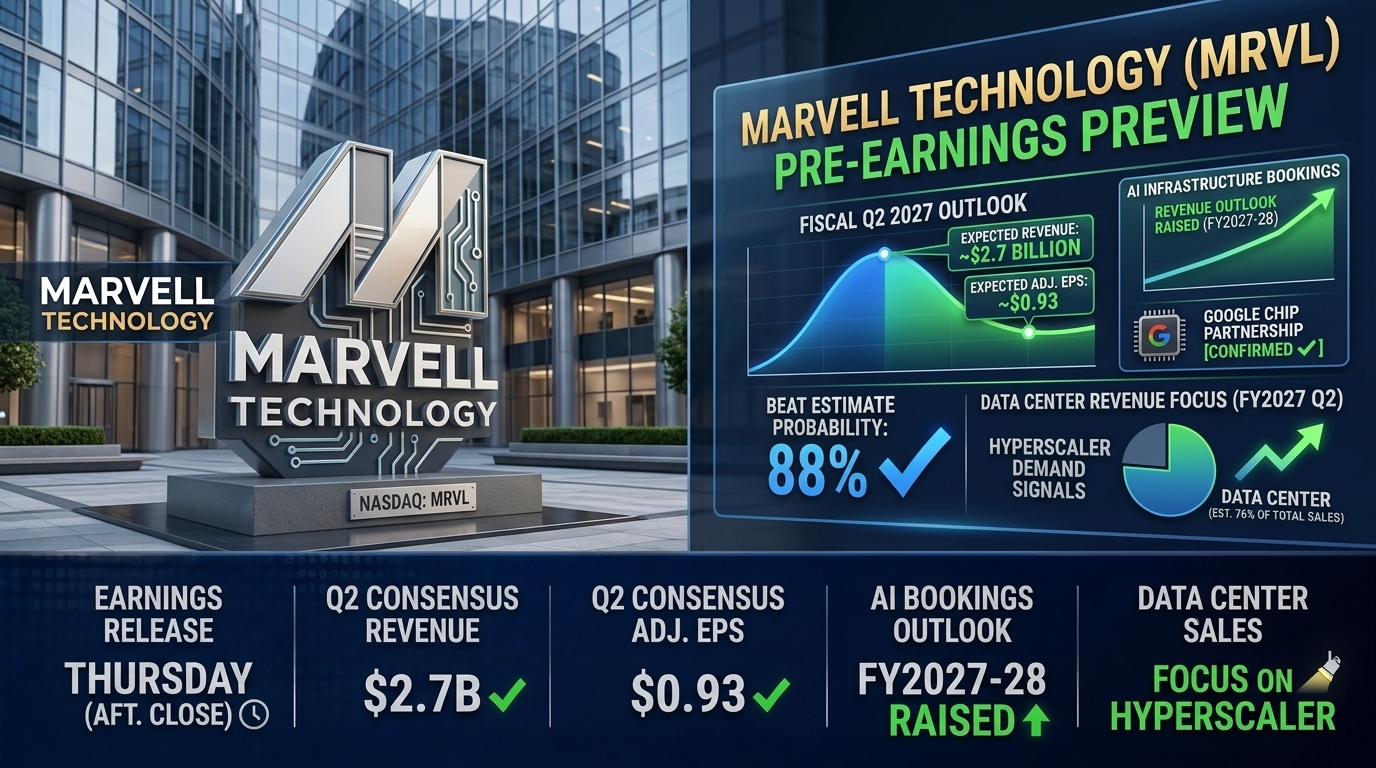
Marvell Technology is scheduled to report fiscal second-quarter 2027 earnings Thursday after the market close, capping a week dominated by results from some of the most closely watched names in artificial intelligence infrastructure. Wall Street expects revenue of approximately $2.7 billion, plus or minus 5% per the company's own guidance, with adjusted earnings per share projected near $0.93.
The chipmaker has increasingly become a key bellwether for the broader AI infrastructure buildout, given its growing custom silicon business supplying specialized chips to major cloud providers. Chief Executive Matt Murphy told investors on the company's prior earnings call that Marvell was seeing "exceptional AI-related bookings," prompting management to significantly raise its revenue outlook for both fiscal 2027 and fiscal 2028. The company has guided to nearly $11.5 billion in fiscal 2027 revenue, up roughly 40% year-over-year, with fiscal 2028 revenue targeted at approximately $16.5 billion.
Data center revenue, which accounts for roughly 76% of Marvell's total sales, will be in sharp focus, particularly given investor concerns about the extent to which major hyperscale cloud providers might increasingly design chips in-house rather than relying on external suppliers. Marvell has pushed back on that narrative, with management pointing to custom engagements across all major U.S. hyperscalers and arguing that its long-range revenue outlook is built on already-won and locked-in chip designs rather than speculative future business.
The company's recently announced partnership with Google has drawn significant investor attention. Under the arrangement, Google would receive a warrant to purchase nearly 59 million Marvell shares, a structure that could dilute Marvell's outstanding share count by roughly 7% over time but that analysts view as reflecting a deep, multi-year custom silicon commitment from one of the world's largest cloud providers. Any updated commentary on the scope or timeline of that partnership will likely be closely parsed on Thursday's earnings call.
Prediction markets on Polymarket assign Marvell an 88% probability of beating quarterly earnings estimates, with the platform's contracts on the company's prior quarterly reports resolving with a 100% crowd-accuracy rate. Options markets tied to Marvell's August 28 expiration reflect a relatively low put-call ratio, suggesting positioning skewed toward upside scenarios heading into the print.
With shares trading at a trailing price-to-earnings ratio of nearly 83 and more than 24 times trailing 12-month sales, analysts note that Marvell's valuation leaves little room for disappointment. A guidance miss or any sign of moderating hyperscaler demand could trigger an outsized negative reaction, even as the base case among analysts, 38 of whom rate the stock a buy with zero sell ratings, points toward continued upside.
Thursday's report follows a week that has already delivered blowout results from Nvidia, Salesforce and CrowdStrike, giving investors an unusually data-rich stretch for gauging the health of AI-related capital spending across chips, cloud infrastructure and enterprise software heading into the fall.