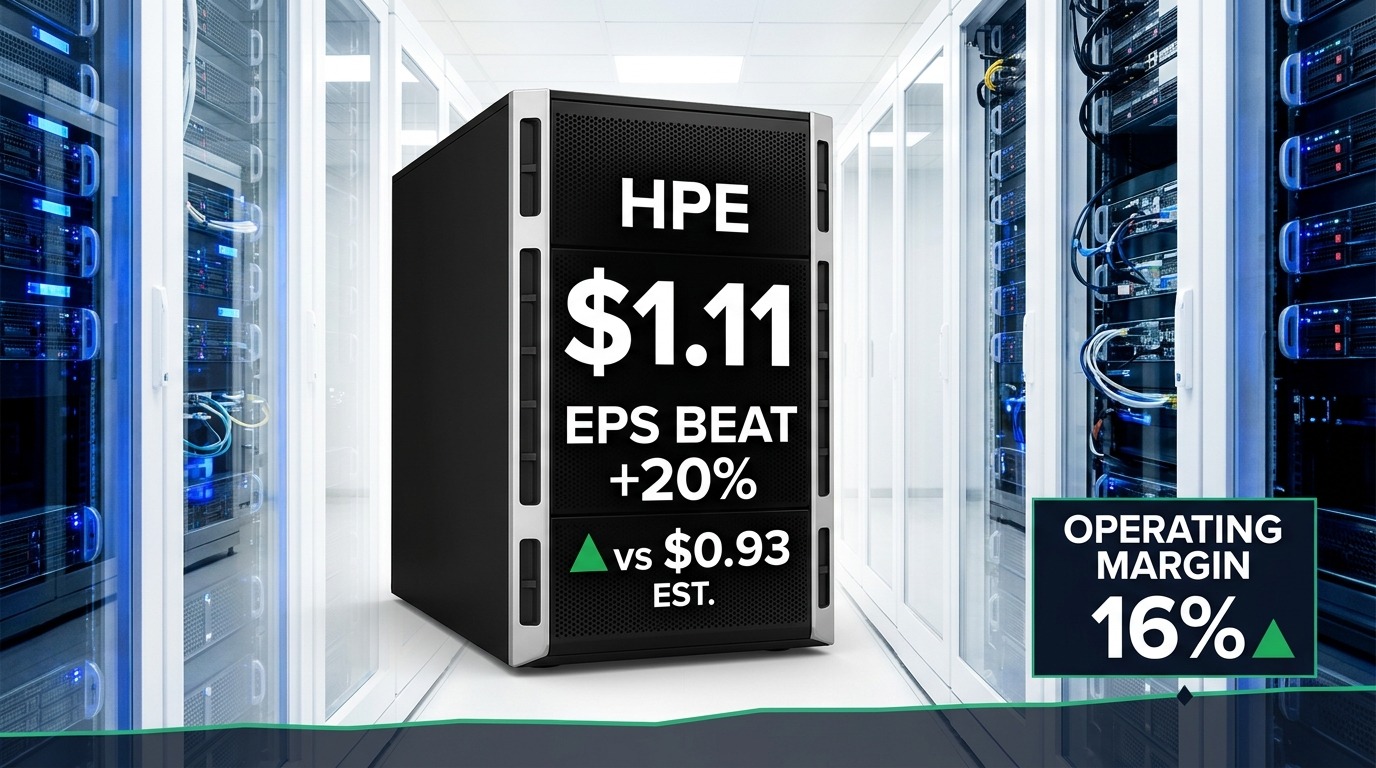
Hewlett Packard Enterprise (HPE) delivered another quarter of outsized profit growth, with results that showed the company's bet on artificial intelligence infrastructure is increasingly translating into bottom-line gains rather than just top-line momentum. The enterprise technology company reported fiscal third-quarter adjusted earnings per share of $1.11, beating the $0.93 Wall Street consensus by roughly 20% and marking a fifth consecutive quarter of topping expectations.
Revenue rose approximately 32.7% to 33.7% year over year to roughly $12.2 billion, also ahead of analyst estimates and representing a sharp acceleration from the growth rates the company posted in the same period a year earlier. Perhaps most notable was the improvement in profitability: non-GAAP operating margin nearly doubled to about 16.2%, up from 8.5% in the year-ago quarter, evidence that the company's AI infrastructure buildout has become a genuine inflection point for earnings rather than simply a revenue growth story.
President and Chief Executive Antonio Neri said the results reflect the durability of the company's profitable growth momentum, pointing to record revenue, orders, and profitability driven by surging customer demand across HPE's portfolio. The company's push into higher-value networking, cloud, and AI solutions, including its expanded campus and branch networking, data center switching, and security offerings, has been a central pillar of the turnaround management has pursued over the past several quarters.
AI infrastructure demand in particular has become the company's key growth catalyst, with customers increasingly investing in AI inferencing, agentic AI systems, and data-intensive workloads that require HPE's compute, networking, and storage products. The company has also been expanding its turnkey AI Factory and Private Cloud AI offerings, some of which are co-engineered with Nvidia, to help enterprise customers deploy AI systems more quickly without building the underlying infrastructure themselves.
Looking ahead, management issued next-quarter revenue guidance at the midpoint of roughly $14.35 billion, which came in about 10% above what analysts had been modeling, while also raising full-year fiscal 2026 non-GAAP earnings guidance to a range of $3.75 to $3.85 per share. The company additionally set a fiscal 2027 free cash flow target of at least $5 billion, underscoring management's confidence that the current pace of AI-driven demand and margin expansion is sustainable rather than a one-quarter anomaly.
The results extend a string of strong prints from enterprise hardware and infrastructure companies this earnings season, as data center buildouts tied to generative AI continue to drive orders across the sector. Analysts have noted that HPE's improving margin profile, in particular, differentiates this quarter's report from earlier periods when the company's AI-related revenue growth came with thinner profitability, suggesting the business is beginning to capture more of the economics from the AI infrastructure cycle rather than competing purely on volume.