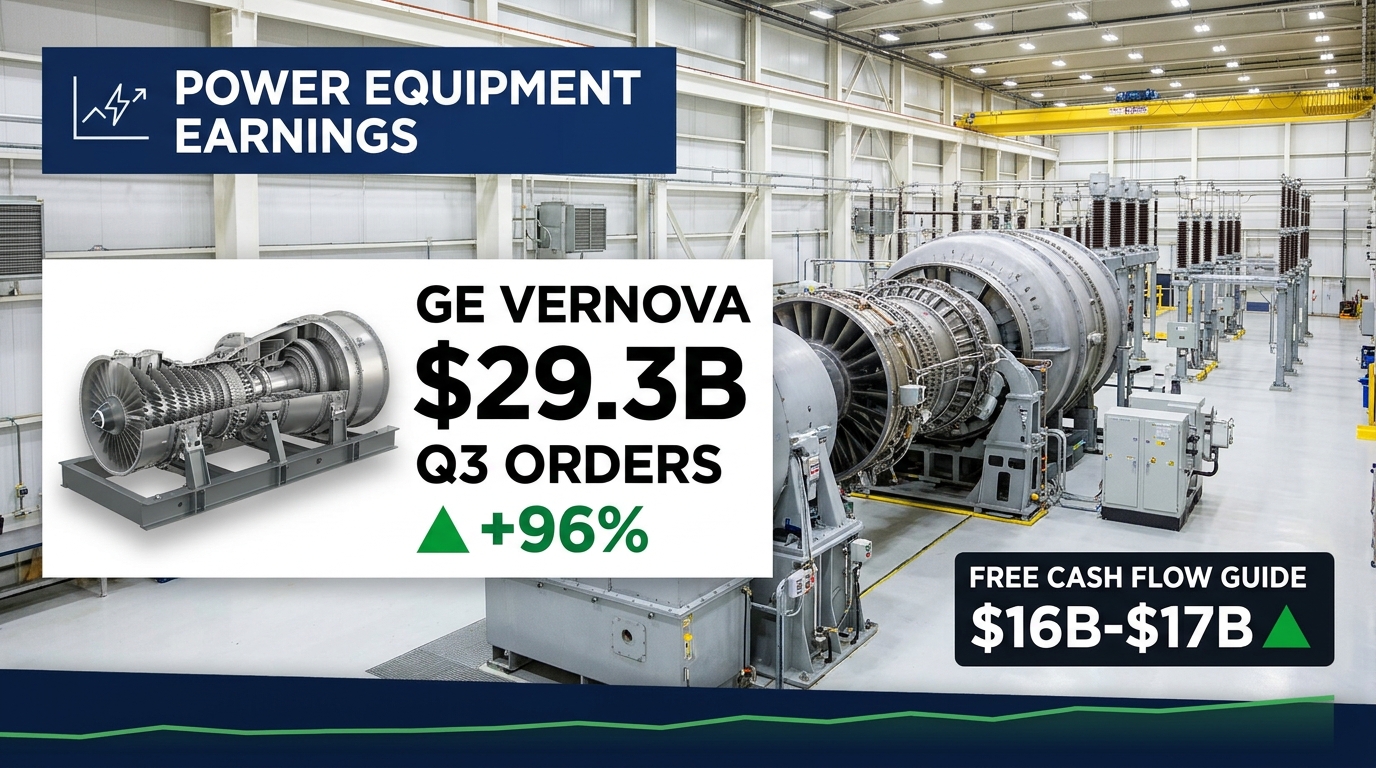
GE Vernova reported third-quarter 2026 results before the market open on Wednesday, posting orders of $29.3 billion, up 96% organically, and lifting its full-year guidance for revenue, adjusted EBITDA margin and free cash flow. The report reinforced the view that demand for electricity infrastructure, driven by data centers and grid upgrades, remains one of the strongest themes in U.S. industrial markets.
Revenue rose 27% to $12.6 billion, or 18% on an organic basis, topping the $11.99 billion that analysts had expected ahead of the report. Net income reached $1.3 billion, or $4.81 per diluted share, compared with $1.64 a year earlier. Adjusted EBITDA more than doubled to $1.9 billion, with the adjusted margin widening to 15.4% from 8.1%, a gain of 690 basis points on an organic basis.
Power was the engine. Segment orders of $21.8 billion rose 178% organically on strong gas turbine equipment demand, including 55 heavy-duty units and 57 aeroderivative turbines. The company signed 11 gigawatts of new gas equipment contracts, and its combined gas equipment backlog and slot reservation agreements grew from 116 to 122 gigawatts. Management now expects to exit 2026 with at least 130 gigawatts under contract. Power segment EBITDA margin expanded 800 basis points to 21.4%.
Electrification and Wind also contributed. Electrification revenue rose 51% to $3.9 billion, including the acquired Prolec GE business, and its equipment backlog increased to $42.2 billion, up 60% from a year ago. Wind orders rose 16% organically to $2.1 billion, and segment EBITDA turned positive at $72 million as the company resolved all outstanding litigation tied to the Vineyard Wind project.
Cash generation was the standout. Free cash flow reached $5.4 billion in the quarter versus $732 million a year earlier, and cash from operations totaled $6.1 billion. GE Vernova ended September with $16.8 billion in cash and returned $5.7 billion to shareholders in the first nine months of 2026. In October the board raised the share repurchase authorization to $20 billion from $10 billion, leaving $10.1 billion available for future purchases.
The raised outlook is notable. GE Vernova now expects 2026 revenue of $46.5 billion to $47.5 billion, up from $45.5 billion to $46.5 billion, an adjusted EBITDA margin of 13.5% to 14.5%, up from 12% to 14%, and free cash flow of $16 billion to $17 billion, up from $11.5 billion to $12.5 billion. Total backlog grew $20 billion sequentially to $197 billion, and management expects it to exceed $200 billion in the fourth quarter with improved margins.
The company also announced an agreement in October to acquire Trench Group, a high-voltage grid equipment maker, for the equivalent of $9.0 billion, with closing expected in late 2027 subject to regulatory approvals. The deal would deepen the Electrification franchise at a time when utilities and data center developers are competing for transformers, switchgear and transmission equipment.
For investors, the setup is mixed despite the strong print. GE Vernova shares rose to roughly $900 in after-hours trading on Tuesday, and the stock fell sharply after its second-quarter report even though orders were strong, a reminder that expectations are high. Key risks include execution on rapidly expanding production, margin sustainability and sensitivity to interest rates, with the Federal Reserve decision due this afternoon. The next test is whether backlog converts to revenue at the pace implied by the raised guidance.