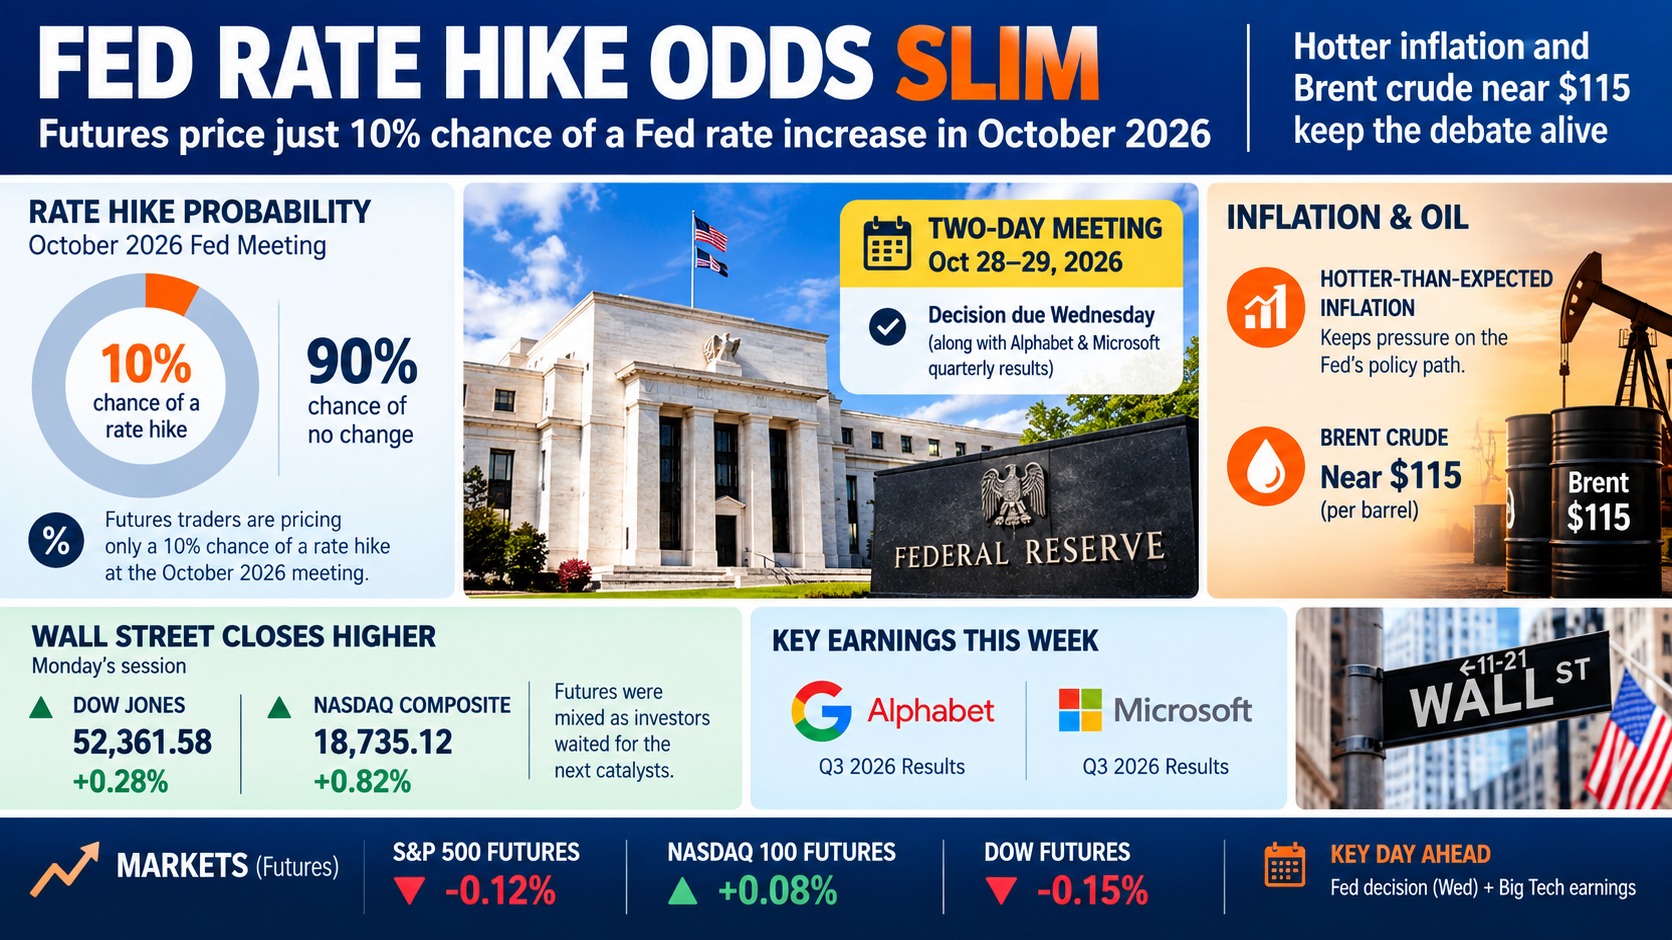
Federal Reserve policymakers opened a two-day meeting on Tuesday, October 27, 2026, with markets assigning only a small chance to a rate increase but watching closely for any shift in tone on inflation. According to CME Group pricing cited in market reports, traders see roughly 10% odds of a hike when the decision is announced on Wednesday. The question before officials is whether hotter-than-expected inflation calls for tightening.
The energy market is a major reason the question is being asked. Brent crude traded near $115 to $116 a barrel on Tuesday and West Texas Intermediate near $101 to $102, after Brent touched six-month highs last week on fears of further attacks on energy sites and commercial shipping. Fuel costs feed quickly into headline inflation and household budgets, which complicates any decision to hold rates steady.
U.S. equities entered the meeting on firm footing. On Monday the Dow Jones Industrial Average rose 146.42 points, or 0.28%, to 52,361.58, the Nasdaq Composite gained 214.04 points, or 0.82%, to 26,169.38, and the Russell 2000 advanced 0.38% to 2,786.43. Futures were mixed overnight and into Tuesday morning, with Nasdaq-100 contracts down about 0.3% at one point while Dow futures hovered near the flatline. In Asia, Japan’s Nikkei 225 rose between 1.7% and 2% and South Korea’s Kospi gained more than 3% as optimism around artificial intelligence lifted risk appetite.
Wednesday is shaping up as a high-density event day. Alphabet and Microsoft are scheduled to report third-quarter results the same day the Fed announces its decision, meaning investors will absorb policy guidance and the latest read on AI-driven cloud demand almost simultaneously. Earlier Tuesday, a long list of blue-chip companies were due to report, adding stock-specific volatility to an otherwise cautious tape.
Beneath the index-level calm, leadership has shifted sharply. Yahoo Finance reported that Wall Street spent October selling chip stocks and buying defensive names, with consumer staples on track for their best month in nearly five years and the average S&P 500 stock headed for its sharpest turnaround against the index in decades. In the latest session, 57 of 60 stocks in a Yahoo Finance semiconductor basket rose, yet the bounce barely dented the month’s scoreboard.
From a portfolio standpoint, the setup favors discipline over conviction. A hold with cautious language on inflation would probably keep the current rotation intact, while a hawkish surprise could pressure long-duration growth stocks and extend the bid for energy and defensive sectors. A dovish tilt, by contrast, could revive the chip rebound. With binary catalysts stacked on Wednesday, position size ahead of the announcement matters more than the direction of any single call.
Investors should also keep an eye on Treasury yields, the dollar and any update on U.S.-Iran diplomacy, all of which can move rate expectations within a single session. This is market commentary rather than investment advice; for a paper-trading account, treating event risk as the primary variable until the Fed and Big Tech results are in hand is the prudent approach.