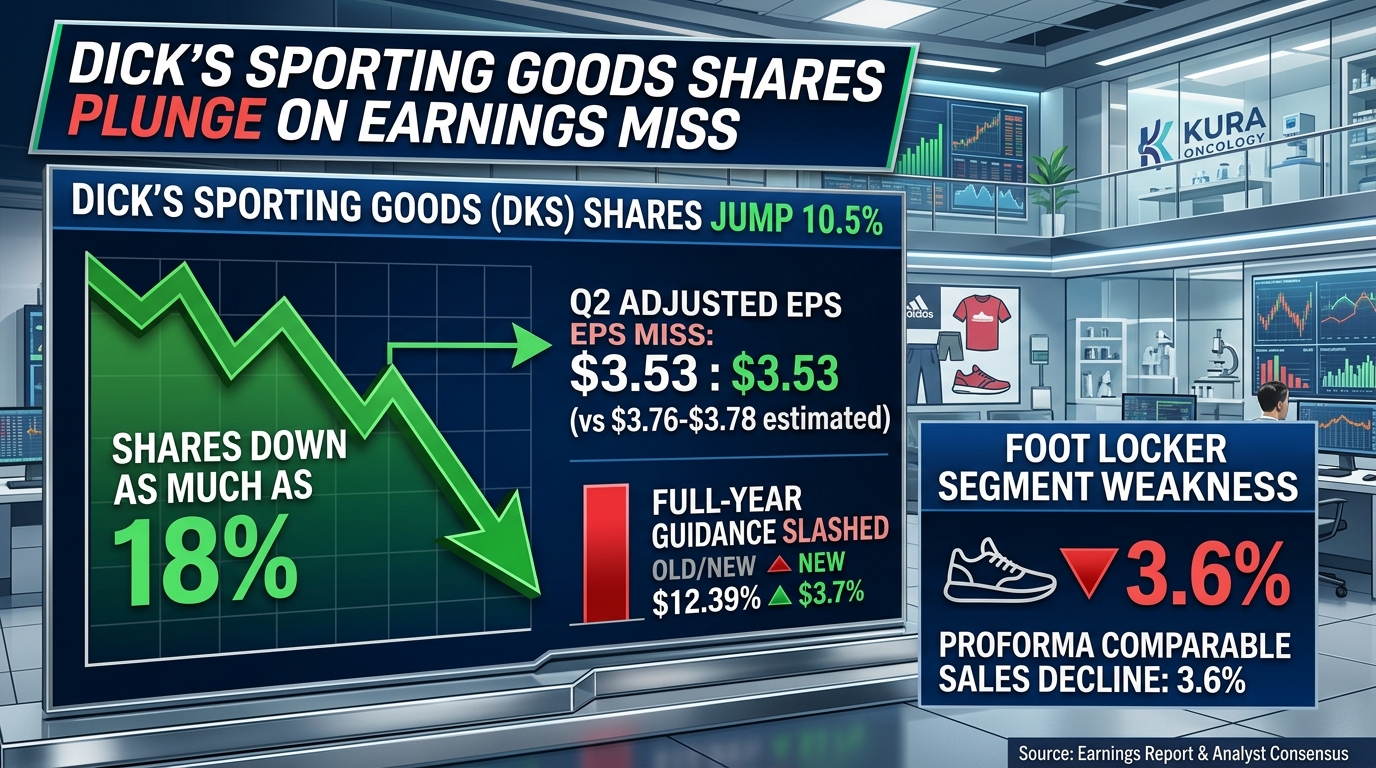
Shares of Dick's Sporting Goods plunged as much as 18% in premarket trading Tuesday after the sporting goods retailer missed Wall Street's second-quarter expectations and cut its full-year outlook, citing an increasingly promotional environment in the athletic footwear and apparel market.
The Pittsburgh-based retailer reported second-quarter net income of $315 million, or $3.50 per diluted share, down from $381 million, or $4.71 per diluted share, in the year-ago period. Excluding one-time items related to its Foot Locker acquisition, adjusted earnings came in at $3.53 per share, below the roughly $3.76 to $3.78 analysts had forecast. Net sales rose 53.2% to $5.59 billion, short of the $5.64 billion to $5.65 billion Wall Street consensus, with the increase driven primarily by the inclusion of the acquired Foot Locker business.
Results were mixed by segment. The core Dick's business, which includes Dick's Sporting Goods, Golf Galaxy, Going Going Gone! and Public Lands banners along with the GameChanger app, generated net sales of $3.8 billion, up from $3.6 billion a year earlier, with comparable sales growth of 4.9% driven by broad-based category strength and a boost from the 2026 FIFA World Cup. The Foot Locker segment, by contrast, posted net sales of $1.7 billion, with proforma comparable sales declining 3.6% amid challenging conditions across the athletic footwear marketplace.
Executive Chairman Ed Stack said conditions across portions of the athletic footwear and apparel market became increasingly promotional as the quarter progressed, prompting the company to adopt a more cautious posture. As a result, Dick's lowered its full-year adjusted earnings-per-share guidance to a range of $11.00 to $12.00, well below the roughly $14.20 analysts had penciled in prior to the report. Full-year revenue guidance was also trimmed to approximately $22.05 billion at the midpoint.
Dick's completed its roughly $2.5 billion acquisition of Foot Locker in September 2025, a deal aimed at expanding its footprint in athletic footwear and giving it greater scale in a competitive retail category. The company said Tuesday it has begun a review of underperforming Foot Locker assets and expects total pre-tax charges of up to $750 million from that process, including about $200 million in fiscal 2026 alone.
The stock's decline weighed on shares of other athletic retail and apparel names, with Nike and Academy Sports and Outdoors both trading lower in sympathy as investors reassessed demand trends across the footwear category more broadly. Analysts said the magnitude of the guidance cut, nearly 20% below prior expectations at the midpoint, raised questions about how quickly Dick's can stabilize the Foot Locker business it acquired less than a year ago.
The report adds Dick's to a growing list of retailers flagging a more promotional selling environment this earnings season, as consumers show increased price sensitivity even as overall retail spending has held up better than some economists expected. Investors will be watching upcoming retail sector reports for confirmation of whether the promotional pressure cited by Dick's reflects a broader industry trend or challenges specific to the Foot Locker integration.