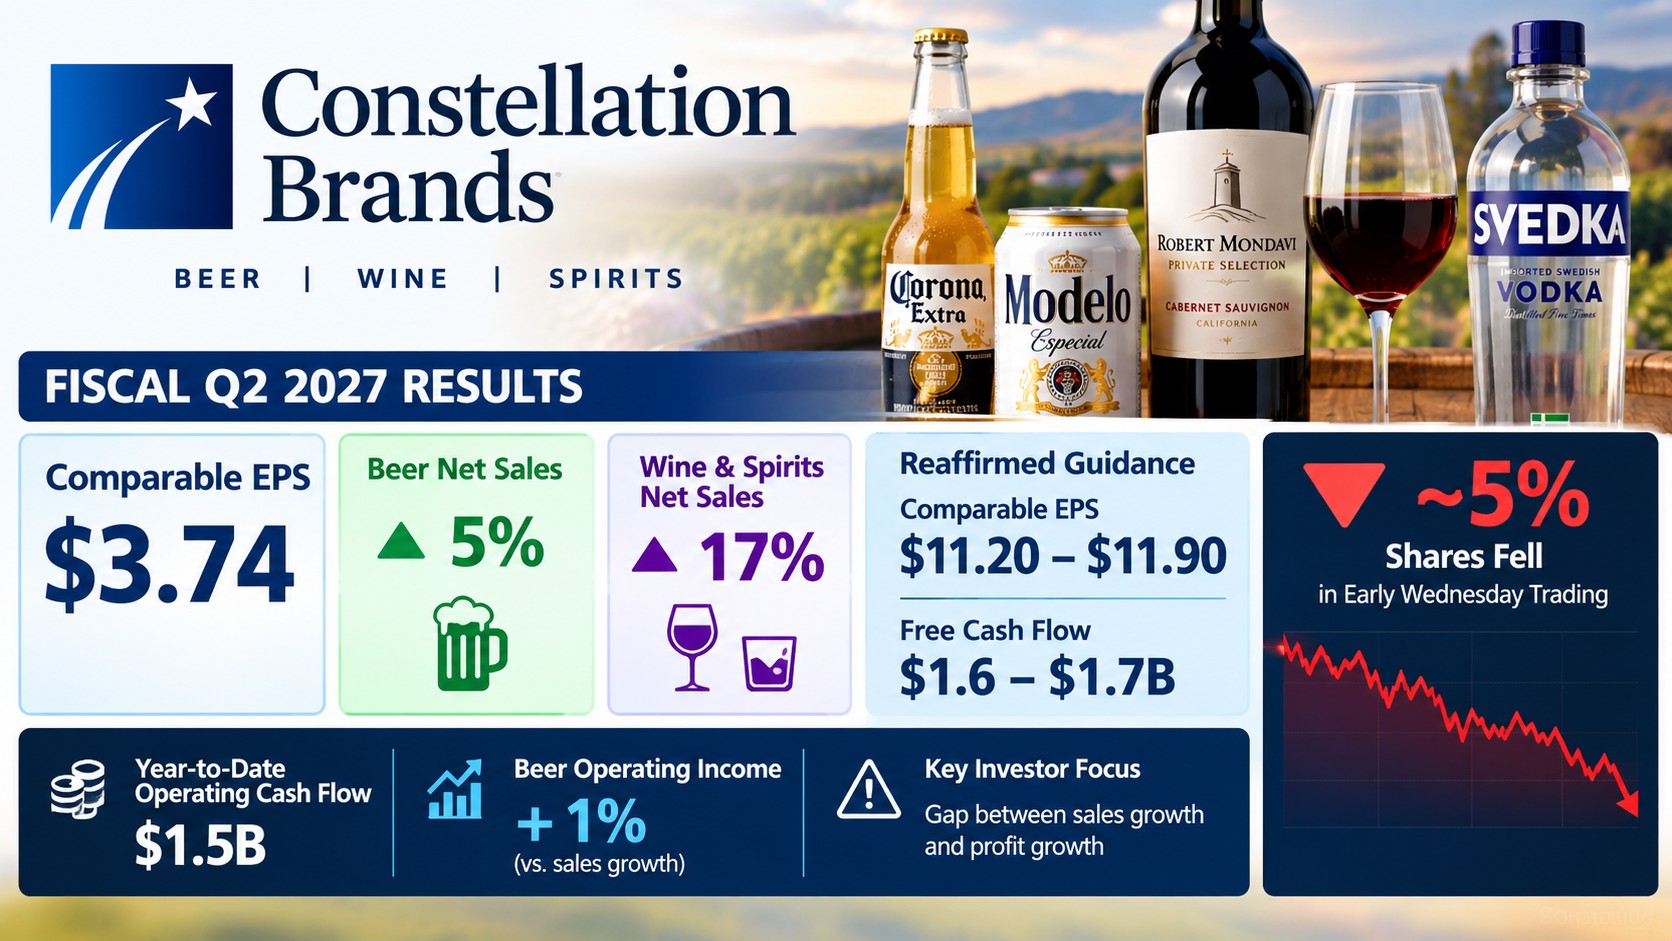
Constellation Brands, the maker of Corona and Modelo, reported fiscal second-quarter 2027 results after the close on Tuesday, October 6, posting comparable earnings per share of $3.74 and reported EPS of $3.32. Despite results that Yahoo Finance described as better than expected, the stock fell about 5% in Wednesday morning trading.
Segment detail showed a split picture. The beer business delivered net sales growth of 5% and operating income growth of 1%, while leading the category in dollar and volume share gains and outperforming the total beer category by 4 percentage points in year-over-year dollar and volume sales across Circana-tracked U.S. channels. The wine and spirits business posted net sales growth of 17% and depletions growth of 10.2%, and its wine portfolio ranked as the number three dollar share gainer in the total wine category.
Cash generation remained a bright spot. Year-to-date operating cash flow was $1.5 billion, a decrease of 1%, while free cash flow of $1.1 billion rose 4%. Management said the strong cash flow allowed it to continue executing its balanced capital allocation priorities through the first half of fiscal 2027.
On guidance, the company updated its fiscal 2027 reported EPS outlook to a range of $11.85 to $12.55 and reaffirmed comparable EPS of $11.20 to $11.90, an operating cash flow target of $2.4 billion to $2.5 billion and a free cash flow target of $1.6 billion to $1.7 billion. A reaffirmation, rather than a raise, can leave a stock vulnerable when expectations have been elevated into the print.
The sell-off highlights a familiar dynamic in consumer staples and beverage alcohol: top-line gains and market-share wins matter less to investors when profit growth lags. Beer operating income rising only 1% against 5% sales growth suggests costs or mix may be absorbing some of the growth, a topic management will likely address on its conference call, scheduled for 8:00 a.m. ET on Wednesday with CEO Nicholas Fink and CFO Garth Hankinson.
The report arrives against a challenging backdrop for consumer-facing companies. Oil above $101 a barrel and rising bond yields raise the prospect of higher fuel and borrowing costs for households, and coverage of the company's first-quarter report noted that the broader consumer environment showed signs of caution.
Constellation Brands has described itself as one of the fastest-growing large consumer packaged goods companies at U.S. retail, a positioning that raises the bar on both volume and profit delivery. In that context, a 5% decline on a day when major indexes were also under pressure suggests investors are applying a stricter lens to staples names that cannot show earnings growth keeping pace with sales.
For investors, the key questions are whether beer volume momentum can translate into stronger operating leverage in the second half, and whether the reaffirmed comparable EPS range proves conservative. The shares' reaction suggests the market wants evidence of margin recovery before rewarding share gains. Traders may watch the conference call commentary and any analyst estimate revisions for direction.
This article is for informational purposes only and does not constitute investment advice.