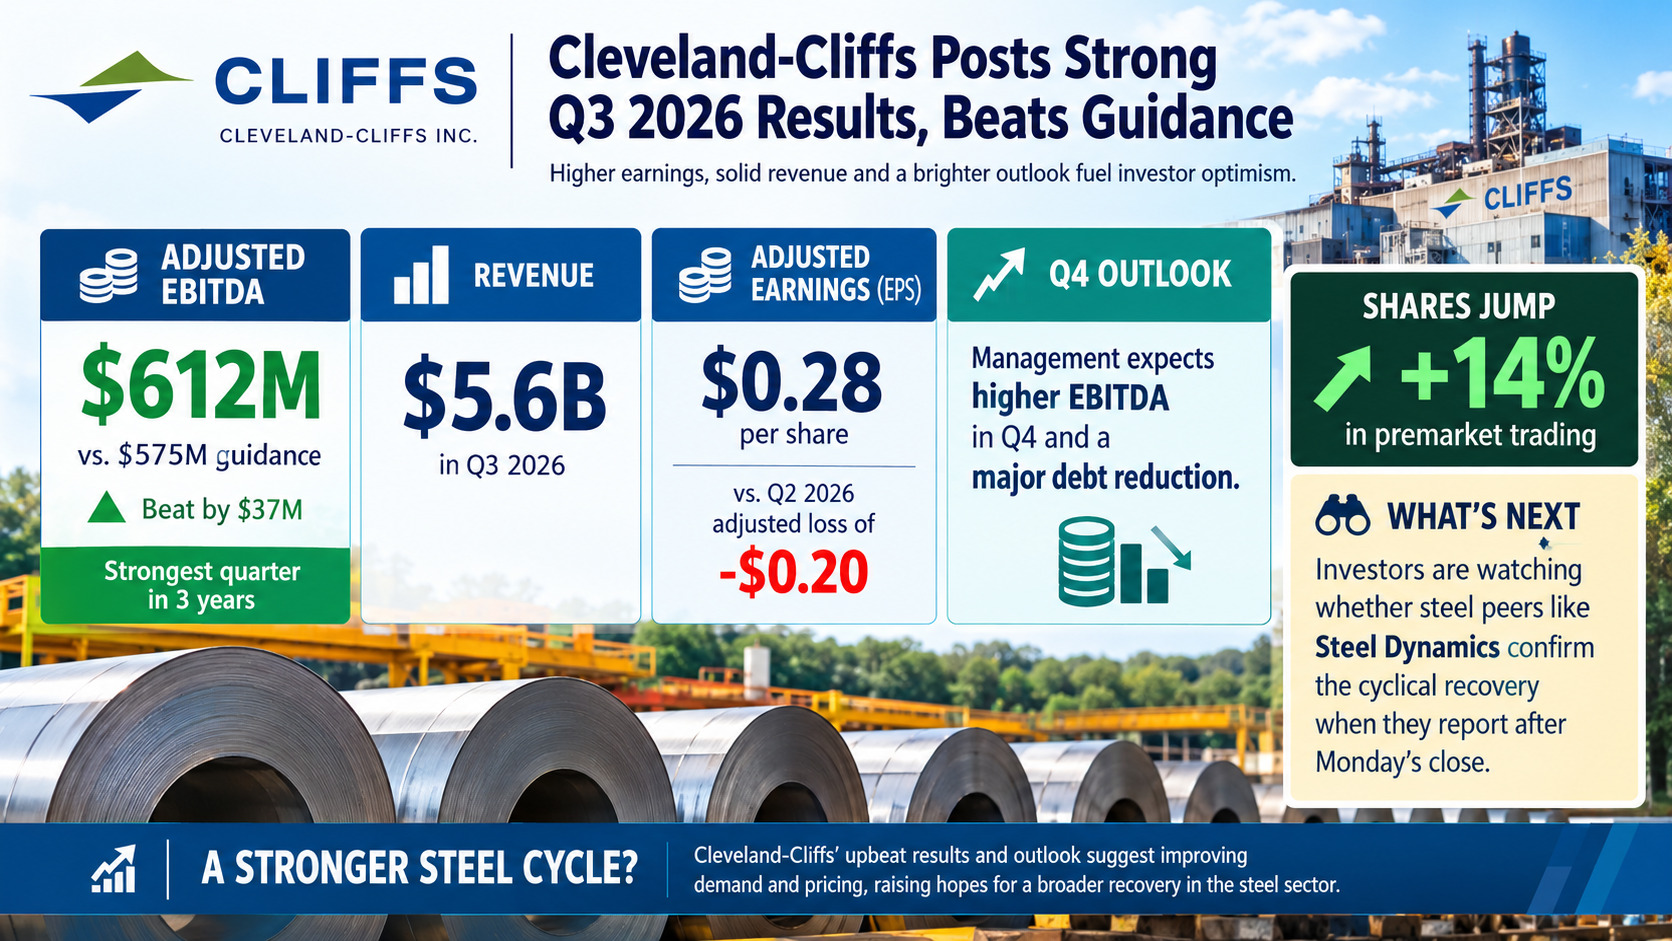
Cleveland-Cliffs reported third-quarter 2026 adjusted EBITDA of $612 million on Monday, October 19, beating the $575 million it guided to three months ago and marking what Chairman and CEO Lourenco Goncalves called the company's strongest quarter in three years. Shares jumped nearly 14% in premarket trading, making the steelmaker one of the day's top trending tickers on Stocktwits.
Revenue came in at $5.6 billion, up from $5.2 billion in the second quarter. The company posted GAAP net income of $165 million, or $0.26 per diluted share, with adjusted earnings of $0.28 per share, a swing from a second-quarter GAAP net loss of $134 million, or $0.25 per share. Earnings calendars had pointed to analyst expectations of about $0.22 per share for the quarter.
Adjusted EBITDA improved by $326 million from the $286 million posted in the second quarter. The company had signaled in July that selling prices, volumes and costs were all moving in the right direction, reporting an average net selling price of $1,124 per net ton for the second quarter, up from $1,048 in the first, and saying automotive volumes would increase further in the third quarter as finishing lines ran at higher utilization.
Management struck a confident tone on the outlook. Goncalves said he expects fourth-quarter adjusted EBITDA to rise further, even with typical seasonality and planned maintenance outages. The company also said it continued to reduce debt in the third quarter and expects a major debt reduction in the fourth quarter, supported by stronger free cash flow and property sale proceeds. He added that Stelco, its Canadian subsidiary, had its strongest quarter since Cleveland-Cliffs acquired it two years ago.
The company hosted a conference call at 8:30 a.m. ET to discuss results, and investors will look for detail on fourth-quarter pricing, tariff effects, automotive demand and the timing of property sales that underpin the debt reduction plan.
Why it matters: Cleveland-Cliffs has been a leveraged recovery story, with net losses in the first half of 2026, including a $229 million loss in the first quarter. A quarter that beats guidance and points to further improvement addresses the two main investor concerns, profitability and the balance sheet. Debt reduction would lower interest costs and could improve the equity's risk profile if executed as described.
For the broader market, the report offers an industrial and cyclical counterweight to a week dominated by AI-related volatility. Steel demand tied to automotive production is sensitive to tariffs, interest rates and consumer spending, so investors will watch whether peers such as Steel Dynamics, which reports after the close Monday, echo the strength. A strong read-through could support materials and industrial names even as technology shares remain unsettled.
Risks remain. Steel prices can reverse, auto production schedules can change, and a double-digit premarket gap can fade if the cash session lacks follow-through. Investors should also consider that the company's fourth-quarter guidance is qualitative and subject to maintenance timing.
This article is informational only and is not investment advice. Readers should review the company's filings and earnings presentation before making decisions.