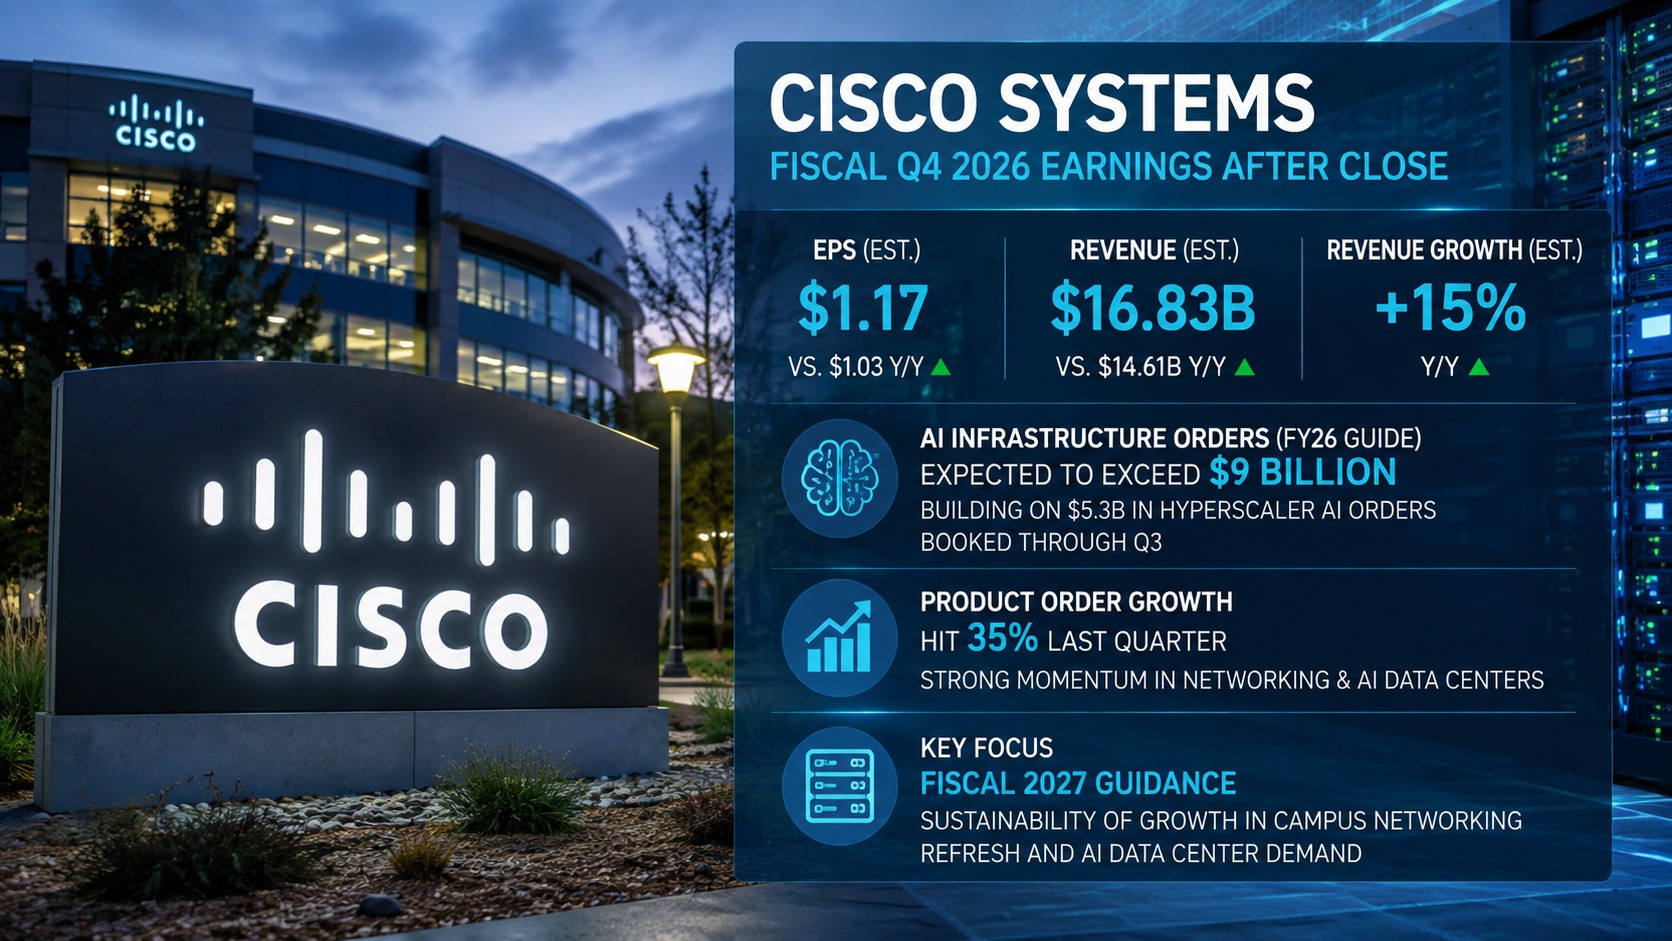
Cisco Systems is set to report fiscal fourth-quarter and full-year 2026 results after Wednesday's closing bell, in what analysts describe as one of the most closely watched prints of the earnings season for enterprise technology spending. Wall Street's consensus, drawn from 21 analysts, calls for earnings of $1.17 per share on revenue of approximately $16.83 billion, which would represent roughly 15% year-over-year growth. Cisco's own guidance range spans $16.7 billion to $16.9 billion in revenue and $1.16 to $1.18 in adjusted earnings per share.
The networking giant enters the print with substantial momentum. In its fiscal third quarter, product orders jumped 35% year-over-year, the strongest pace in more than a decade, while networking orders alone surged more than 50%. Growth was broad-based rather than concentrated among the largest cloud customers: enterprise orders rose 18%, public-sector orders climbed 27%, and service-provider and cloud orders soared 105%. By the end of the third quarter, Cisco had already accumulated $5.3 billion in hyperscaler AI infrastructure orders, supported by its Silicon One networking systems and Acacia optics business.
UBS analyst David Vogt, who maintains a Buy rating and $132 price target on the stock, said industry checks and commentary from hyperscalers and neoclouds suggest AI infrastructure demand accelerated further over the past three months. He estimated Cisco's networking revenue could reach $9.6 billion for the quarter, implying 26% year-over-year growth and an acceleration from the prior quarter's 25% pace. Vogt does expect product order growth to moderate to around 29%, down from the third quarter's 35%, though he flagged room for upside driven by strength in pluggable optics.
Beyond the headline numbers, investors are expected to focus heavily on management's commentary regarding fiscal 2027, including margin trajectory and the durability of AI-related order growth. For the full fiscal year, Cisco has targeted revenue between $62.8 billion and $63.0 billion alongside adjusted earnings per share of $4.27 to $4.29. Any signal that the AI and campus networking refresh cycles remain intact into next year could reinforce the view among some investors that Cisco has become a genuine AI infrastructure beneficiary rather than a legacy hardware story.
Cisco shares have gained roughly 59% year-to-date heading into the report, reflecting investor enthusiasm around the company's AI infrastructure exposure, though the stock has recently traded in a narrower range near resistance around $124.62. Options markets and recent trading activity point to a mixed setup, with low short interest but net selling pressure in the days leading into the print, according to data compiled by StockTitan.
The report also arrives alongside a broader wave of technology and networking sector data points this week, giving investors a fuller picture of enterprise capital spending trends heading into the back half of 2026. A strong beat-and-raise from Cisco could lend further support to the semiconductor and networking-equipment rally already underway in Wednesday's session, while any disappointment on order growth or fiscal 2027 guidance could reignite concerns about the sustainability of AI infrastructure spending more broadly.