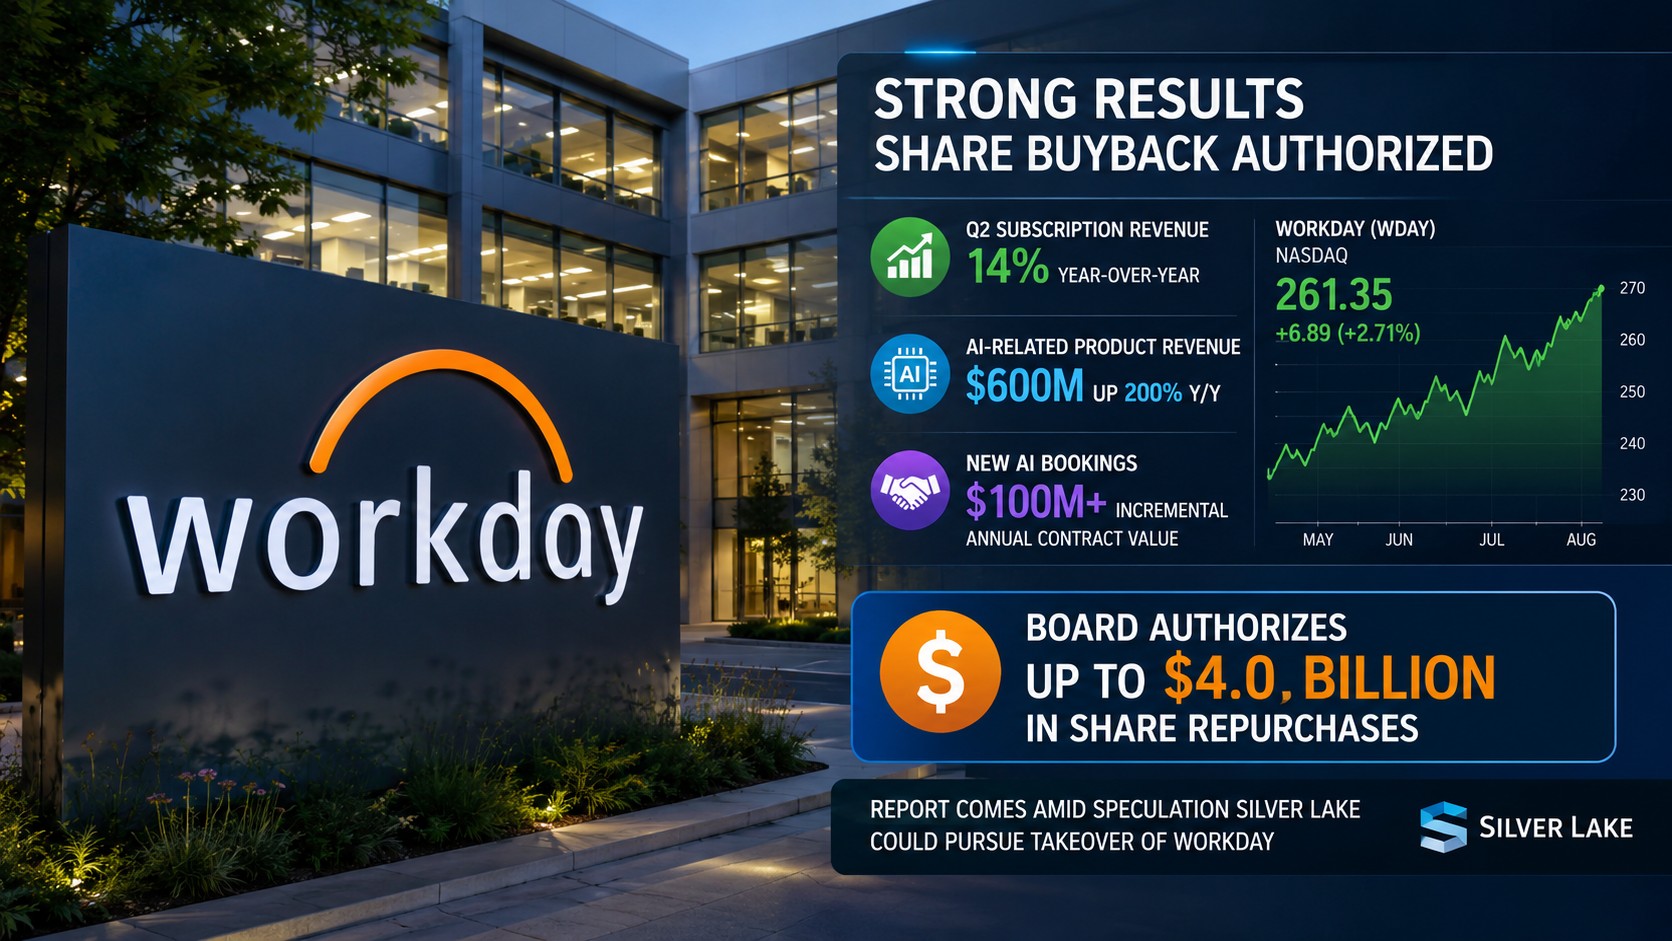
Workday's board of directors authorized the repurchase of up to $4.0 billion of the company's outstanding Class A common stock, the enterprise software maker announced alongside fiscal second-quarter 2027 results that topped Wall Street's expectations across key metrics.
The company reported subscription revenue growth of 14% year-over-year, continuing a trend of steady, if unspectacular, top-line growth for the human capital management and financial software provider. The more notable figures came from Workday's artificial intelligence product lines, where revenue from AI-specific SKUs reached $600 million, up 200% year-over-year, while new AI bookings contributed more than $100 million in incremental annual contract value during the quarter.
Thursday's report landed amid weeks of speculation that private equity firm Silver Lake could pursue a takeover of Workday, chatter that analysts said had helped drive a roughly 48% surge in the stock over the trailing three months, a rally some cautioned had gotten ahead of the company's underlying fundamentals. Thursday's beat-and-raise quarter, combined with the sizable buyback authorization, gives investors a fundamental data point to weigh against the buyout speculation that had been a significant driver of recent stock performance.
Prediction markets had assigned Workday a 91% probability of beating earnings estimates heading into the report, and the company delivered its fourth consecutive quarterly beat, according to analysts tracking the stock. Workday's non-GAAP operating margin came in at a healthy level, and operating cash flow continued to grow at a double-digit pace, metrics that analysts said support the company's continued capital return program even as it invests in expanding its artificial intelligence product suite.
Following the results, analyst reaction was mixed. Jefferies analyst Brent Thill lowered his price target on Workday to $220 from $225 while maintaining a Hold rating, citing concerns that the company lacks a sufficiently differentiated AI strategy relative to peers. DA Davidson, by contrast, raised its price target to $190 from $135 while maintaining a Neutral rating, citing the better-than-expected quarterly results even as the firm remained cautious on valuation.
Workday has increasingly positioned its agentic AI capabilities, which allow the software to autonomously complete certain human resources and finance workflows, as a key differentiator against larger competitors including Oracle and Salesforce in the broader enterprise software market. The company said adoption of these AI tools continues to expand across its customer base, with more than 4,000 customers now live on its agentic AI offerings.
The $4 billion buyback authorization represents a significant commitment relative to Workday's current market capitalization and signals management's confidence in the stock's valuation even amid the ongoing takeover speculation. Investors will be watching for any further developments on the Silver Lake talks in the coming weeks, alongside continued execution on Workday's AI product roadmap heading into the second half of fiscal 2027.