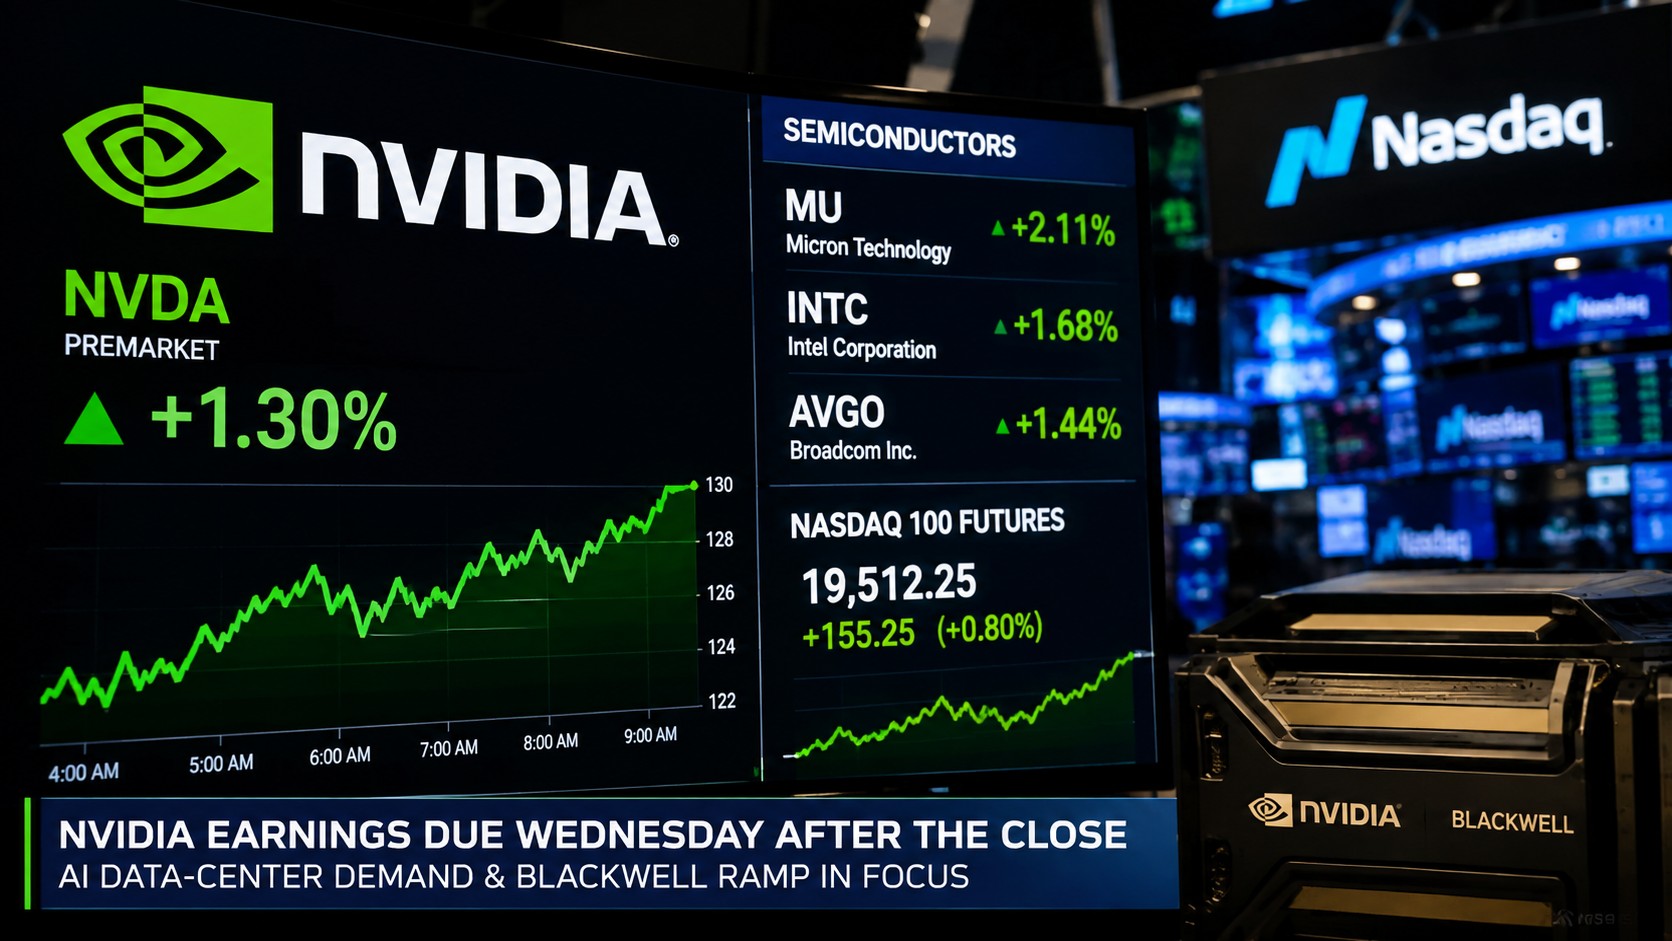
Nvidia shares advanced approximately 1.3% in premarket activity on Tuesday, leading a broader recovery among semiconductor and AI-related names after a heavy sell-off the previous session. Micron Technology gained more than 2%, Intel climbed over 3% in some quotes, and Broadcom also moved higher, helping Nasdaq 100 futures rise between 0.75% and 1%.
The rebound follows Monday’s decline in which the Philadelphia Semiconductor Index fell more than 2.5% and Nvidia itself closed lower for a seventh consecutive session at one point in the recent streak. Investors had grown cautious about lofty valuations and the sustainability of AI infrastructure spending even as demand for advanced GPUs remained robust.
Attention is now firmly fixed on Nvidia’s fiscal results scheduled for release after the market close on Wednesday. The report is expected to deliver updated commentary on Blackwell GPU shipments, data-center revenue growth, and forward guidance that will shape sentiment across the entire AI ecosystem. Analysts will scrutinize any signs of supply constraints, customer concentration, or margin pressure.
Softer oil prices and a modest pullback in Treasury yields provided a constructive backdrop for the premarket bounce. West Texas Intermediate retreated toward the low $82 area and the 10-year yield eased to around 4.66–4.67%, reducing some of the valuation pressure that had weighed on long-duration growth stocks.
Beyond Nvidia, the calendar remains heavy. The July personal consumption expenditures price index lands Wednesday morning, offering the Federal Reserve’s preferred inflation gauge ahead of Chair Kevin Warsh’s Jackson Hole remarks on Friday. Software names Intuit and Zoom are also due to report results later Tuesday, adding further tech-sector color.
For equity investors the near-term path hinges on whether Nvidia can reaffirm the durability of AI demand without introducing new concerns about capital intensity or competitive intensity. A clean beat and constructive outlook would likely extend the premarket recovery; any disappointment could quickly reverse the gains seen Tuesday morning.