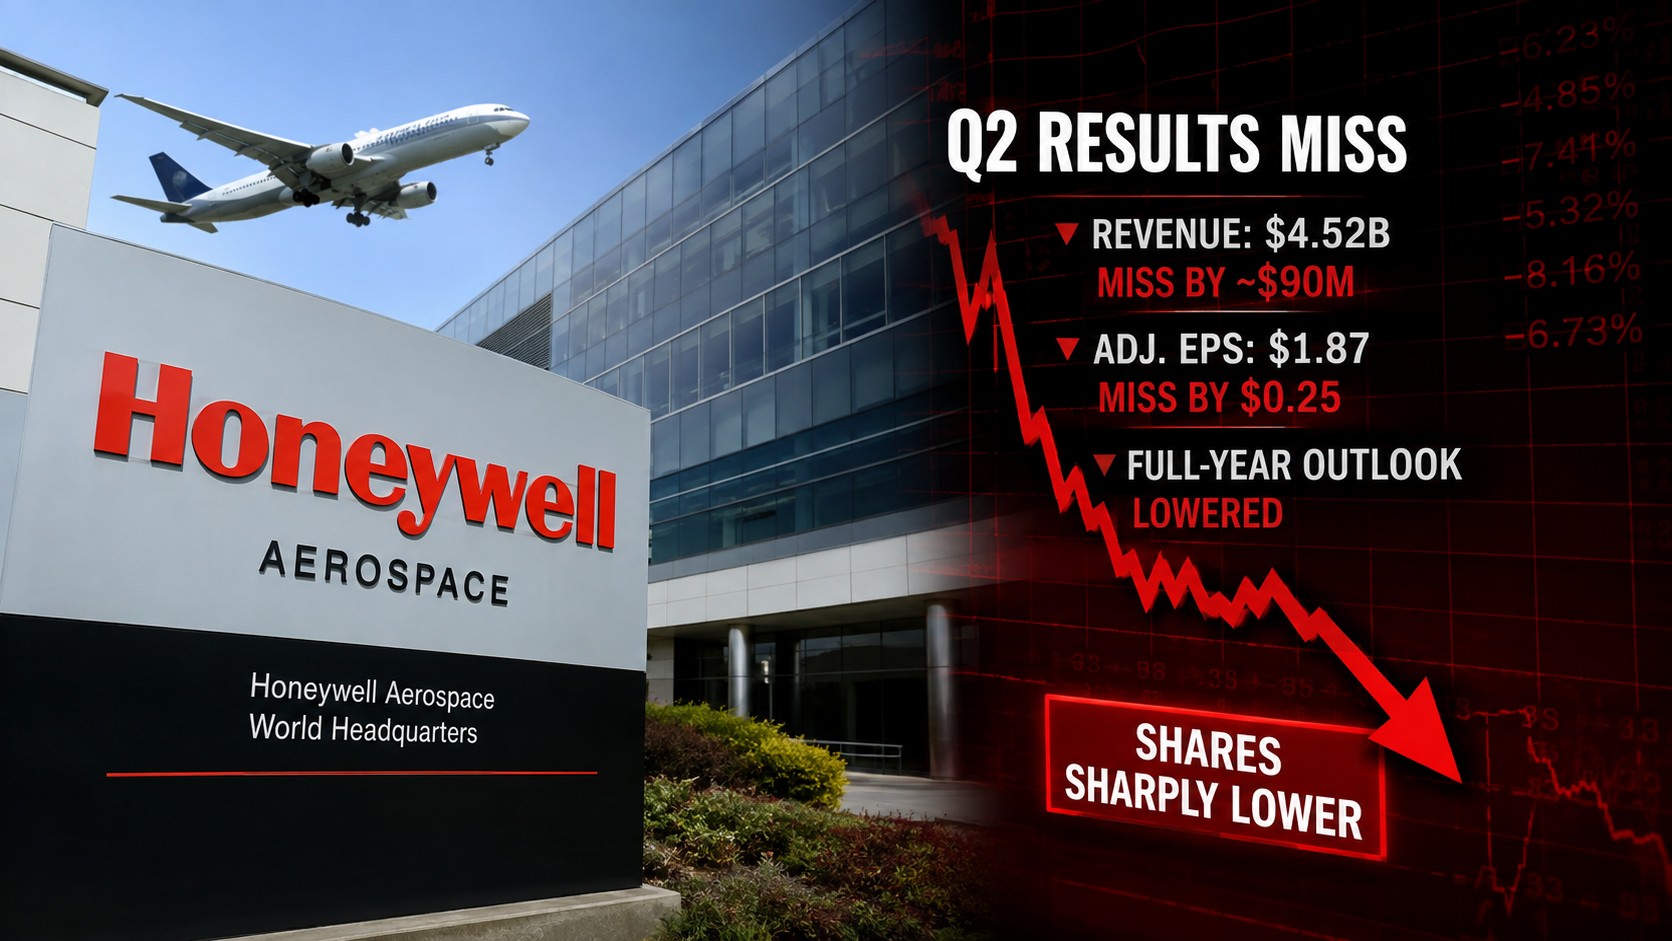
Honeywell Aerospace posted second-quarter results that fell short of Wall Street expectations and reduced its full-year outlook, triggering a steep decline in the newly independent stock. Revenue came in at $4.52 billion, up 5.4% year-over-year but approximately $90 million below consensus. Non-GAAP earnings per share of $1.87 missed estimates by $0.25.
Adjusted EBIT declined 7%, reflecting roughly $100 million of separation-related costs and inventory charges. Backlog rose 9% to $18.2 billion and trailing twelve-month orders increased 8%, led by Defense and Space, indicating longer-term demand remains intact. However, near-term execution and margin pressure dominated the reaction.
Management revised full-year organic growth guidance downward to 4% to 5% from the prior 7% to 9% range and cut pro forma standalone adjusted EBIT expectations to $4.35 billion to $4.45 billion from $4.65 billion to $4.75 billion. The company also issued pro forma standalone adjusted EPS guidance of $7.60 to $7.90.
Shares of the aerospace pure-play, which separated from Honeywell Technologies in late June, fell sharply in early trading, with some reports indicating declines approaching 25% at the lows. The miss highlights challenges in the post-spin transition period and investor sensitivity to any deviation from previously communicated growth trajectories.
Defense and commercial aerospace trends continue to provide a multi-year tailwind, yet the combination of one-time costs, a guidance reduction, and high expectations produced a clear negative verdict. Investors will focus on sequential improvement in the second half and the pace at which separation costs abate.
The result adds to a mixed bag of industrial and aerospace reports this earnings season and contributes to selective pressure within the broader industrials complex even as the Dow remains near record levels.