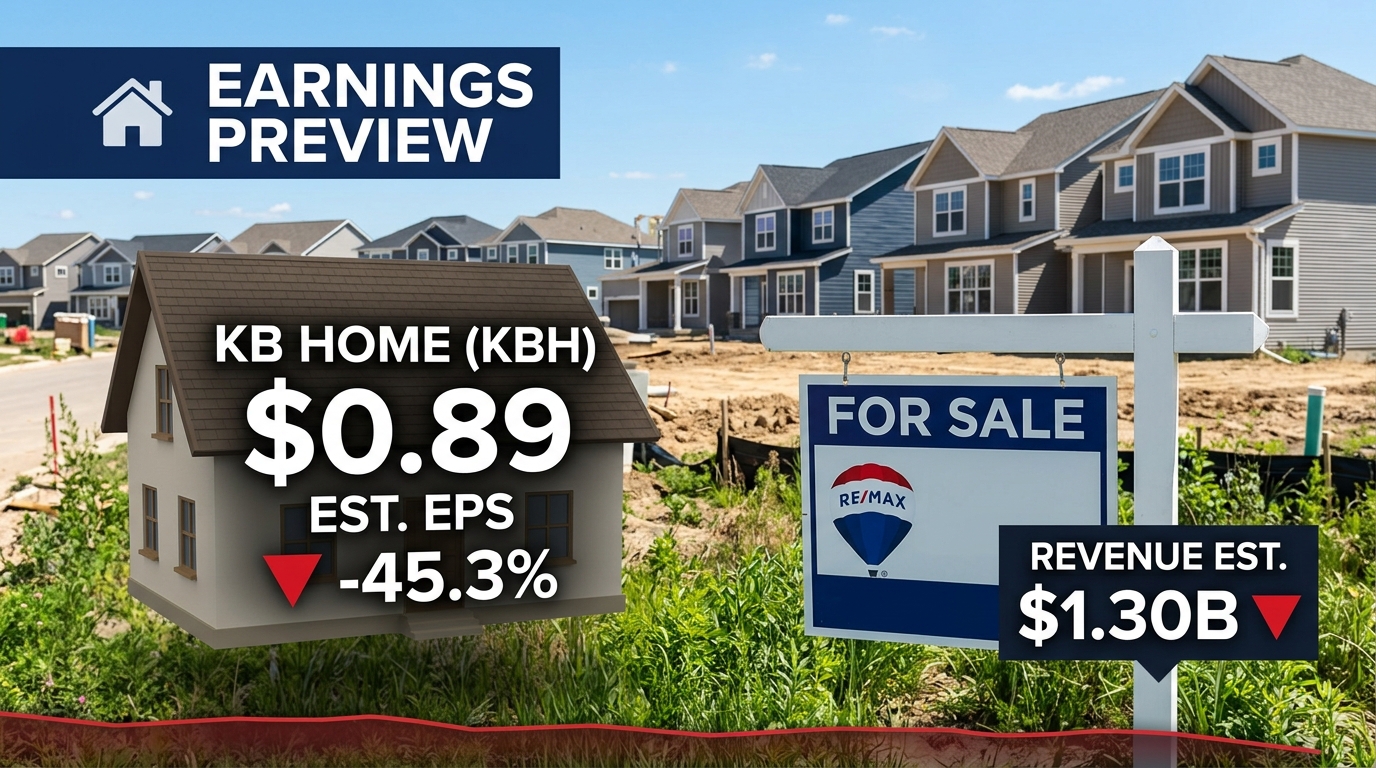
KB Home is scheduled to release fiscal third-quarter 2026 results after the market closes today, and Wall Street is bracing for one of the steepest earnings declines the homebuilder has posted in recent memory. The consensus estimate calls for adjusted earnings per share of approximately $0.89, which would mark a 45.3% drop from the $1.61 per share KB Home reported in the same period last year.
Revenue for the quarter ended August 31 is expected to come in near $1.30 billion, representing a projected 20.2% year-over-year decline. The forecast reflects an accelerating slowdown from the prior quarter, when KB Home's revenue fell 27% year over year even as the company narrowly beat the top-line consensus.
Sentiment among sell-side analysts has grown more cautious heading into the print. Zacks Research reduced its third-quarter EPS estimate to $0.86 from $0.87 in a note published Friday, and the firm currently carries a "Strong Sell" rating on KB Home shares. Zacks also lowered its full-year 2026 earnings forecast, projecting annual EPS of roughly $3.27, well below the profitability the homebuilder posted in 2025.
The deteriorating outlook stems largely from an increasingly difficult housing backdrop. Thirty-year mortgage rates have climbed toward the 7% threshold in recent months, squeezing affordability for prospective buyers already contending with elevated home prices. Resale inventory has also risen in several of KB Home's core markets, intensifying competition from existing homes that are frequently priced more aggressively than new construction.
KB Home's stock has traded around $48.50 heading into the report, reflecting the market's already-diminished expectations for the quarter. Analysts covering the stock note that while a 45% profit decline sounds alarming in isolation, KB Home has historically beaten depressed consensus estimates in two of its last four quarters, suggesting the bar for a positive surprise may not be as high as the headline decline implies.
Insider selling activity has drawn some scrutiny ahead of the report. Regulatory filings show that a company director and an executive vice president each sold shares in recent weeks, transactions that, while not unusual for scheduled diversification, have added a layer of caution among some investors watching the stock into earnings.
Beyond the headline numbers, investors will be watching KB Home's forward guidance closely for commentary on order trends, cancellation rates, and incentive spending, all of which have become key swing factors for homebuilders navigating an affordability-constrained market. Peers across the sector have adopted more aggressive pricing incentives to preserve sales volume, a strategy that tends to compress gross margins even when unit deliveries hold up.
KB Home's results will also be read as a bellwether for the broader homebuilding sector heading into the final stretch of 2026, a year in which persistently high borrowing costs and a still-elevated Federal Reserve policy rate have weighed heavily on new-home sales nationwide. With the company's earnings call scheduled for 5:00 p.m. Eastern Time today, investors and analysts will be listening closely for any signal on whether the worst of the housing downturn is behind the industry or still ahead of it.