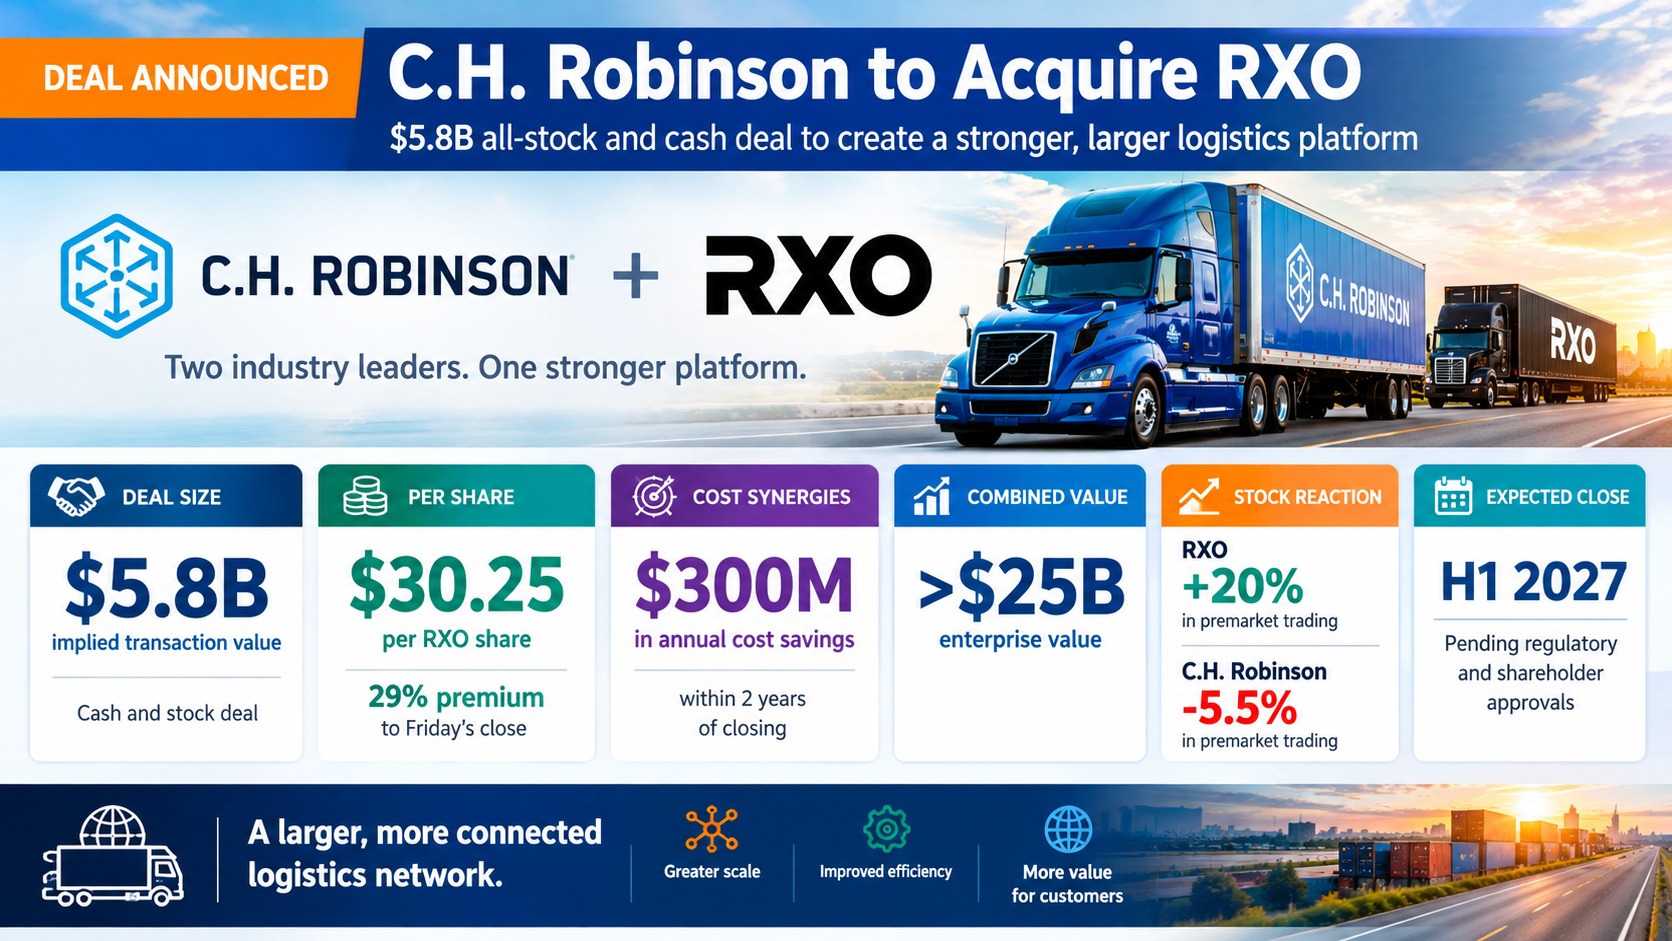
C.H. Robinson Worldwide (CHRW) agreed on Monday to acquire trucking brokerage RXO Inc. (RXO) in a cash-and-stock transaction with an implied value of $5.8 billion, a major consolidation move in freight brokerage that lands at a challenging time for the industry. RXO shareholders will receive $17.25 in cash and 0.0856 shares of C.H. Robinson for each RXO share, an implied $30.25 per share and a 29% premium to RXO's closing price on October 2.
Shares reacted in opposite directions. RXO jumped more than 20% in premarket trading, while C.H. Robinson fell about 5.5%, a familiar pattern when an acquirer commits capital, takes on debt and promises integration benefits that still have to be delivered. The companies expect the deal to close in the first half of 2027, subject to regulatory and shareholder approvals.
The consideration is flexible. RXO holders can elect all-cash consideration of $30.25 per share or an all-stock exchange of 0.1992 C.H. Robinson shares, subject to proration so that roughly 57% of the aggregate payment is cash and 43% is stock. Those taking stock are expected to own about 11% of the combined company. MFN Partners, which holds about 17% of RXO, has agreed to vote in favor, and Orbis Investments, described as RXO's largest shareholder, publicly backed the transaction.
Strategically, the combination creates an enterprise value above $25 billion. C.H. Robinson brings a global forwarding and multimodal network, while RXO contributes a North American truck brokerage business along with expedited and last-mile operations. Management is targeting $300 million in annual cost synergies within two years of closing, which it plans to unlock by applying its Lean AI operating model across RXO's operations and integrating the business mainly into its NAST division.
The price is not small. One merger-arbitrage tracker calculates that C.H. Robinson is paying roughly 49.7 times EBITDA for RXO, and GuruFocus noted that C.H. Robinson shares were already trading about 54% above its own intrinsic value estimate. To finance the purchase, C.H. Robinson will take on additional debt and put share buybacks on hold while it pays that debt down. Axios noted the company had paused dealmaking for five years before buying cold-chain specialist DeSpir Logistics for $75 million in June.
For traders, the setup involves two distinct stories. RXO now trades as a merger target whose value is tied partly to C.H. Robinson's share price, because most holders will receive a mix of cash and stock, so the spread to $30.25 will be watched closely. C.H. Robinson, meanwhile, must convince investors that $300 million in savings justifies the premium and the added leverage, particularly with the 10-year Treasury yield near 5.25% and borrowing costs elevated.
Execution and industry risks also remain. Goldman Sachs advised RXO and Paul, Weiss, Rifkind, Wharton and Garrison served as its legal counsel, but the transaction still needs shareholder and regulatory sign-off, and trade press has flagged litigation exposure for large brokers following the Lipe verdict. This article is for informational purposes only and is not investment advice.