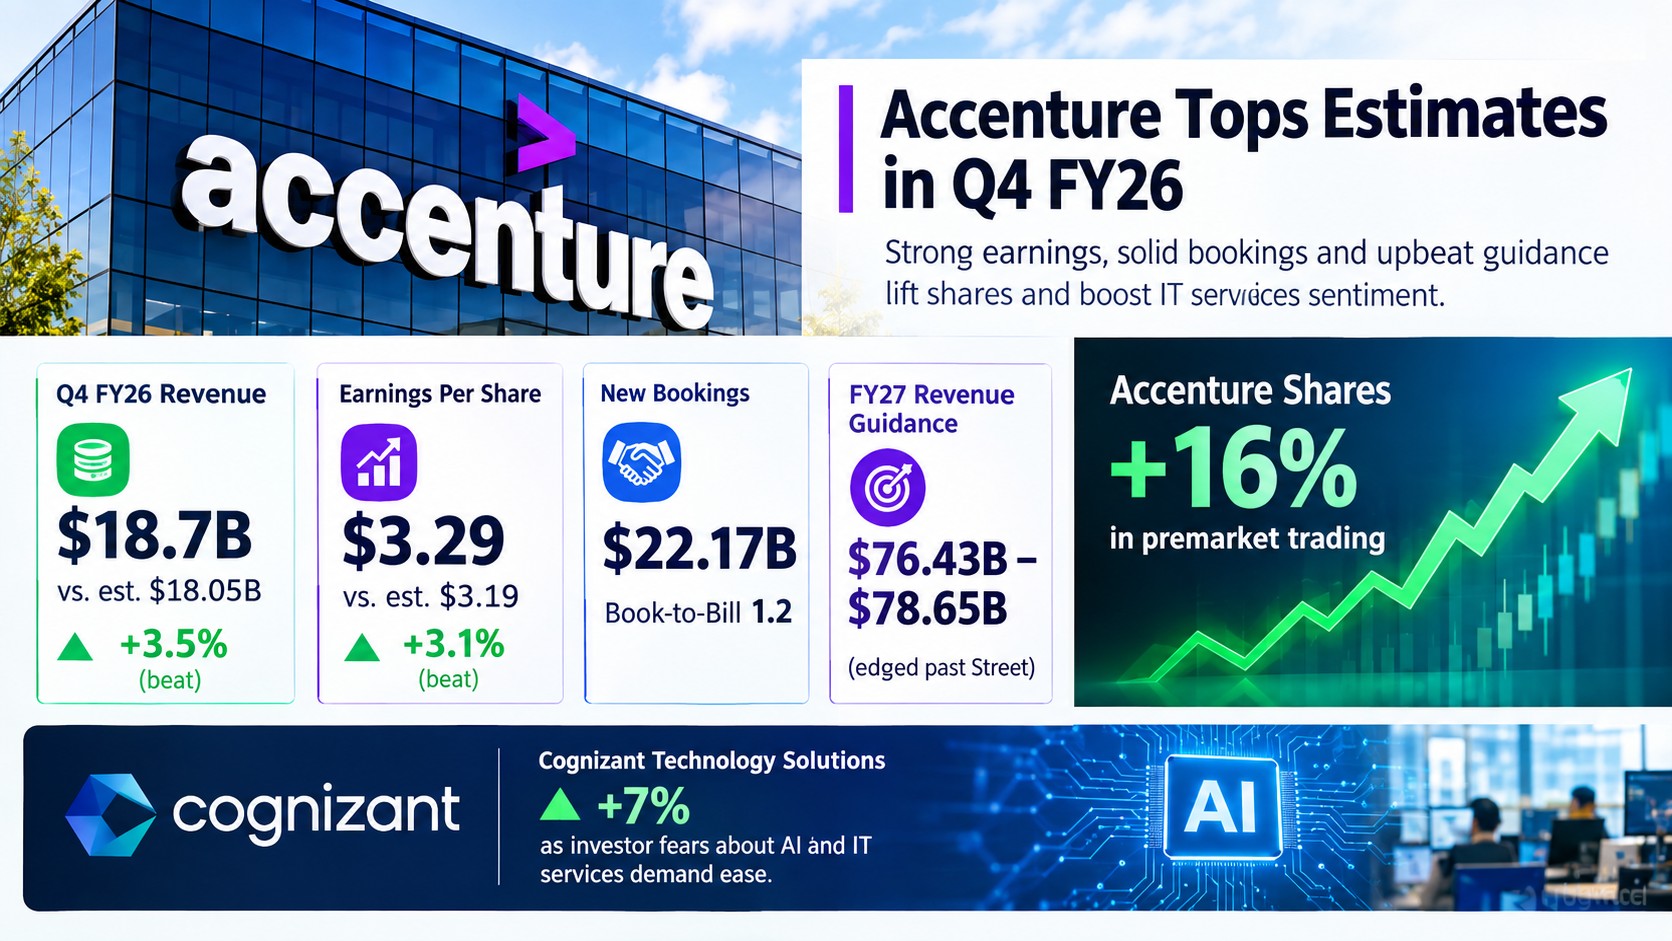
Accenture (ACN) shares surged in premarket trading on Thursday after the consulting and technology services company reported fiscal fourth-quarter 2026 results that beat estimates and issued a fiscal 2027 outlook above Wall Street expectations. The stock jumped about 16% before the open, according to premarket data, after having fallen roughly 32% so far in 2026 on worries that artificial intelligence could erode demand for traditional services work. Investors had been focused on fiscal 2027 guidance, bookings, and the pace at which AI-related demand is translating into revenue.
Revenue for the quarter ended August 31 was $18.7 billion, compared with Wall Street's estimate of about $18.05 billion. Earnings per share were $3.29, ahead of the $3.18 to $3.19 consensus. GAAP operating margin was 15.3%, up 370 basis points from the year-earlier quarter, which included business optimization costs. New bookings were $22.17 billion, up 4% in U.S. dollars and 5% in local currency, for a book-to-bill ratio of 1.2.
Chair and CEO Julie Sweet said the company exceeded its fourth-quarter revenue guidance and ended the year with broad-based growth. Financial Services revenue increased 5% to $3.5 billion, while Resources revenue rose 6% to $2.5 billion. The strong level of large client bookings addressed one of the central investor concerns heading into the report: whether AI-related demand is arriving fast enough to offset pressure on older work.
The fiscal 2027 outlook did much of the work. Accenture expects full-year revenue growth of 3% to 6% in local currency, translating to revenue of $76.43 billion to $78.65 billion versus the $76.41 billion analyst estimate. Adjusted earnings are guided to $14.39 to $14.81 per share versus a $14.63 consensus, and the company plans to return at least $9.5 billion to shareholders. For the first quarter, it projects revenue of $18.95 billion to $19.60 billion.
The read-through extended across the sector. Cognizant Technology Solutions (CTSH) climbed about 7% in premarket trading as investors repriced a group that has been punished this year amid worries that automation could shrink the addressable market for outsourced technology services. A sustained recovery would depend on whether bookings translate into revenue and whether pricing holds as clients ask for AI-enabled delivery.
Context matters. Before the report, Accenture had lowered its fiscal 2026 revenue growth outlook to 3% to 4% in local currency following its third-quarter results, and the stock remained well below its late-2021 record. Thursday's move therefore partly reflects relief from depressed expectations rather than a clean change in trend, and investors will want to see continued bookings strength in coming quarters.
Treasury yields at their highest since 2002 and oil above $90 a barrel remain the main macro risks for the group, as higher rates can weigh on corporate technology budgets. Still, the combination of a double beat, an above-consensus guide and a large shareholder return commitment gives momentum traders a clear catalyst, while value-oriented investors may wait for confirmation after the opening gap. Gaps of this size often retrace partly in the first hour, so entry discipline is critical.