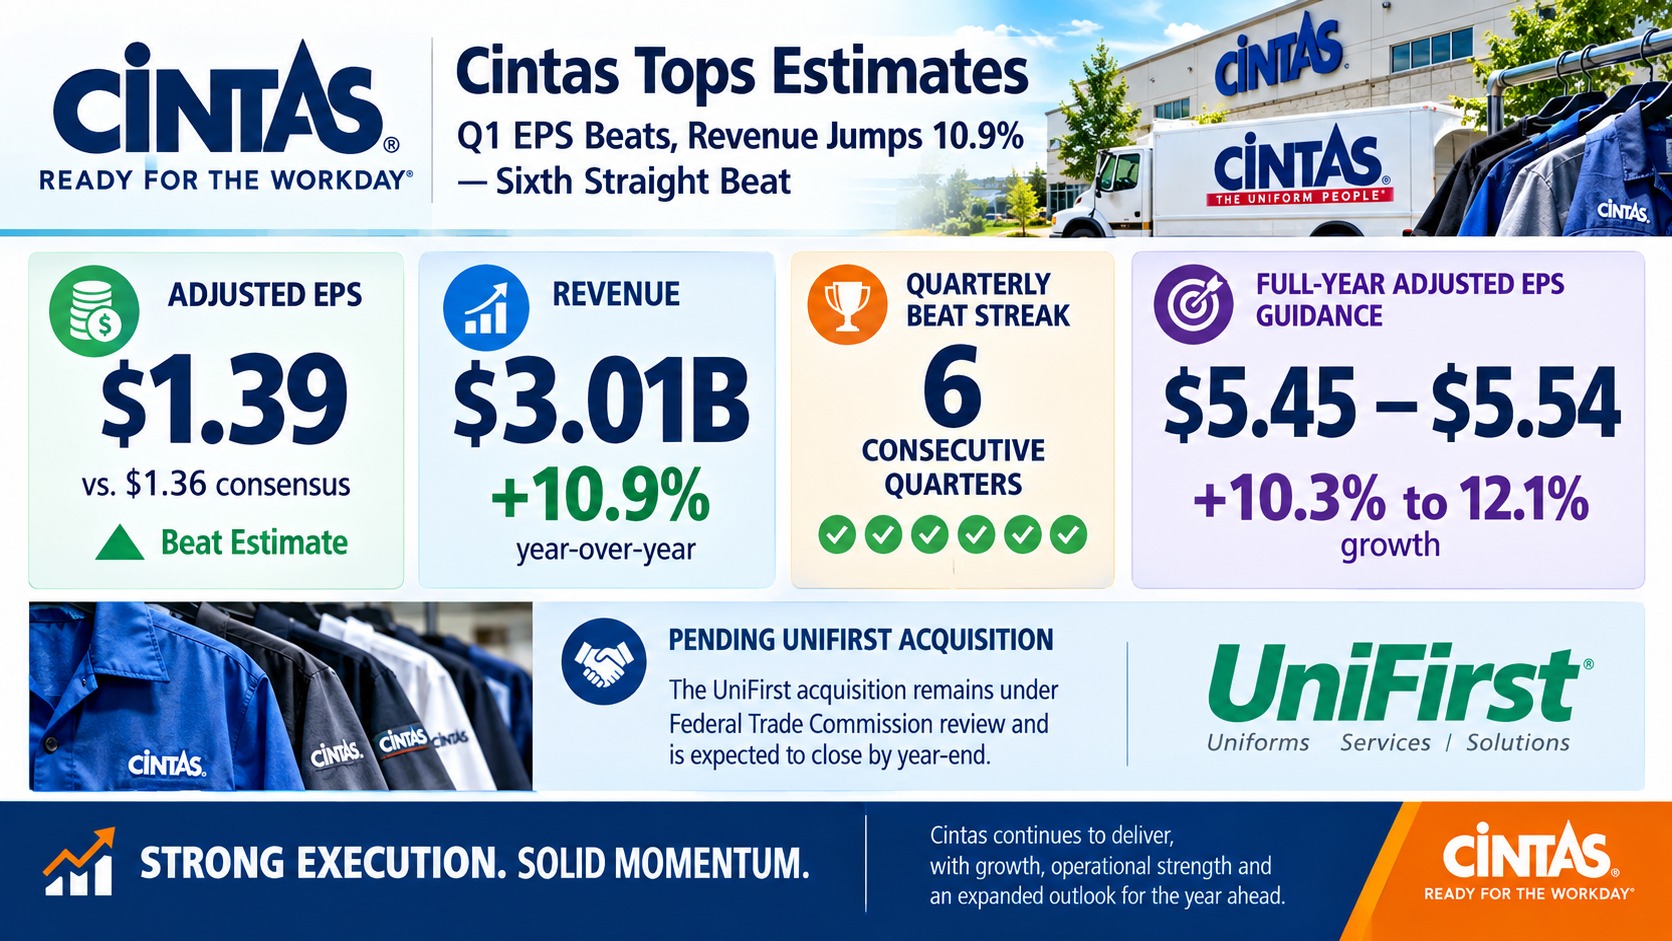
Cintas Corporation delivered another quarter of outperformance Wednesday, reporting fiscal first-quarter 2027 adjusted diluted earnings per share of $1.39, ahead of the $1.36 Wall Street consensus, while revenue rose 10.9% year-over-year to $3.01 billion. The print marked the sixth consecutive quarter in which the uniform rental and facility services company has topped analyst expectations, reinforcing its reputation as one of the steadiest compounders in the industrial services sector.
Growth was broad-based across the company's business lines. The core Uniform Rental and Facility Services segment, which supplies corporate identity garments, mats, and restroom supplies to businesses nationwide, grew 9.7% during the quarter. First Aid and Safety Services was the standout performer, continuing a trend of ancillary services outgrowing the legacy rental business as Cintas cross-sells additional offerings into its existing customer base. Chief Executive Officer Todd Schneider credited ongoing investments in technology, capacity, and talent for the broad-based strength.
Encouraged by the momentum, management raised its full-year fiscal 2027 guidance on both revenue and profitability. The company now expects adjusted diluted EPS in a range of $5.45 to $5.54, representing growth of 10.3% to 12.1% over fiscal 2026 — a figure that notably excludes any contribution from Cintas's pending acquisition of rival uniform provider UniFirst. That deal, first announced earlier this year, would meaningfully expand Cintas's footprint in the uniform rental industry once completed.
The UniFirst transaction remains the primary swing factor for investors evaluating Cintas shares heading into year-end. The deal has been unanimously approved by both companies' boards, and entities affiliated with UniFirst's founding Croatti family, which control roughly two-thirds of the voting power of UniFirst's common stock, have already agreed to vote in favor of the transaction. Cintas has also lined up fully committed bridge financing from Morgan Stanley, KeyBank, and Wells Fargo to fund the acquisition.
The one remaining obstacle is regulatory approval. Schneider said Wednesday that Cintas continues to engage with the Federal Trade Commission on its review of the deal and still expects the transaction to close before the end of calendar 2026, though the timeline ultimately depends on the agency's findings. Until the review concludes, Cintas's standalone guidance does not yet reflect the added scale UniFirst would bring.
Shares of Cintas, which closed at $198.82 ahead of Wednesday's report, have carried a premium valuation into the print given the company's consistent beat-and-raise track record. That leaves comparatively little room for disappointment, and investors will be parsing management's commentary on customer retention, new business pipelines, and pricing sustainability in the uniform rental segment for clues about whether the current growth trajectory can be sustained into the back half of the fiscal year. With six straight quarters of upside surprises now in the books, Wall Street's bar for Cintas keeps climbing — even as the company keeps clearing it.